
Get a 500 Credit Score Personal Loan From These Fast Online Lenders
Last updated: 2026-10-16
Navigating a financial drought with a 500 credit score can feel like wandering through a dense mist without a map. You might feel like the walls are closing in. Many folks mistakenly believe a low rating acts as a permanent barrier to entry.
In reality, it is often just a temporary roadblock on your journey. The real secret to finding breathing room lies in locating a lender that sees the human behind the digits. They need to look beyond that solitary, underwhelming number.
Generally, a score around 500 lands you in the “very poor” bracket. If you approach big banks or premium credit card companies, expect a quick “no.” They aren’t built for these types of risks. It’s a tough pill to swallow.
However, the credit landscape isn’t entirely closed to you. You just need to pivot your approach. Instead of knocking on the doors of mainstream institutions, start scouting for specialty lenders who specialize in these unique situations.
When you hunt for a loan, remember that getting the money is only half the battle. You have to ensure the terms don’t become a millstone around your neck. A bad deal can quickly turn a minor setback into a catastrophe.
Consider the math: a $5,000 loan at 36% APR is a much heavier burden than one at 25% APR over 36 months. That extra interest adds up fast. You could end up throwing thousands of dollars down the drain instead of building savings.
We have curated this list to highlight lenders that value speed and accessibility. These are the companies helping people patch up their finances. They focus on those who are actively trying to mend their credit standing.
- Avant
- OneMain Financial
- FastLendGo
- Reprise
- United Finance
- OppLoans
Our Method for Ranking Providers
When we set out to find the best options for those with a 500 credit score, our primary compass was accessibility. Traditional banks often slam the door on anyone in the “poor” credit bracket. Consequently, we spent our time hunting for lenders that specialize in helping people with less-than-ideal credit histories.
We placed a huge premium on companies that don’t treat your FICO score like a fragile glass vase. Specifically, we looked for lenders that permit you to start the application process without an immediate penalty to your credit standing. It is all about keeping your options open without causing extra damage.
A “soft pull” is a lifesaver in these scenarios because it lets you peek at interest rates and loan terms without a “hard pull” scarring your report. When your financial health is already on shaky ground, you need to scout the field carefully. This allows you to shop around without making your situation even more precarious.
Speed and honesty were the other two pillars holding up our selection process. Life doesn’t wait for a perfect credit score to throw a curveball. Whether it is a sudden trip to the mechanic, a surprising medical invoice, or a looming utility bill, people often need cash in a heartbeat.
Because of this, we gave the spotlight to lenders capable of making lightning-fast decisions or offering same-day transfers. However, we didn’t just reward speed; we also ensured their repayment structures remained fair and manageable. We weren’t interested in predatory traps that offer quick cash but demand a mountain of interest in return.
We relied heavily on the “time-to-cash” metric to separate the wheat from the chaff. This specific measurement tracks the clock from the second you click “submit” on your digital application until the actual dollars land in your personal checking account. If they were too slow, they didn’t make our cut.
The Reality of Borrowing with Limited Credit
Before you sign on the dotted line with anyone on this list, you must face the cold, hard math of high-interest debt. When your score hovers around 500, you are essentially a gamble in the eyes of a bank. They see a high-risk profile, so they demand a higher premium to cover their potential losses.
This premium manifests as a higher Annual Percentage Rate, or APR. It is a common mistake to look only at the interest rate and think you have the full story. In reality, the APR is the true north for your finances because it bundles the base rate with those pesky origination fees and lender costs.
Think of the APR as the “all-in” price of your debt. If you only focus on the interest rate, you might find yourself blindsided by extra charges when the final bill arrives. Being savvy means looking at the total cost of borrowing before you commit your hard-earned cash to a new loan.
Take a look at how these different borrowing scenarios play out for someone sitting at a 500 credit score:
| Principal Borrowed | APR (Annual Rate) | Repayment Period | Monthly Installment | Cumulative Interest | |
|---|---|---|---|---|---|
| – | $3,000 | 15% (Good Credit) | 24 Months | $145.46 | $491.04 |
| – | $3,000 | 30% (Fair Credit) | 24 Months | $171.18 | $1,108.32 |
| – | $3,000 | 45% (Poor Credit) | 24 Months | $199.63 | $1,791.12 |
The numbers tell a staggering story. When the interest rate simply doubles, the total amount you pay in interest can end up more than tripling the original cost. It is a steep mountain to climb, and the weight of that interest can feel like an anchor around your ankles if you aren’t careful.
This is why your choice of lender matters more than almost anything else. You shouldn’t just be looking for someone to hand you cash; you need a partner. Look for a lender that offers a path to repairing your credit score rather than one that just treats you like a walking ATM.
Ultimately, your goal should be long-term stability, not just immediate relief. Choosing a lender that prioritizes your financial health over predatory interest rates is the single most vital decision you will make during this journey.
Top Borrowing Alternatives Evaluated
Navigating the sea of lending options can feel like trying to find a needle in a haystack when your score is hovering around the 500 mark. It is easy to feel overwhelmed by the sheer volume of companies promising quick cash under the table. However, not every lender is cut from the same cloth when it comes to risk tolerance.
I remember a friend of mine who was stuck in a financial pinch, staring at a daunting pile of bills. He thought his credit history had essentially closed all the doors in his face. It turns out, some providers actually specialize in helping people in his exact predicament. You just have to know where to look.
Finding the right fit is about more than just looking at the interest rate. You have to weigh how fast they can get money into your pocket and what they demand from your credit report. Some companies are lightning-fast, while others take a bit more time to process your application and verify your details.
Before you sign any paperwork, take a moment to look at the landscape. This quick breakdown compares how several major players stack up against one another. It should give you a bird’s-eye view of what to expect regarding amounts, timeframes, and their specific attitudes toward your credit profile.
| Company | Available Funds | Repayment Period | Processing Time | Qualification Criteria |
|---|---|---|---|---|
| Avant | Consult website | Consult website | Consult website | Suited for low credit scores |
| OneMain Financial | $1,500 – $30,000 | 24 – 60 months | Within 1 hour | Consult website |
| FastLendGo | Consult website | Consult website | Consult website | Poor or no credit history |
| Reprise | Consult website | Consult website | Consult website | Consult website |
| United Finance | Max $20,000 | Consult website | Consult website | Consult website |
| OppLoans | Consult website | Consult website | Funds arrive same-day | No impact on FICO score |
Leading Lending Options Evaluated
1. Avant
Avant acts like a financial co-pilot, helping people steer toward better economic health. They provide a tailored suite of options, ranging from credit cards to installment loans, that adapt to where you are in life. Their mission focuses on handing you the right implements to tackle debt or survive an unexpected rainy day.
You won’t find a predatory “payday” trap here; instead, Avant wants to walk beside you for the long haul. They are a fantastic pick if your needs go beyond a simple cash injection. Because they offer tools for debt consolidation, they function as a versatile ally for anyone looking to tidy up their messy financial life.
If your high-interest credit card bills are starting to feel like a heavy weight, an installment loan from Avant might be the life raft you need. By merging those various payments into one single, manageable monthly installment, you could find some breathing room, provided the interest rate works in your favor.
Pros:- Provides various financial instruments like debt consolidation and credit cards.
- Focused on helping clients reach their long-term financial milestones.
- Offers flexible solutions suited for different stages of life.
- Exact terms and interest rates aren’t clearly stated for every credit bracket.
2. OneMain Financial
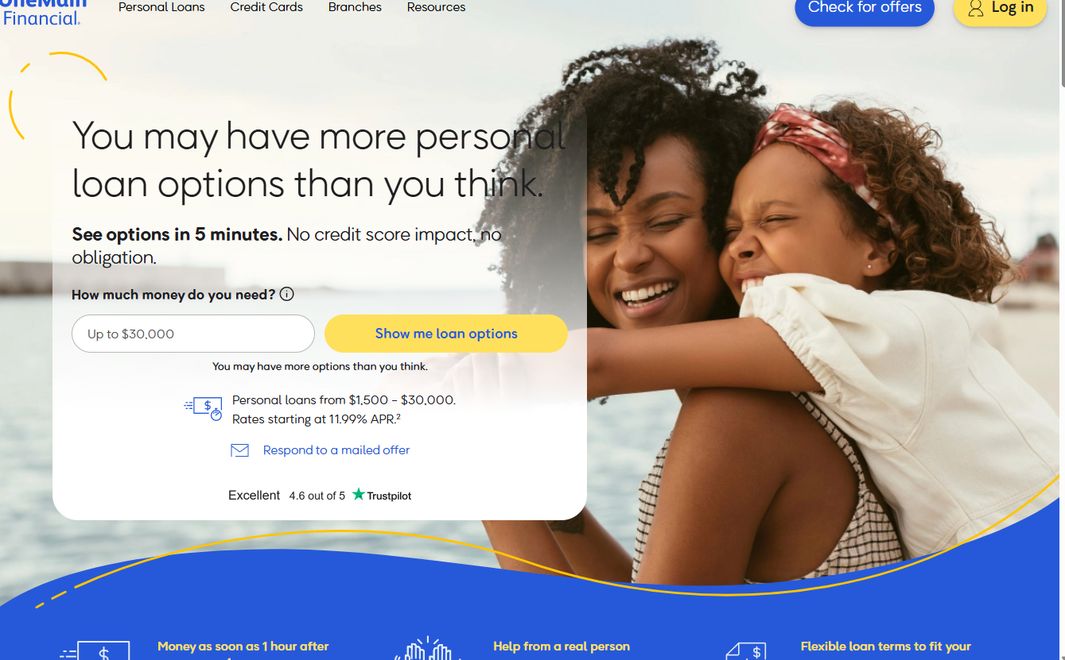
Sometimes, you just need to look a human being in the eye. OneMain Financial fills that void with a massive network of over 1,300 physical branches. This face-to-face access is a goldmine for borrowers with non-standard income, like freelancers or the self-employed, whose stories might get lost in a cold computer algorithm.
Walking into a branch allows you to sit down with a professional and lay out your unique circumstances. This personal connection can often unlock better loan terms than a purely digital application. They offer a wide range of personal loans, from $1,500 all the way up to $30,000, making them a sturdy choice for big projects like fixing a roof or consolidating debt.
If you are in a time crunch, you won’t be left hanging for long. Once the paperwork is signed and verification is complete in person, you could potentially see your funds within a single hour.
Pros:- Extensive network of physical locations for face-to-face assistance.
- Rapid fund disbursement, potentially just one hour after signing.
- Substantial loan limits reaching up to $30,000.
- Some loan options require a branch visit or a response to a mailed offer.
3. FastLendGo
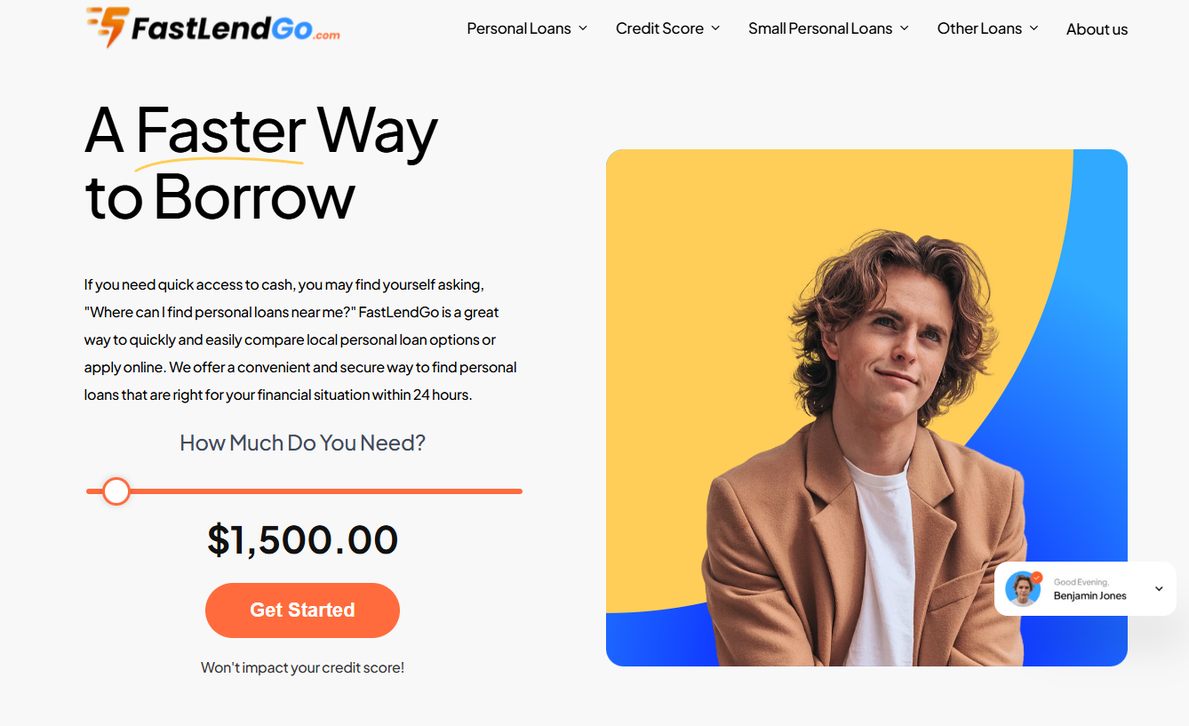
Think of FastLendGo as a high-speed digital bridge connecting you to local lending opportunities. Rather than wasting your afternoon playing phone tag with various banks, FastLendGo pulls multiple offers into one clean, efficient dashboard. Whether you need a tiny $500 cushion for a sudden repair or a larger sum for a new roof or car, they have you covered.
The platform is built for the modern, fast-paced lifestyle, working beautifully on a smartphone for those on the move. They specifically target people facing financial hurdles, providing options for those with no credit history or even bad credit. It is the perfect “near me” solution for anyone wanting to bypass the long lines of a traditional bank.
By putting all the cards on the table through a comparison model, you take back control. You get to see exactly which lender is offering the most competitive rate for your specific credit profile, giving you the full picture at a single glance.
Pros:- Supports many loan uses, including dental and automotive needs.
- Accommodates various credit levels, including those with no credit history.
- Provides an efficient way to compare local lenders.
- Works as a comparison engine, so actual terms depend on the matched lender.
4. Reprise
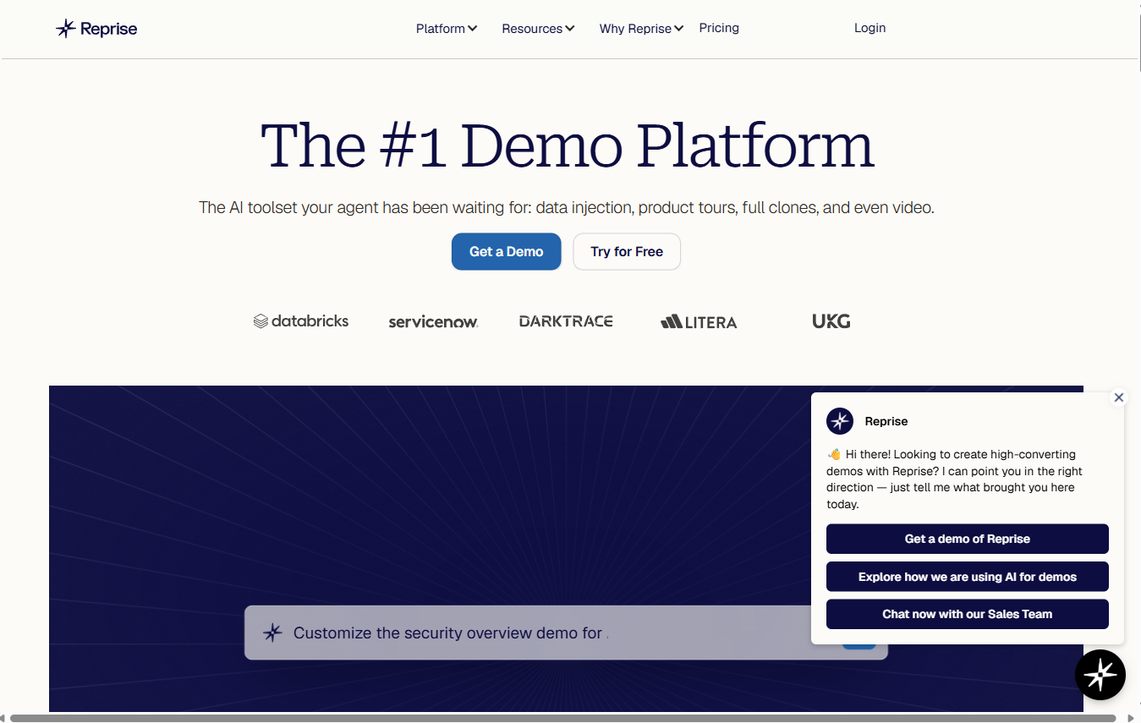
Reprise plays in a different league by utilizing cutting-edge AI to handle data and demonstrations. While they primarily exist to provide a platform for enterprise-level demos, they represent the fascinating point where high-tech data meets professional services. In a world where everything is being automated, they showcase how deep data management has evolved.
For professionals who live and breathe technology, they offer sophisticated features like full clones and data injection. They aren’t really a traditional lender for your personal debt; instead, they are a specialized tool for managing business presentations at a high level. They serve as a unique reminder of the diverse tech landscape currently shaping the fintech world.
Pros:- Utilizes advanced AI technology for creating demos.
- Offers high-level capabilities for injecting data.
- Provides an efficient way to manage professional presentations.
- Not a standard personal loan provider for consumer debt.
5. United Finance
United Finance is a true veteran of the industry, having kept its doors open since 1922. They specialize in making personal and auto loans straightforward and easy to understand. Their long history is a testament to the stability they provide to their clients—a refreshing change of pace compared to the “flashy” fintech startups that often vanish overnight.
This decades-long track record suggests they truly understand how to manage risk and navigate the lending cycle. They offer personal loans that can go up to $20,000. Additionally, Oregon residents can take advantage of their high-yield certificates. This mix of lending and investment products makes them a very reliable choice for those seeking a traditional institution.
Pros:- Boasts an incredibly long history of stability.
- Provides both auto and personal loan options.
- Features investment products like high-yield certificates.
- Certain products, like investment certificates, may have geographic restrictions.
6. OppLoans
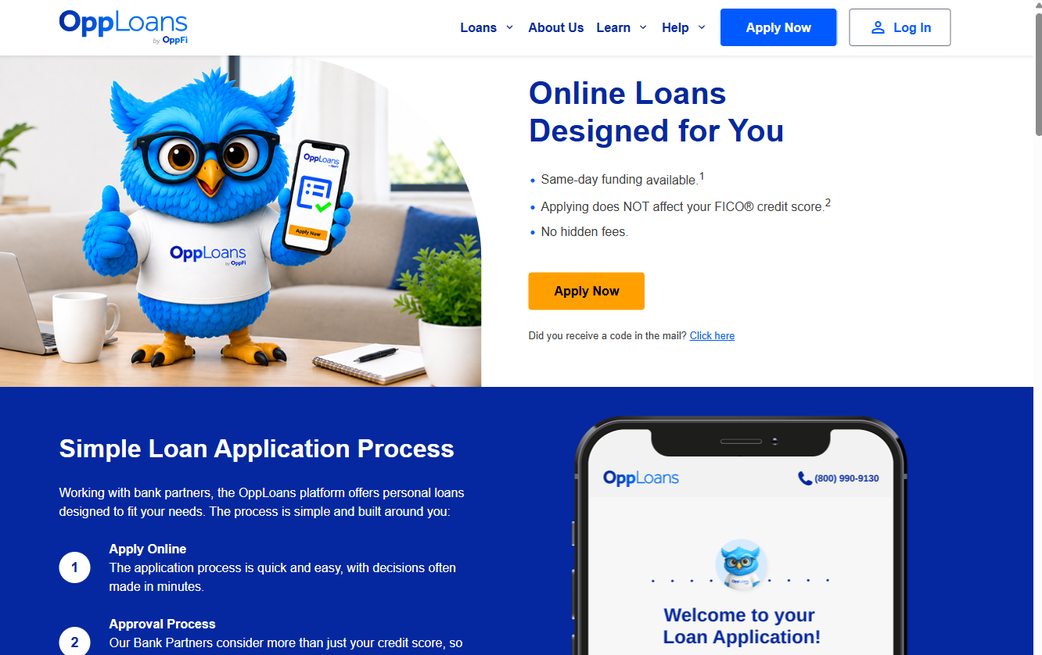
If speed is your main priority, OppLoans is built for the moment. Perhaps their greatest advantage is that applying won’t touch your FICO score. This is a massive win for anyone trying to nurse a 500 credit score back to health, because when you are rebuilding, every single point is precious.
Since a “hard inquiry” can act like a weight on your score, being able to check your eligibility without penalty is a game-changer. They partner with banks to deliver rapid decisions, often within just a few minutes. If you are facing a crisis, they can even offer same-day funding to get you through the storm.
This is the ideal choice for urgent emergencies where waiting even one day might mean a late fee or a utility shut-off. It is a tool designed for when you need a solution right this second.
Pros:- Checking eligibility does not impact your FICO score.
- Same-day funding is available for those who are approved.
- Features a very rapid decision-making process.
- Best suited for urgent, short-term needs rather than long-term wealth building.
Hunting for the Right Financing
If you find yourself staring down a 500 credit score, you might feel like you’re running a race with weights tied to your ankles. The urge to jump at the very first hand extended to you is incredibly strong. Yet, the path of least resistance rarely leads to the most favorable destination for your wallet.
You must dive deep into the murky details regarding how much this capital actually costs you. A quick loan might seem like a lifesaver in a pinch, but it can quickly turn into a millstone around your neck if the interest rates are predatory. Don’t let a momentary solution create a long-term financial headache.
Watch out for those sneaky “origination fees” that lenders often hide in the shadows. These are essentially upfront charges sliced directly from your borrowed funds. Imagine you secure a $1,000 loan, but the lender deducts a $100 fee immediately. You walk away with just $900 in hand, yet your debt remains $1,000. It is a bitter pill to swallow.
Many borrowers stumble by failing to distinguish between a soft inquiry and a hard credit pull. I always suggest hunting for lenders that permit you to verify your eligibility through a soft pull first. This method lets you window-shop for better rates without bruising your credit score further. It is a smart way to play the field.
Treat this comparison phase as a tactical mission to gather diverse quotes. By weighing various APRs against one another, you ensure you aren’t paying a premium just for the luxury of having cash today. It is better to spend a little time now than to lose hundreds later to high interest.
Another trap involves getting caught up in a long repayment timeline. While a 60-month term might make your monthly bills look manageable, the math tells a different story. You could end up paying back almost twice what you initially took out because of the extended interest accumulation. It is a costly way to live.
Try to find a sweet spot where the monthly installment fits your budget without suffocating your lifestyle. You want to leave some breathing room in your bank account so you can build an emergency fund. This extra cushion helps you climb out of a low score rather than staying stuck in a debt cycle.
Ultimately, look at this loan as a temporary bridge to get you from point A to point B. It should be a tool for progress, not a permanent anchor that keeps you tethered to your past financial mistakes.
