
Best Places to Secure a 520 Credit Score Personal Loan Right Now
Last updated: 2026-10-16
Trying to navigate your finances with a 520 credit score is akin to trekking uphill through a swamp. When your rating slides into the 500s, traditional banks tend to pull up the drawbridge. It becomes a relentless loop of seeking assistance, only to collect a mountain of rejection notices.
This specific rating often stems from a cocktail of heavy credit usage, late payments, or perhaps a recent bankruptcy. Dealing with collections can also drag your standing down. Beyond the math, the mental fatigue of constant denial is a heavy weight to carry.
We have curated this list to highlight lenders that peek past that one difficult digit. If your score is low, you require transparency and rapid response times. You cannot afford to wait weeks for a manual review when an urgent medical debt or a broken furnace demands immediate payment.
Our team cut through the clutter to find genuine options for people facing immediate hardship. We specifically sought out firms that weigh alternative metrics. By looking at your bank activity or steady income, they build a more complete picture of your ability to repay.
- Max Cash
- Avant
- JetzLoan
- Acorn Finance
- NetCredit
- Upgrade
Our Methodology for Rating Lenders
Finding a way out of a financial hole when your credit rating sits at 520 is like walking a tightrope in a storm. It is incredibly difficult. Because of this, our team placed a premium on finding lenders who actually welcome people facing major credit hurdles.
We didn’t care about perfection; we cared about possibility. Our main goal was to pinpoint companies that grant approvals even when a flawless payment history is out of reach. Speed was another deal-breaker for us. We sought out streamlined, user-friendly digital portals.
Specifically, we hunted for web-based services capable of finishing your paperwork in less than ten minutes. It wasn’t just about the raw numbers, though. We examined the breadth of their inventory to ensure they had something for everyone.
Whether you are hunting for a small lifeline to pay a sudden electric bill or a substantial pile of cash for renovations, diversity matters. We wanted to ensure these providers didn’t just offer one size fits all solutions.
We also took a hard look at “soft pull” options. You should never have to risk your fragile score by “shotgunning” applications across the internet. That frantic habit of blasting out dozens of requests can bury a consumer in even more damage.
Transparency is the name of the game when things get dicey. For those navigating a 520 score, hidden costs or penalties for paying early can feel like a trap. We prioritized lenders who lay their APRs bare before you ever sign on the dotted line.
| Provider | Funding Range | Processing Time | Score Impact for Quotes |
|---|---|---|---|
| Max Cash | $250 – $10,000+ | Minutes | No Obligation |
| Avant | See site | See site | See site |
| JetzLoan | $500 – $35,000 | As little as 24 hours | No impact |
| Acorn Finance | See site | See site | No impact |
| NetCredit | Up to $10,000 | Same-day available | No impact |
| Upgrade | Up to $50,000 | Fast funding | Won’t impact score |
Top-Tier Lending Options for Subprime Borrowers
1. Max Cash
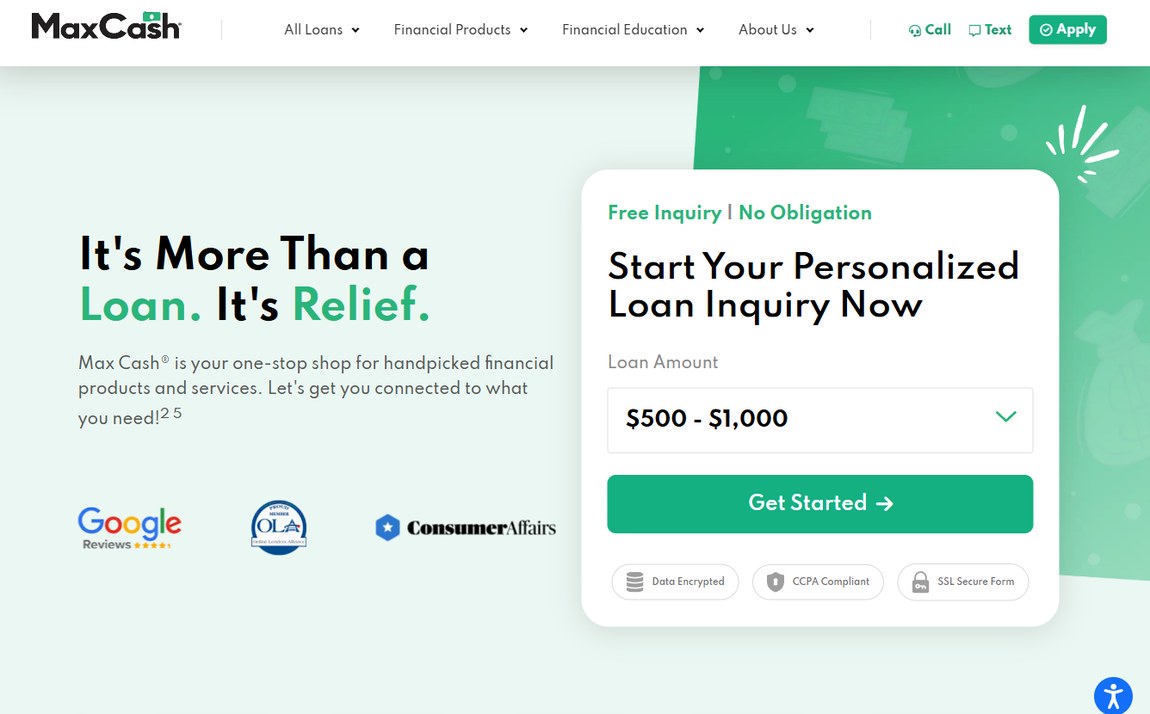
When mainstream banks shut their doors, Max Cash serves as a vital lifeline. Their product catalog is quite diverse, spanning from tiny micro-loans to much larger installment-based financing. They understand that time is of the essence when you are facing a sudden cash crunch.
This makes them a perfect fit for those navigating “bridge financing” scenarios. If you are simply waiting for a paycheck or a tax refund to hit your account, they can bridge that gap. It is a reliable lifeline for anyone needing quick liquidity to tackle an emergency.
The flexibility here is impressive, with borrowing limits starting at a modest $250 and scaling up past the $10,000 mark. Because they cater to various scales of necessity, they are a versatile ally. Small loans are particularly handy for minor expenses that don’t require a long-term debt commitment.
Advantages:
- Flexible amounts ranging from $250 to over $10,000.
- Lightning-fast processing that takes only minutes.
- Initial quotes are provided without any obligation.
Disadvantages:
- The emphasis on extreme speed may result in higher interest rates.
2. Avant
Avant operates on the belief that a person is much more than a solitary digits on a report. Their mission is to facilitate upward financial mobility through various tools designed to manage debt or cover unexpected household costs. They offer a structured path for those seeking stability.
They don’t just obsess over FICO numbers; instead, their underwriting process might weigh your employment history or your banking relationships. Whether your goal is a new credit card or funding a home renovation, they provide tailored options for your life.
If you are slowly climbing out of the credit basement, Avant is a fantastic companion. As your score inches from 520 toward the 600 mark, they act as a long-term partner in your progress rather than a mere temporary band-aid for your problems.
Advantages:
- Wide variety of options, from credit cards to debt consolidation.
- Built specifically to help users progress financially.
- Versatile solutions that adapt to different life stages.
Disadvantages:
- Minimum credit thresholds might disqualify those with the lowest scores.
3. JetzLoan
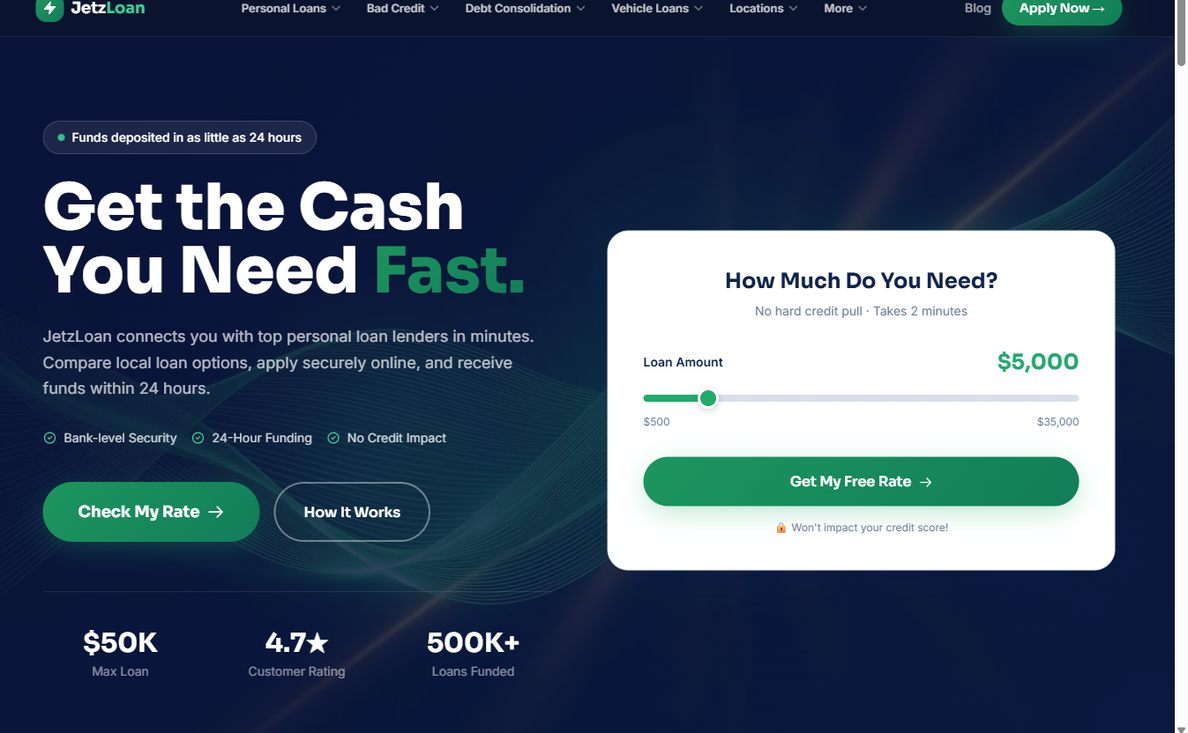
If the slow pace of traditional banking drives you crazy, JetzLoan is a breath of fresh air. They act as a high-speed connector, linking you to premium lenders in just a few minutes. It is an incredibly efficient way for modern, busy individuals to shop around.
You won’t have to spend your afternoon filling out a mountain of different applications. Their marketplace model handles the heavy lifting for you. With a reputation for high customer satisfaction and over 500,000 loans funded, they are built for high-speed results.
The ability to hunt for rates without a hard credit inquiry is a massive safety net. When your score is sitting at 520, a single unnecessary inquiry could drag you into the 400s. JetzLoan protects your credit health while you search.
Advantages:
- Potential to receive your funds in as little as 24 hours.
- Rate comparisons that don’t require a hard credit pull.
- Consistently high ratings from satisfied customers.
Disadvantages:
- How quickly you get paid depends on the specific lender you find.
4. Acorn Finance
Acorn Finance is a niche powerhouse, specifically engineered for those tackling home improvement projects. They operate as a marketplace that matches you with various lenders. This is a godsend if you are trying to upgrade your kitchen or fix up a backyard deck.
Many homeowners view their property as their primary wealth builder. Using a loan to increase home value is a smart way to build equity even when your credit is currently in the red. They even allow contractors to offer financing without charging any dealer fees.
This makes them a standout for large-scale, project-specific funding. You can shop around for personalized rates without touching your credit score. For example, if a new roof is required, you can compare different specialists through Acorn to find the best APR for your profile.
Advantages:
- Focused expertise in financing for home improvement contractors.
- Checking rates will not impact your credit score.
- Certain contractor options feature zero dealer fees.
Disadvantages:
- The narrow focus means they might not fit general cash needs.
5. NetCredit
With the slogan “Credit to the People,” NetCredit operates under the philosophy that you are more than a data point. This mindset leads them to use sophisticated algorithms that look at your holistic financial health rather than just a single FICO number.
By analyzing your banking patterns, they can assess your ability to repay, which is a total game-changer for people with thin credit histories. They offer everything from personal loans to lines of credit, with the possibility of seeing funds the same day you apply.
This is perfect for emergencies, like a sudden car breakdown that threatens your ability to get to work. They strive to be a transparent, empathetic alternative to the big banks, providing a reliable experience for those who are often overlooked.
Advantages:
- The option to receive funding on the same day.
- Advanced technology looks beyond just your credit score.
- Checking your eligibility is completely free and won’t hurt your FICO.
Disadvantages:
- Total loan amounts are limited to a maximum of $10,000.
6. Upgrade
Upgrade is a major player in the personal loan industry, serving a massive variety of borrowers. They provide substantial funding, reaching up to $50,000, which is ideal for life-altering events or consolidating expensive debt. If high-interest credit cards are sinking your score, this is your exit ramp.
Consolidating those various high-interest balances into one single, lower-interest installment loan can act as a catalyst for credit recovery. Their digital platform is built for the modern age, allowing you to see your potential rates in mere minutes.
They also include extra perks, such as cash back on select purchases, helping you rebuild your financial footing while you manage your money. By providing both a loan and cash-flow tools, they act as a holistic financial partner for your journey.
Advantages:
- Generous loan limits that go up to $50,000.
- Rapid rate checks and quick funding cycles.
- Bonus features like cash-back on specific checking accounts.
Disadvantages:
- The variety of products might be too much for someone seeking only a basic loan.
Financial Implications of Subprime Loans
If your credit profile sits around 520, you need to brace yourself for a bit of a sting. Borrowing money isn’t a walk in the park when your score is low; it’s going to cost significantly more than it would for a person boasting a 750 rating. Lenders view your score through a lens of uncertainty, attaching higher interest rates as a safety net to cover potential defaults.
Think of these extra percentages as a “risk premium” that banks demand to offset the gamble they are taking on you. Before signing any paperwork, you must grasp the fundamental distinction between how interest is tallied. Understanding the mechanics of your debt is the only way to avoid being blindsided by rising balances later on.
Simple interest is quite straightforward, as it only applies to the original sum you borrowed. On the flip side, compound interest is a different beast entirely. It calculates charges based on your principal plus any unpaid interest, which can cause your debt to snowball out of control if you stick only to minimum monthly payments.
You should always hunt down the “Total Cost of Loan” metric during your search. A salesperson might tempt you with a $150 monthly installment, which feels like a breeze for your budget. However, if that term stretches out to 60 months, that $5,000 loan could ultimately cost you $9,000 in total repayments.
That gap represents a $4,000 fee just for the access to capital. It is worth asking yourself: “How much total interest will I pay over the life of this loan?” Taking the time to ask this one specific question can save you thousands of dollars and stop years of grueling financial struggle before they even begin.
Pathways to Credit Improvement Post-Loan
View obtaining a loan with a 520 score as a strategic stepping stone rather than a mere quick fix for immediate expenses. Think of it as a reset button for your financial health. If you utilize this capital to combine various debts, use that newfound space to clear those old balances entirely.
The real danger lies in the temptation to keep spending. If you wipe out a credit card using your loan but then quickly max out that card again, you’ve effectively doubled your liabilities. This mistake is a recipe for disaster that could cause your score to plummet even further than it is now.
To squeeze every bit of value out of your loan and watch those numbers climb, stick to these essential habits:
- Set and forget your payments: A single slip-up on a deadline can slash your score by 50-100 points. To prevent this, schedule autopay for at least the minimum monthly amount to keep your record spotless.
- Watch your credit usage: If your loan was meant to settle card balances, ensure your card usage stays below the 30% threshold. Managing this ratio is often the fastest way to see a significant jump in your rating.
- Hold off on new credit: Once things stabilize, resist the urge to shop for new credit lines for the next 6-12 months. Your score needs a window of time to recognize and reward your consistent repayment habits.
Mastering the Application Journey
Navigating the financial landscape with a 520 score is like walking a tightrope during a storm. Every single step requires precision and careful thought. A common blunder that many people make is firing off numerous applications simultaneously to different lenders.
Every time a lender performs a “hard pull” on your file, your credit rating takes a direct hit. This can make your already shaky foundation even more unstable. It is better to hunt for lenders that offer “soft pull” rate checks first.
Checking rates this way is like window shopping in a luxury mall. You can compare prices and terms without any cost to your reputation. This method lets you find the most favorable terms without the sting of multiple credit inquiries.
Don’t let the siren song of a quick cash injection lead you into a trap. While a fast loan might patch a hole in your finances today, the long-term consequences can be heavy. You must scrutinize the fine print of your agreement.
If the interest rates are sky-high, you might find yourself staring at a mountain of debt rather than a solution. It is a slippery slope that many borrowers fall down. Always calculate the total cost of borrowing over the full life of the loan.
Looking only at the monthly installment is like looking at the tip of an iceberg. It hides the massive debt lurking beneath the surface. Ensure your choice actually paves a path toward better credit rather than digging a deeper hole.
Keep a sharp eye out for clauses regarding “prepayment penalties” tucked away in the contract. Some companies will actually charge you a fee if you try to settle your debt ahead of schedule. It sounds counterintuitive, but it is a real trap.
If a sudden windfall allows you to clear your balance early, you want to celebrate that victory. You shouldn’t be punished for being fiscally responsible or efficient with your money. Seek out lenders that cheer on your progress instead of taxing it.
