
Quickly Secure Bad Credit Loans California: Best Fast Approval Lenders
Last updated: 2026-10-16
Navigating your finances in California can often feel like trying to steer through a heavy mist, especially if your credit score isn’t quite where it needs to be. It is a common struggle for many residents who find themselves scrambling to pay for unexpected vehicle maintenance, doctor’s bills, or other pressing living expenses. Too often, traditional big-name banks offer an immediate “no” when you are most vulnerable. This leaves many people searching for alternative paths to bridge the gap between their current income and sudden, mounting costs. Whether it is a sudden transmission failure while driving through Los Angeles or an unexpected medical deductible in San Diego, financial emergencies rarely wait for a convenient time. They strike like lightning, leaving you grasping for immediate liquidity to keep your life moving forward. Finding a suitable lender requires more than just glancing at shiny advertisements. You must dive deep into the fine print, scrutinizing interest rates and the actual speed of fund disbursement to ensure you aren’t being misled by flashy promises. It is incredibly easy to fall for a “low monthly payment” sales pitch that sounds like a lifeline. However, your true total cost of borrowing is dictated by the length of your term and the Annual Percentage Rate (APR). Don’t let the marketing jargon cloud your judgment. Understanding how these factors interact is the only way to avoid a mountain of debt that feels impossible to climb later on. This selection outlines the premier choices for Californians seeking flexibility. These lenders offer a realistic possibility of approval, even for those navigating a rather bumpy financial journey.
- OneMain Financial
- Avant
- FastLoans CA
- Upgrade
- VivaLoan
- GreendayOnline
- United Finance
Scrutinizing California Lending Options for Low Credit Scores
Finding a trustworthy lender is like searching for a needle in a haystack when your credit history is less than stellar. We decided to weigh several critical metrics to see who actually stands up to scrutiny. Our investigation prioritized how accessible these services are for those with suboptimal ratings. We also looked at how quickly cash lands in your pocket.
Transparency is the name of the game when you are navigating financial waters. You should never be left in the dark regarding whether a company will perform a hard credit pull during your initial inquiry. Knowing this detail upfront can be the difference between a smooth experience and a sudden shock to your financial standing.
A soft pull is your best friend because it allows you to gauge your potential rates and eligibility without any penalty to your score. It’s a harmless glance at your data. Conversely, a hard pull occurs when an institution conducts an intensive investigation of your credit profile for a formal loan request. This specific action can lead to a momentary drop in your numerical rating.
Understanding this nuance is vital to protect your credit score from needless erosion. We also dug deep into the math behind the money. A massive loan limit sounds enticing, but it can be a wolf in sheep’s clothing if the interest rates are predatory. It can turn a simple loan into a mountain of debt that is impossible to climb.
Consider how the numbers play out over time. For example, a $5,000 loan carrying a 36% APR over a 36-month span will cost you significantly more in interest than a $5,000 loan with a 15% APR over that same duration. We have ranked these providers based on their commitment to fair structures and straightforward, honest processes.
| Financial Institution | Borrowing Limits | Speed of Funding | Credit Standards | Primary Advantage |
|---|---|---|---|---|
| OneMain Financial | $1,500 – $30,000 | Within 1 hour | Refer to website | Local branch access |
| Avant | Refer to website | Refer to website | Refer to website | Versatile options |
| FastLoans CA | $1,000 – $35,000 | Within 24 hours | No hard credit pull | California authorized |
| Upgrade | Up to $50,000 | Refer to website | Refer to website | Debit card cash back |
| VivaLoan | $100 – $15,000 | By the next day | All credit types welcome | Small minimums |
| GreendayOnline | $100 – $5,000 | Within the same day | No credit check | Rapid emergency funds |
| United Finance | Up to $20,000 | Refer to website | Refer to website | Operational since 1922 |
Distinguishing Between Collateralized and Non-Collateralized Borrowing
Navigating the lending landscape in California often feels like walking a tightrope. You will inevitably encounter two primary categories of debt: secured and unsecured options. Grasping the nuances between these two paths is essential for your lasting fiscal stability and how you handle potential pitfalls.
Think of it as choosing between a minor inconvenience and a total catastrophe. One path leaves your belongings safe, while the other puts them on the line. Understanding this distinction is the first step toward making a smart move with your money.
When you opt for an unsecured loan, such as the personal loans offered by Upgrade or Avant, you aren’t required to provide collateral. You won’t find yourself handing over your home deed or your car’s title just to secure the funds. It is a straightforward transaction without the heavy baggage of physical assets.
However, there is no such thing as a free lunch in the banking world. Since these lenders face a higher risk of non-payment without an asset to grab, they typically charge steeper interest rates. For many residents across the Golden State, the ability to protect their property makes these higher costs worth the peace of mind.
On the other hand, a secured loan demands that you pledge something valuable, such as a savings account or a vehicle, as security. This asset acts as a safety net for the lender. If you find yourself unable to meet your monthly obligations, the creditor possesses the legal authority to take that property to recover their funds.
It is a classic trade-off of risk versus reward. While these types of loans frequently boast more favorable interest rates, losing your primary mode of transportation could derail your entire life. Before signing any paperwork, carefully balance the benefit of a lower rate against the terrifying possibility of losing your hard-earned possessions.
Leading Lending Options for California Residents
1. OneMain Financial
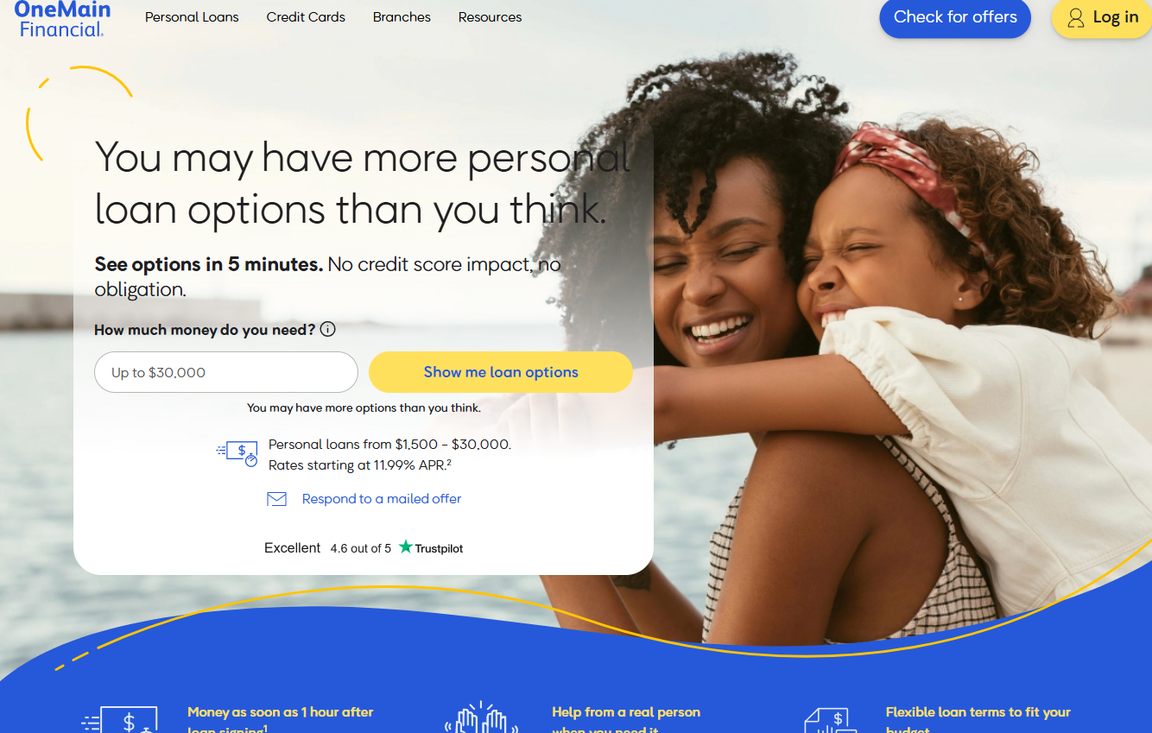
If you’re the type of person who prefers a handshake over a digital signature, OneMain Financial might be your best bet. They bridge the gap between modern technology and old-fashioned service through a massive network of over 1,300 local branches. It’s a comforting feeling to walk into an office rather than clicking through a screen when your finances are on the line.
For residents in Fresno or Sacramento, having a physical location nearby can make all the difference in the world. Sitting down with a professional helps clear up the fine print and builds a foundation of trust that many purely online companies just can’t match. You can secure personal loans ranging from $1,500 all the way up to $30,000 to tackle those heavy financial burdens.
Budgeting becomes much less of a headache with their fixed monthly installments. With terms that stretch from 24 to 60 months, your costs won’t fluctuate even if the economy throws a curveball. Starting at 11.99% APR, these loans offer a structured path to getting your finances back on track without any nasty surprises later on.
Pros:
- Wide-reaching physical network for face-to-face assistance.
- Rapid disbursement, potentially within an hour of signing.
- Predictable monthly payments for easier financial planning.
Cons:
- Involves more hands-on interaction than most digital-only lenders.
2. Avant
Think of Avant less as a lender and more as a financial companion. Rather than just handing over cash, they provide a toolkit designed to help you make progress. Whether you need a fresh credit card or a loan to consolidate what you already owe, they focus on your long-term trajectory.
This makes them a stellar choice if you’re tired of chasing multiple high-interest monthly payments. They realize that life isn’t one-size-fits-all, so they offer a variety of paths, from tackling debt to funding home improvements or handling sudden emergencies.
Their digital-first platform is a dream for the busy person on the move. You can manage your entire financial life while grabbing a coffee or riding the train. It’s a seamless way to find the specific tools you need to steady your ship and move forward.
Pros:
- Prioritizes your ongoing financial growth.
- Provides a diverse range of products like loans and credit cards.
- Boasts a very intuitive digital experience.
Cons:
- Upfront details on specific rates and terms can be a bit elusive.
3. FastLoans CA
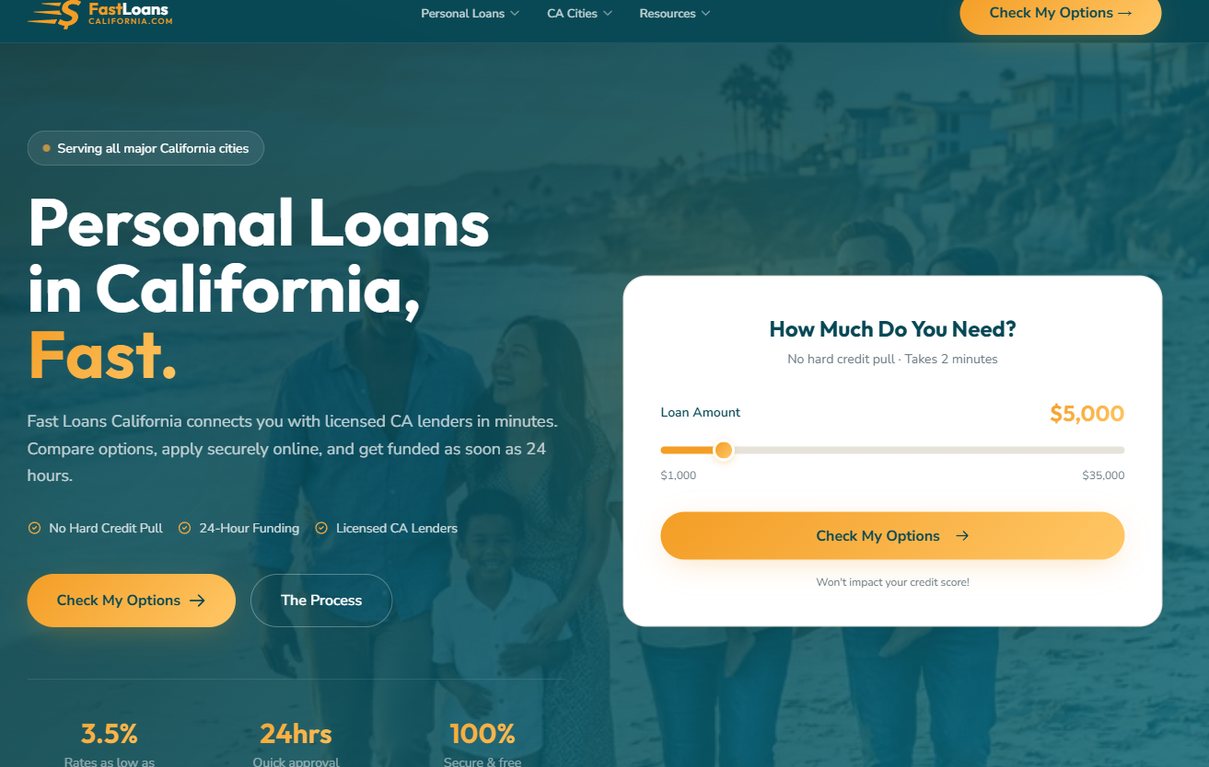
When you’re facing a sudden crisis, FastLoans CA acts as a bridge to licensed lenders throughout the Golden State. They understand that time is of the essence, often aiming to get funds into your hands within 24 hours. You can check your eligibility in just a few minutes.
Imagine your pipes burst or a medical bill arrives out of nowhere; that’s where this speed becomes a lifesaver. Best of all, checking your options won’t ding your credit score because they don’t use hard credit pulls for the initial inquiry. You can shop around with peace of mind.
With loan caps reaching $35,000, they cover everything from a quick fix to a major household overhaul. Because they focus specifically on California, they are well-acquainted with local laws, offering an extra layer of security for the people they serve.
Pros:
- Inquiry process does not impact your credit score.
- Extremely quick approval and funding turnaround.
- Dedicated service for a huge number of California families.
Cons:
- Interest rates may be notably higher than standard bank loans.
4. Upgrade
A powerhouse in the lending world, Upgrade has helped over 8 million people navigate their finances. With loan amounts hitting up to $50,000, they are a heavy hitter for those tackling major life transitions or massive debt consolidation projects. If you’re looking to roll several high-interest cards into one, their high limits are a massive plus.
They do more than just lend money; they offer a complete ecosystem, including checking accounts that can pay you back with 2% cash on your purchases. This creates a unique opportunity to blend your borrowing needs with your everyday banking habits seamlessly.
By keeping your banking and your loan under one roof, you can see your whole financial picture in a single dashboard. This is a huge time-saver for anyone who finds managing five different apps to be a total headache.
Pros:
- Substantial loan limits reaching $50,000.
- Offers rewarding checking accounts alongside loans.
- Allows for quick rate checks without affecting your credit.
Cons:
- The most competitive rates are usually reserved for those with better credit.
5. VivaLoan
Sometimes, you don’t need a mountain of cash; you just need a small helping hand. VivaLoan excels at providing smaller, bite-sized loans starting at just $100. It’s the perfect solution for a quick fix, like replacing a blown tire, without the weight of a massive debt hanging over you.
Speed is their middle name. The application process takes roughly five minutes, and if you’re approved, the money is usually in your account by the next business day. It’s a reliable lifeline for when you need cash almost instantly.
The beauty of their system lies in its simplicity. By cutting through the red tape that usually defines traditional banks, they make it incredibly easy for people to solve a sudden problem and move on with their lives.
Pros:
- Very accessible minimums starting at only $100.
- Funds are often delivered by the very next business day.
- The application is incredibly straightforward and fast.
Cons:
- Loan ceilings are somewhat limited at $15,000.
6. GreendayOnline
When a financial emergency is staring you in the face, GreendayOnline provides specialized installment loans designed for urgent situations. They specifically cater to those with less-than-perfect credit by skipping the hard credit checks. For many, this is a vital lifeline when traditional banks have closed their doors.
This is often the final option for those dealing with significant credit damage or active bankruptcy. With amounts from $100 to $5,000, they provide the quick liquidity needed for immediate crises. Their web form is streamlined to ensure you get a decision quickly.
While these are high-speed options, they function as installment loans. This means instead of a single massive payment, you can spread the repayment out over time, which is much more manageable than a typical payday loan structure.
Pros:
- Approvals don’t require hard credit checks.
- Potential for same-day cash when you need it most.
- Simple and incredibly easy-to-use online platform.
Cons:
- Interest rates on these installment loans can be quite steep.
7. United Finance
United Finance offers a sense of enduring stability, having been around since 1922. In an era of fly-by-night digital lenders, their century of experience offers a comforting sense of permanence. There is a unique peace of mind that comes with knowing a company has weathered every economic storm for decades.
They provide a range of products, including personal loans up to $20,000 and various auto loan options. Their philosophy is built on simplicity and accessibility, making them a great choice for anyone seeking a traditional, reliable lending experience.
Having survived everything from the Great Depression to the digital revolution, their longevity speaks volumes. This history can be incredibly reassuring for cautious borrowers who are wary of unproven online startups that might vanish overnight.
Pros:
- A long, established history in the finance industry.
- Offers both auto and personal loan varieties.
- Provides a personal touch in their lending approach.
Cons:
- Lacks some of the high-tech, instant-only digital features.
How to Boost Your Approval Odds
Even when your credit score isn’t exactly shining, you can still tilt the scales in your favor. It is a common misconception that a low FICO score is a total dead end. Most lenders actually peek at your capacity to settle your debts rather than just looking at a single number.
Walking into an application unprepared is like sailing into a storm without a compass. By doing your homework beforehand, you can avoid a trail of rejected requests. Every time a lender pulls your report, it leaves a tiny mark on your record, so being selective is key.
Before you even sit down to click “submit,” make sure you have your paperwork organized in a neat pile. You will generally need to provide:
- A legitimate ID issued by the government, such as a passport or driver’s license.
- Evidence that you live in California, like a lease or a recent utility statement.
- Documentation of your earnings, which might include bank statements or your two most recent pay stubs.
- Your Social Security number to confirm you are who you say you are.
Making sure your paychecks are easy to track is vital. For those navigating the gig economy or freelance life, the path can be a bit rockier. If you can show a steady stream of deposits or neatly filed tax documents, you might just turn a “no” into a “yes.”
Another crucial step involves checking your debt-to-income ratio (DTI). Think of this as a measure of how much of your paycheck is already spoken for by other lenders. If your monthly obligations eat up too much of your gross income, it’s a red flag for most banks.
It might be worth it to clear a small balance on a credit card before you start this process. Reducing that debt slightly can polish your financial profile. A better DTI makes you look much more stable when the lender begins their investigation into your finances.
Dodging Financial Traps
Before you ink your signature on any legal documents, you must grasp the full price tag of your debt. It is easy to get blinded by a small monthly installment that seems to fit your budget perfectly. However, a stretched-out repayment timeline can be a wolf in sheep’s clothing for your wallet.
Consider a scenario where you borrow $5,000. A $200 monthly bill feels like a breeze, but if that agreement spans 36 months, your total output hits $7,200. That extra $2,200 is the actual toll you pay for that credit. Never let a low monthly figure distract you from the bottom line.
Always demand the lender clarify the total repayment amount in a flat dollar figure rather than just the monthly chunk. If you only look at the monthly payment, you are essentially flying blind. It is like looking at the tip of an iceberg while ignoring the massive mass beneath the surface.
Don’t rush headlong into a deal without scrutinizing the fine print. Some companies bury administrative charges or hidden levies within the text. These sneaky costs can balloon your debt before you even have a chance to settle the balance.
Keep a sharp eye out for “prepayment penalties.” These are essentially fines that companies slap on you if you attempt to settle your debt ahead of schedule. It feels like being penalized for being financially responsible, which is a bitter pill to swallow.
You deserve the liberty to crush your debt early and bypass heavy interest charges without being slapped with extra fees. Take a moment to pause and weigh different APRs against one another. Make sure the debt’s architecture aligns with your real-world earnings and lifestyle.
Being diligent during the application phase acts as a shield for your future self. Taking an extra hour to read now prevents a massive headache from blooming down the road. It is better to be cautious than to find yourself trapped in a cycle of endless interest.
