
Quickly Secure Bad Credit Loans Maryland to Fix Your Finances Today
Last updated: 2026-10-17
Trying to manage your money in Maryland sometimes feels like stumbling through a dense mist in the dark. You might find a sudden mechanic’s bill or a surprise hospital invoice staring you down. These moments can trigger immediate stress for many families.
Perhaps your score took a hit because you were out of work for a while. Or maybe the skyrocketing prices in the Baltimore-Washington area simply squeezed your wallet too tight. Your credit history doesn’t always tell the whole story of who you are.
Hunting for a reliable lender is a task that requires more than a frantic thumb-swipe on a smartphone. You have to balance how fast you get the cash against what it will eventually cost you.
It is vital to distinguish between secured and unsecured debt options. You need to find companies that look at your current reality rather than just a three-digit rating. Whether you live in Montgomery County or the city of Baltimore, knowing these market shifts is key.
This compilation spotlights specific lenders tailored for residents of the Old Line State. We hope this serves as a useful compass for anyone trying to patch up a hole in their monthly budget.
- FastLendGo
- MaxCash
- LendingPoint
- OppLoans
- SECU
Our Selection Process for MD Borrowers
Finding the right lender in the Old Line State isn’t just a walk in the park. We spent countless hours dissecting the specific financial products available to Marylandans. Our goal was to ensure these options actually serve people facing real-world money struggles.
It isn’t enough to simply list names that appear in a Google search. We had to vet them for genuine utility, specifically for those struggling with low credit scores. We wanted to find a lifeline, not a sinking stone.
Many people fall into a hole of debt because they chase quick cash without reading the fine print. We steered clear of predatory lenders who hide nasty fees or sky-high interest rates in the shadows. We prioritized transparency above all else.
Our team scrutinized every potential candidate against a rigorous set of benchmarks:
- Funding Thresholds: We verified that lenders could handle anything from a tiny $300 emergency bill to a massive $15,000 debt restructuring loan.
- Deployment Velocity: When the rent is due tomorrow, every second counts. We checked if lenders offer instant approvals or if you’ll be waiting several days.
- Clarity of Terms: We ensured that the digital interface tells the truth. There should be no surprises when you finally put pen to paper.
- FICO Protection: We favored companies that use soft inquiries for initial quotes. You shouldn’t be penalized just for window shopping around.
| Company | Available Funds | Delivery Time | Qualification Criteria |
|---|---|---|---|
| FastLendGo | $500 – $5,000+ | Quickly available | Bad/Fair/Good Credit |
| MaxCash | $250 – $10,000+ | Minutes | Bad Credit Loans |
| LendingPoint | $1,000 – $36,500 | Rapid decision | See site |
| OppLoans | See site | Same-day funding available | Does not affect FICO score |
| SECU | $300 – $30,000 | See site | Unsecured Signature Loans |
Decoding Your Borrowing Options: Collateralized vs. Non-Collateralized Debt
Before you dive into the various lenders listed here, you must grasp the fundamental mechanics of your potential debt. Throughout Maryland, most creditors provide two main frameworks for borrowing: secured and unsecured options. Choosing the wrong path can transform a helpful lifeline into a financial nightmare involving the loss of your belongings.
Think of it like choosing a safety net. One method relies on your word, while the other relies on your stuff. Navigating these differences is the secret to keeping your head above water when navigating the choppy waters of credit challenges.
Ultimately, the choice boils down to how much skin you have in the game. Understanding this distinction is the most important step in your journey toward securing the capital you need to move forward.
Loans Without Collateral
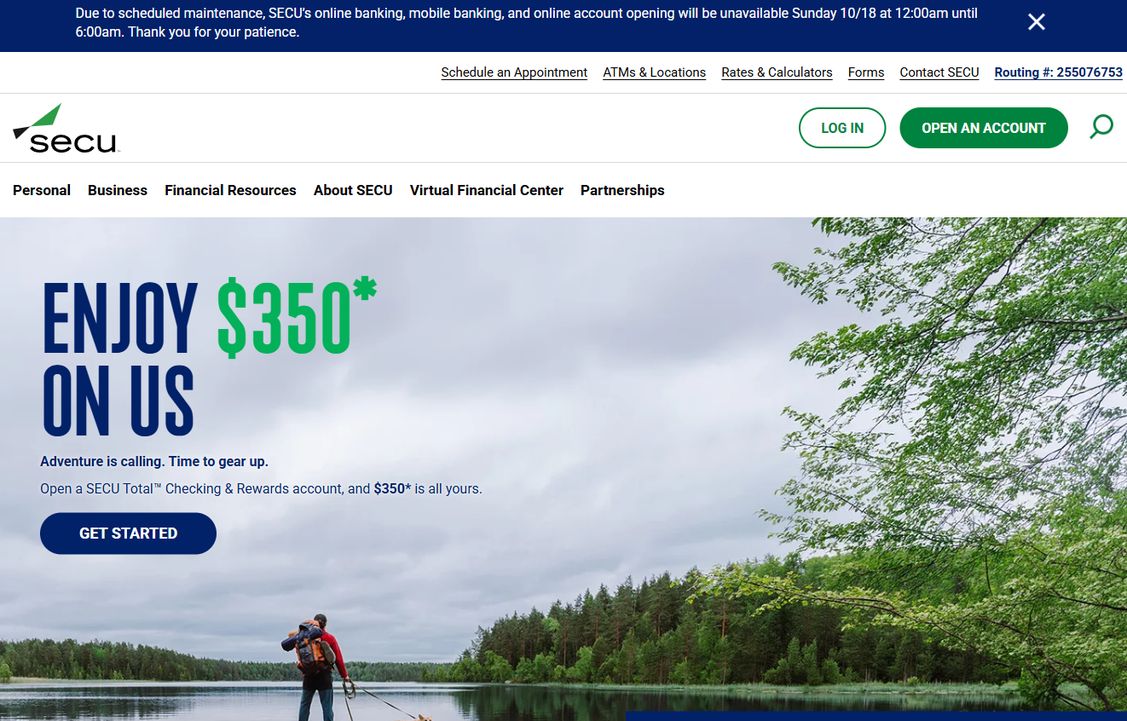
When you opt for an unsecured loan, you aren’t putting any property on the line to back the money. If you choose a route like those provided by SECU or LendingPoint, the institution is essentially betting on your integrity and your ability to fulfill your repayment promise. It is a handshake deal backed by your financial history.
Because the bank cannot immediately grab your car or home if you miss a payment, they tend to dig a little deeper into your bank statements and employment stability. They want to be absolutely sure your paycheck is reliable before they hand over the funds. They are looking for a pattern of stability rather than physical assets.
For many Marylanders with a steady job but a bruised credit score, this is often the smartest move. It allows you to access quick cash without the terrifying possibility of losing your house or your transportation if things get rocky.
Loans Backed by Assets
A secured loan functions on a different level because it requires collateral to act as a safety net for the lender. Imagine you are using a title loan, much like the ones discussed in the MaxCash part of this guide; in that scenario, your car acts as the security for that debt. It is a high-stakes arrangement.
If your financial situation takes a turn for the worse and you cannot meet your obligations, the lender possesses the legal authority to take your asset to recover their money. It is a heavy price to pay for immediate liquidity. You are essentially trading your property for the cash you need right now.
The silver lining is that these options are often much easier to secure if your credit score is in the basement. Because the lender has a fallback option, they feel much safer lending to you. However, the personal danger is significantly higher if your budget fails to recover.
Leading Maryland Financial Providers for Low Credit Scores
1. FastLendGo
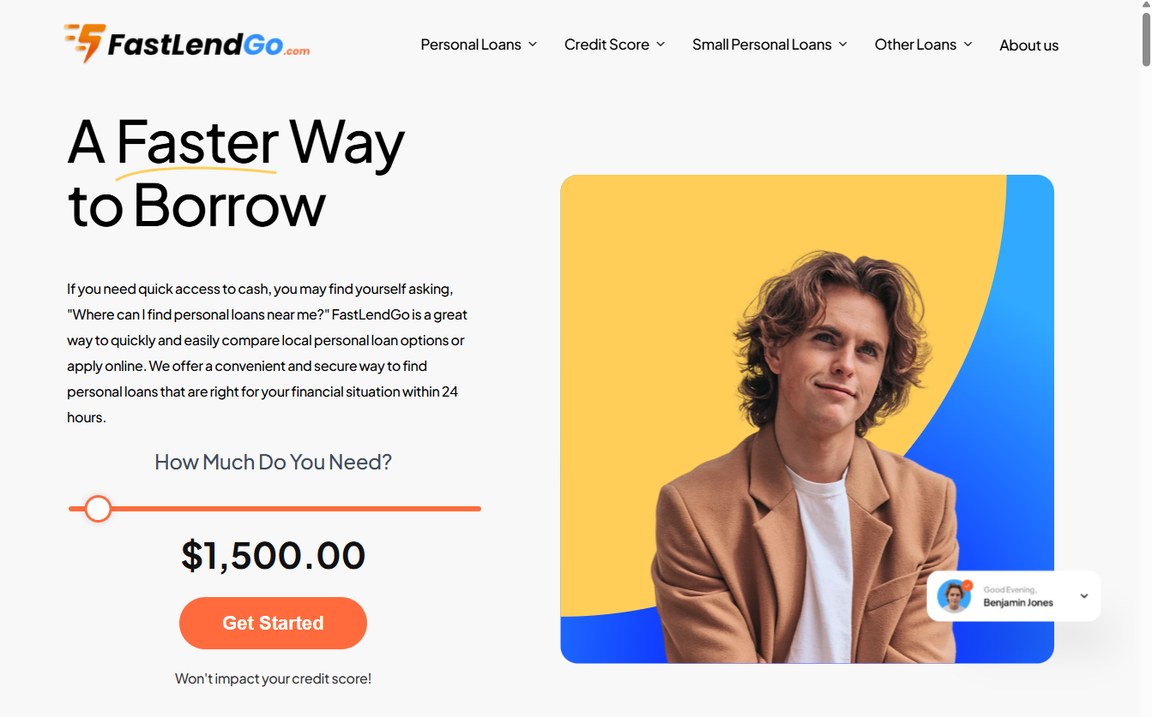
Think of FastLendGo as a digital bridge for anyone needing to survey local personal loan options quickly. Life often throws curveballs that demand immediate cash, such as an unexpected trip to the dentist or a sudden car breakdown. These urgent scenarios simply cannot wait for your next paycheck to arrive.
The platform is engineered to cut through the red tape that usually makes big-box banks such a headache. Instead of wading through piles of paperwork, borrowers can find a streamlined path to the funds they need. You can explore their offerings at fastlendgo.com to see how they work.
Whether you are looking for a small $500 boost or a larger $5,000 personal loan, this provider has you covered. They embrace a diverse range of credit profiles, acting as a vital resource for Marylanders caught in a financial pinch. Because they connect you to various lenders, they often locate matches that traditional banks might ignore.
Upsides:
- Accommodates various needs like dental or auto expenses.
- Accepts a broad spectrum of credit ratings, from excellent to poor.
- Provides a rapid way to evaluate local lending choices.
Downsides:
- The summary doesn’t list specific interest rates.
2. MaxCash
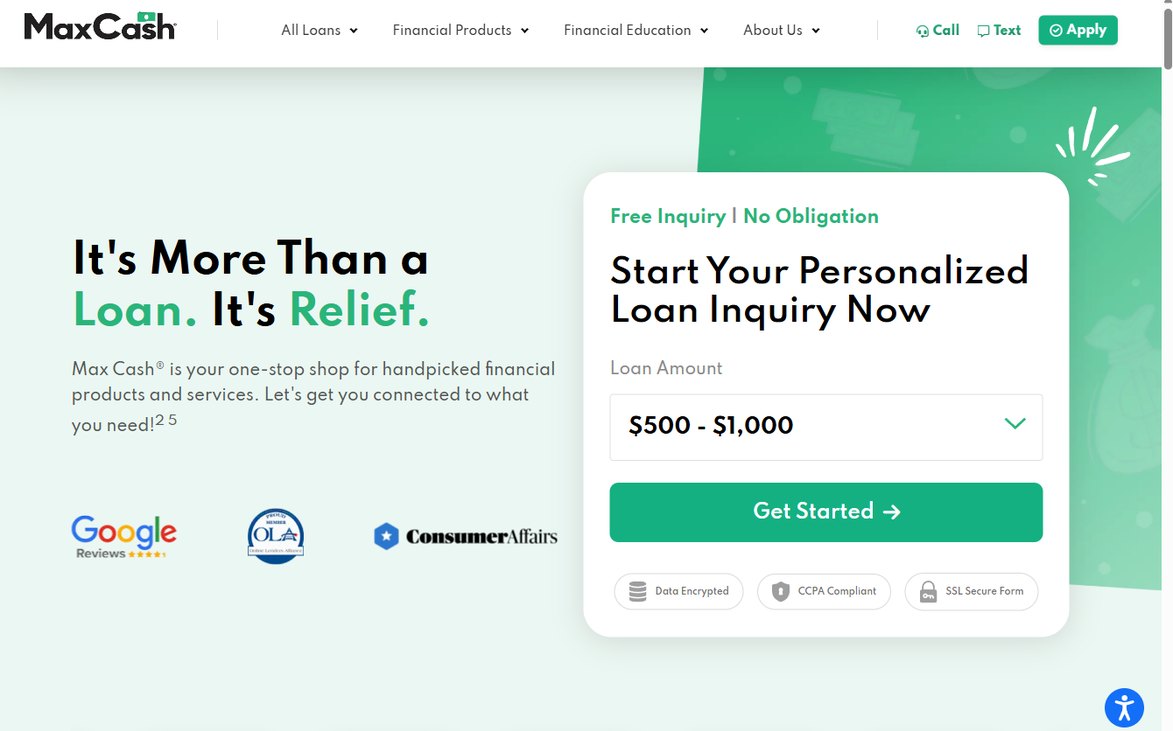
MaxCash views itself as a lifeline rather than just another lending company. When a utility shut-off notice arrives or a home repair becomes unavoidable, Maryland residents can turn to this service. They offer a way to secure installment or title loans in just a few minutes.
This service is built for high velocity, making it perfect for plugging sudden gaps in your cash flow. If you find yourself staring at an empty bank account before payday, this option provides the immediate liquidity you require. It is a fast-acting solution for those in a tight spot.
The variety of available funds is quite impressive, spanning from $250 up to amounts exceeding $10,000. This flexibility turns the service into a true “one-stop shop” for diverse financial products. It is a primary contender for anyone needing instant money rather than waiting several days for a bank transfer.
Upsides:
- Ultra-fast processing, occasionally completed within minutes.
- Offers high upper limits for those using title loans.
- Provides a wide array of different loan varieties.
Downsides:
- Title loans require your vehicle to serve as collateral.
3. LendingPoint
For those chasing larger capital injections, LendingPoint focuses on opening new doors. With limits reaching as high as $36,500, this is a powerhouse for anyone looking to tackle debt consolidation or major home upgrades. It is a robust tool for serious financial moves.
If high-interest credit card debt is bleeding your monthly income dry, a larger loan from a provider like this can be a brilliant strategic move. It allows for long-term restructuring of your finances. Instead of juggling many small debts, you can consolidate them into one manageable payment.
The digital experience is polished and professional, allowing you to check your rates without hurting your credit score. This “soft pull” method is a total lifesaver for shoppers who want to compare options without making their credit report look even worse. It is perfect for those with significant financial goals in mind.
Upsides:
- Features high loan ceilings for major expenditures.
- Checking rates won’t impact your credit score.
- Offers many different loan purposes.
Downsides:
- May demand a slightly better credit score than specialized bad credit lenders.
4. OppLoans
OppLoans operates on the principle that your FICO score isn’t your whole story. By partnering with various banks, they provide personal loans tailored to unique life situations. This is especially helpful if a sudden drop in your credit score has caused you to be rejected elsewhere.
It serves as a supportive alternative for those who feel ignored by the rigid, automated models used by traditional banks. They look at the person, not just the number. This human-centric approach helps bridge the gap for many Maryland residents in need of assistance.
The ability to access same-day funding is a massive advantage if an emergency strikes. Imagine your furnace breaking down during a freezing Maryland winter; having money in your account the same business day is a total game-changer. The application is simple, requiring very little paperwork to get moving.
Upsides:
- Same-day funding is available for those who are approved.
- Your application won’t affect your FICO score.
- No hidden fees are included in the advertised process.
Downsides:
- Approval isn’t guaranteed by credit alone, which makes it somewhat unpredictable.
5. SECU
As the largest state-chartered credit union in Maryland, SECU offers a traditional, community-oriented banking experience. Their unsecured signature loans are a fantastic choice for people looking to cultivate a long-term relationship with their bank. It feels more like a partnership than a transaction.
Because they are member-owned, SECU provides a level of care and local alignment that national banks simply cannot replicate. They offer loans from $300 up to $30,000 with no penalties for paying off your loan early. This is a refreshing departure from the predatory tactics of some lenders.
This flexibility is vital for your financial health. If you land a work bonus or a sudden tax refund, you can wipe out your SECU loan without being hit with extra interest charges. It is a relief for anyone tired of “early repayment penalties” that plague high-interest lenders.
Upsides:
- Zero penalties for applications or early repayment.
- High maximum limits for their unsecured products.
- Deeply rooted within the Maryland community.
Downsides:
- You may need to meet specific membership requirements.
Sorting Through Your Financing Pathways
Selecting a financial partner shouldn’t be a shot in the dark. Before you pick up a pen to sign anything, you really need to squint at the tiny text in those contracts. It’s incredibly easy to get swept up in the rush of a lightning-fast approval process. However, that convenience might end up costing you a fortune if you skip your homework.
Don’t fall into the trap of fixating solely on what you owe each month. While a tiny monthly installment looks attractive, it often signals a much longer repayment timeline. This extended duration means you end up handing over much more money in interest. Think of it as a slow leak in a tire; eventually, you’ll find you’ve spent much more than you intended.
Consider a $2,000 loan where you pay $100 every month for 36 months. Now, compare that to a $2,000 loan with a $200 monthly payment over just 12 months. The first option is a far more expensive way to borrow money. Always add up every single installment to find the total cost of the loan before you commit.
Matching Lenders to Your Immediate Needs
Many people stumble when they fail to weigh a lender’s standing against their personal situation. If you are facing an imminent eviction and need cash immediately, a local credit union might move at a snail’s pace, even if their interest rates are superior. Sometimes, speed is the only thing that matters when the landlord is knocking.
On the flip side, suppose you are looking to consolidate $20,000 in various debts to lighten your monthly interest load. A quick cash advance shop simply won’t have the capacity to assist with such a large sum. In fact, leaning on them for major restructuring could actually toss your finances into a tailspin.
It is vital to ensure the institution’s scale matches the size of your financial hole. Using a sledgehammer to crack a nut is a waste of energy, and using a toothpick for a structural repair is just as dangerous. Always pick a tool that fits the specific job you are trying to accomplish.
Watching Out for Red Flags
Keep in mind that the idea of “guaranteed approval” is nothing more than a fairy tale. Real lenders are legally obligated to check if you can actually pay them back to follow consumer protection regulations. If a company promises they will never say no, you should run the other way.
Such claims are often massive red flags indicating either a total scam or a predatory lender looking to bleed you dry. These outfits prey on desperation rather than providing genuine relief. It is better to be cautious than to be caught in a predatory trap when you are already struggling.
Stick with established, trustworthy providers that are transparent about their requirements. They should respect your long-term financial health while helping you navigate through these choppy waters. A good lender acts as a life jacket, not an anchor that pulls you deeper into debt.
