
Get a 550 credit score personal loan: Top 5 lenders to apply for today
Last updated: 2026-10-16
Navigating your finances while stuck with a 550 credit score often feels like trekking through thick sludge. It is a heavy burden to carry, particularly when life tosses an unexpected wrench into your plans. An emergency trip to the mechanic or a sudden trip to the dentist can drain your savings in a heartbeat.
You might find that mainstream banks pull the ladder up behind them, viewing a 550 rating as a hard “no.” Yet, a few niche lenders remain ready to lend a hand. These outfits utilize alternative metrics that peer beyond your standard FICO digits. They evaluate your steady paycheck and history with your current bank to gauge your reliability.
Searching for a financial safety net involves looking at much more than just the APR. You must balance the speed of the funding against the ultimate price of the loan. A low interest rate is vital for those thinking long-term. Conversely, some folks just need funds hit their account by tomorrow to dodge a late fee or an eviction.
We have curated a selection of dependable lenders for those navigating the fair to poor credit spectrum. This resource aims to simplify the heavy lifting involved in making quick, high-stakes choices. We want to help you find the right path forward during a tight squeeze.
- LendingPoint
- FastLendGo
- Max Cash
- Avant
- Reprise
Our Selection Methodology
Scouring the market for lenders that accept lower credit scores requires looking past the shiny advertisements. It is not merely about finding a firm that gives a thumbs up. The real goal is locating a provider that offers a fair path toward financial assistance.
We prioritize accessibility above all else. Can you actually secure the capital when your credit history has hit some bumps in the road? Simply being able to get approved is only half the battle if the fine print is filled with traps.
A company might brag about massive approval rates, but they aren’t a real lifeline if they hide sneaky service charges or punish you for paying off the debt early. You have to know the exact cost of your commitment before you sign any paperwork.
Our team analyzed providers specifically targeting the 550 score bracket. We focused our scrutiny on three pillars: availability, speed, and transparency. We looked at how rapidly they transfer cash, how candid they are regarding loan totals, and the diversity of their available products.
Every single candidate was vetted to ensure they provide a genuine way out of a pinch. We also put their mobile technology to the test. If a crisis strikes, you need to navigate the entire application on a smartphone while running errands.
A clunky or frustrating digital interface can become a massive obstacle when every minute counts. Our goal was to ensure these tools actually help you in an emergency rather than adding to your stress.
| Lender | Funding Range | Credit Minimums | Speed of Funds |
|---|---|---|---|
| LendingPoint | $1,000 – $36,500 | Fair Credit | Fast Funding |
| FastLendGo | $500 – $5,000+ | Bad/Fair Credit | Quick Access |
| Max Cash | $250 – $10,000+ | Bad Credit | In Minutes |
| Avant | See site | 550 and above | Fast Funding |
| Reprise | See site | See site | See site |
1. LendingPoint
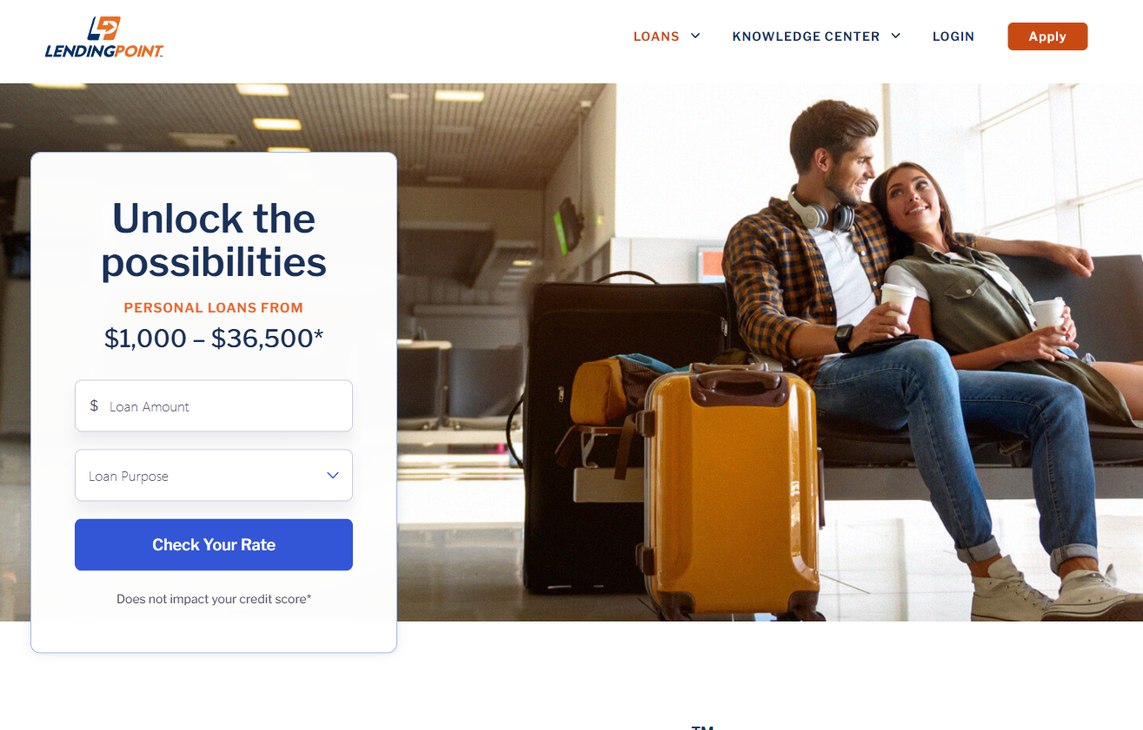
LendingPoint serves as a bridge for individuals trying to walk away from financial tension and toward a more stable footing. They provide a broad spectrum of borrowing options, which makes them a very adaptable choice for many different needs.
You might find yourself needing a small chunk of change to cover a sudden doctor’s visit. Conversely, you may require a much larger sum to wipe out various old debts entirely.
Picture yourself staring at $15,000 in credit card debt with interest rates that feel like they’re suffocating you. A single consolidation loan from LendingPoint can pull all those disparate obligations into one neat, predictable monthly bill. It is an excellent way to stop playing “catch up” with multiple different due dates every single month.
This provider is a strong match for those tackling specific milestones, such as upgrading your home or reorganizing debt. Their digital setup is built for speed to respect your hectic life. You can submit paperwork and receive a verdict in mere minutes, which is a lifesaver when your budget is stretched thin.
Pros:
- Extensive maximum borrowing limit reaching $36,500.
- Checking your rates won’t hurt your credit score.
- Wide range of uses from travel to weddings.
Cons:
- Their eligibility requirements might be tougher than niche bad credit firms.
2. FastLendGo
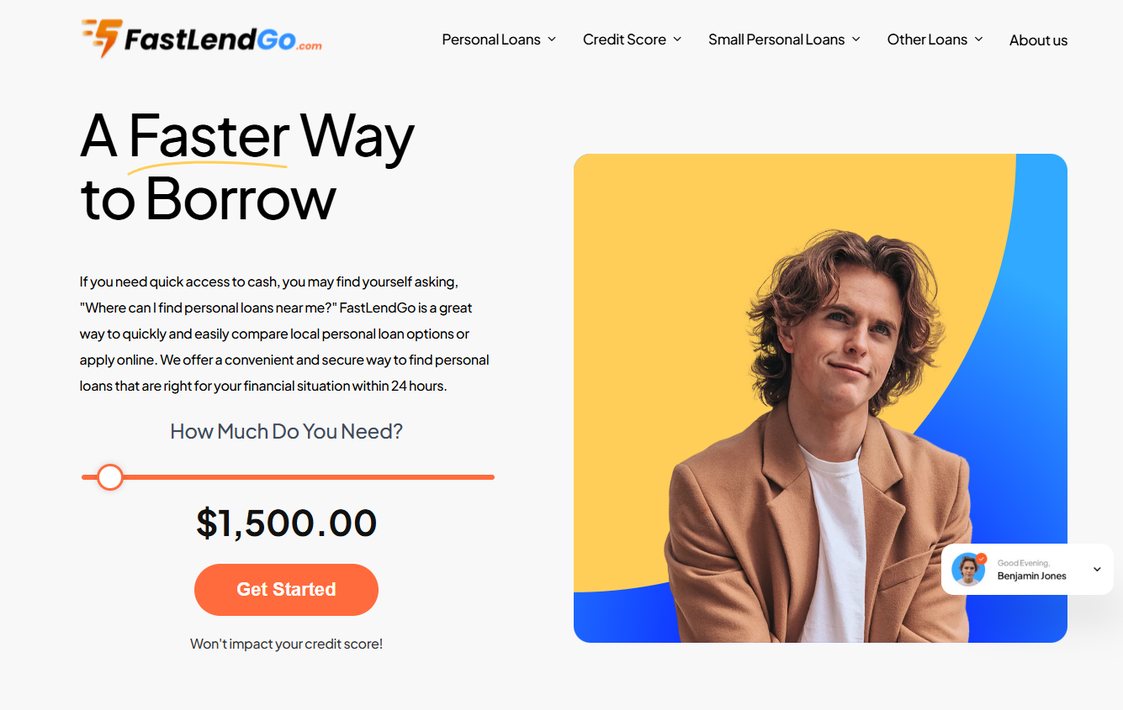
FastLendGo is tailor-made for the person who feels like they need cash by yesterday. Their main specialty is providing rapid access for urgent needs like fixing a car or paying for a dentist visit.
Imagine your car’s alternator dies on a Friday and you must have it fixed by Monday to stay employed. Their specialized loan products are crafted to address that exact nightmare.
They sit in that sweet spot between traditional bank loans and the high-cost world of payday lenders. This setup provides much more long-term stability than a quick cash advance, but they move much faster than a standard big-name bank.
Whether you are looking for a $500 boost or a $5,000 loan, their tiered structure accommodates you. This flexibility is a godsend when your score is stuck in the tricky 550 territory. Instead of being saddled with a massive debt you can’t manage, you can pick a smaller amount that matches your specific crisis.
Pros:
- Offers loans for specific emergencies like motorcycle or roof repairs.
- Provides tiny loan amounts for very immediate needs.
- Features options for first-time borrowers and high earners.
Cons:
- The sheer volume of product types might be confusing for some users.
3. Max Cash
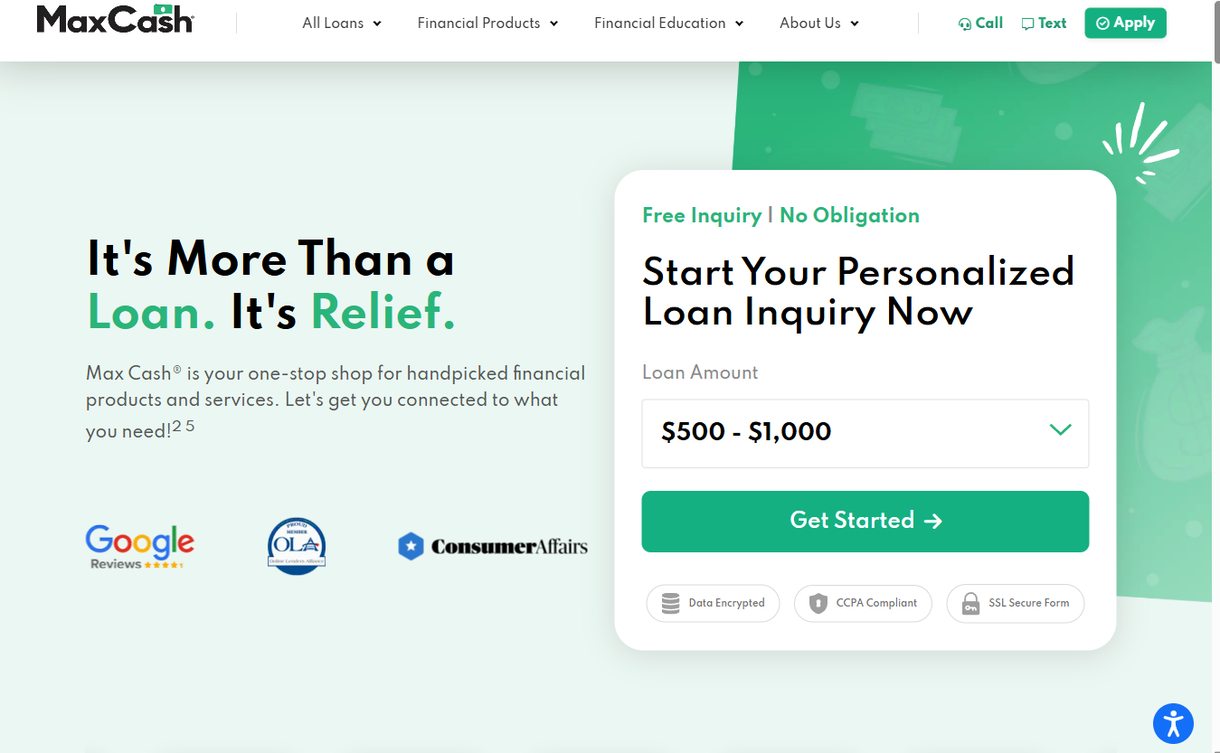
Max Cash functions like a digital matchmaker for financial relief. For those wrestling with a 550 score, they provide a streamlined way to encounter personalized lender matches tailored to you. Their technology links you with exactly what you require, saving you from the headache of browsing hundreds of different websites manually.
Rather than offering a generic, one-size-fits-all solution, they employ a smart algorithm to locate the lender most likely to say yes to your specific profile. It is a matter of efficiency rather than blindly casting a wide net and hoping for the best.
They excel at providing highly accessible amounts, with entries as low as $250. This is ideal for those micro-emergencies where a large loan would simply be overkill. If you have a $300 utility bill, taking out a $3,000 loan would be a massive mistake. Max Cash lets you fix the small leaks without the heavy weight of excessive interest.
Pros:
- Incredibly low starting points for loan amounts.
- Rapid inquiry process that carries no obligation.
- Manages a huge variety of different credit backgrounds.
Cons:
- Their focus on small amounts might not work for major debt restructuring.
4. Avant
Avant is a significant contender for anyone looking to make forward progress in their financial journey. They have built a reputation for considering applicants whose scores sit around 550. This makes them a crucial option if you have been repeatedly turned away by traditional banking institutions.
While some lenders only fixate on your FICO score, Avant takes a much broader look at your overall financial health. This can be a total game-changer for people who have faced recent financial setbacks but still maintain a regular, steady income.
This lender focuses on providing long-term solutions, such as debt consolidation or funding home improvements. If you manage to get your application in before their afternoon cutoff, you might see the funds arrive in your account remarkably fast. Their platform is built for the modern user who wants to run their finances entirely through a mobile app.
Pros:
- Specifically targets the 550 credit score demographic.
- Capable of very fast funding for those who are approved.
- Provides a mix of loans and credit cards for various needs.
Cons:
- Approval is highly contingent on specific timing and your unique criteria.
5. Reprise
Reprise functions in a totally different arena, concentrating on high-tech tools and AI-driven solutions. It is not a standard consumer personal loan lender like the other companies on this list. Instead, it represents the cutting edge of data management and financial technology.
They are much better suited for businesses or tech-savvy entities looking for advanced data injection and demo creation. It is a specialized toolkit for people who need to present complex datasets in an interactive format, rather than a regular consumer looking for a quick loan.
If a fintech startup needs to show potential investors exactly how a loan application workflow functions, Reprise provides the tools to build that immersive experience. It is about the sophisticated technology operating behind the curtain rather than a customer standing at a teller window.
Pros:
- Very advanced AI toolkit used for creating demos.
- Streamlined capabilities for data injection and presentation.
- Makes sharing product tours incredibly easy.
Cons:
- This is not a traditional provider of personal loans for individuals.
The Real Price of Credit: Measuring APR Against Monthly Obligations
When your finances are in a tight spot, it is incredibly tempting to chase the smallest possible monthly bill. You might find yourself comparing two different loan proposals side by side. Imagine one asks for $50 every month, while the other requires $75 to keep the account current.
At first glance, the $50 choice feels like a lifesaver because it keeps more cash in your wallet right now. It feels like a breath of fresh air during a storm. However, relying on this single metric is like navigating a ship without a compass; it is a recipe for disaster.
The actual expense of your debt is hidden within the Annual Percentage Rate, or APR. A bank could lower your immediate monthly burden by simply stretching your repayment period out to seven years. This might make the monthly sting feel much less intense on a day-to-day basis.
The catch is that interest accumulates like snow in a drift during a blizzard. While your monthly obligation stays low, the interest can balloon significantly. You might find yourself returning much more than you originally borrowed, potentially paying back double or even triple the initial amount.
You need to look at the big picture rather than just the immediate snapshot. Before signing any paperwork, ask yourself a critical question: “How much cash will have left my bank account by the time this debt is fully settled?” This is the ultimate litmus test.
If that final sum is vastly larger than the principal amount you received, you are essentially buying time. You are paying a steep premium for the luxury of a smaller monthly installment. It is vital to weigh that convenience against the heavy weight of long-term interest costs.
Navigating the Differences Between Hard and Soft Credit Checks
If your credit score is hovering around 550, you need to grasp how your search for financing influences your standing. Not all credit checks are created equal in the eyes of the bureaus. You will encounter two distinct categories: soft inquiries and hard inquiries.
A soft pull happens when a company scans your history to see if you qualify for a deal. You see this most often when clicking buttons that say “check your rate” on various websites. It is like testing the waters before diving into a deep pool.
These specific checks are harmless to your financial health. They remain invisible to other banks when they review your profile. Because they do not impact your score, you can use them to window shop for better terms without any fear of a penalty.
On the other hand, a hard pull is triggered once you formally apply for a credit card or a personal loan. This tells the credit reporting agencies that you are hungry for new debt. To a lender, this sudden hunger can signal a potential risk to your stability.
Every time a hard inquiry lands on your report, your score might take a minor, fleeting hit. While these dips are usually small, they can add up if you are not careful. If your goal is to mend your credit, treat these pulls like precious resources that shouldn’t be wasted.
Navigating the Lending Landscape
Selecting a financial partner is much like shopping for footwear. If the fit is off, the entire trek becomes a literal and figurative headache. You must scrutinize the complete cost of borrowing rather than just eyeing the monthly installment. A small monthly bill might simply be a mask for a predatory interest rate that slowly bleeds your bank account dry.
Always demand a formal truth-in-lending disclosure from your chosen provider. Since this is a mandatory legal document, it removes any ambiguity by detailing the full finance charge. Knowing exactly how much cash will leave your pocket by the end of the term provides much-needed clarity.
Avoid the “shotgun approach” of spamming applications across various banks at once. When you do this, a flurry of hard inquiries hits your credit profile simultaneously. This makes you appear financially distressed to potential creditors, which can cause your score to plummet even further. It is much better to target one or two specific lenders that actually align with your current goals.
Don’t ignore the tiny text hidden in the contract. It is vital to grasp the specific repayment schedule and look out for any prepayment penalties. Some companies will actually fine you for being responsible and trying to settle your debt ahead of schedule. You shouldn’t be penalized when you finally get your finances back on track. Treat these loans as a bridge to recovery, but walk across it carefully.
