
Get First Time Personal Loans No Credit History Fast
Last updated: 2026-10-16
Stepping into a local bank to request a loan without an established credit profile can feel like stumbling through a dark hallway without a candle. If you have never dealt with auto loans or credit card interest, traditional institutions might act as if you simply do not exist. It is a maddening loop where you must already possess a credit trail to prove you are a reliable borrower.
This financial stalemate often leaves many individuals stuck in a state of uncertainty. Newcomers to the country, early-career professionals, and those rebuilding after a rough patch frequently find themselves barred from the very resources required for stability. It sometimes feels like the entire economic game is rigged to keep you on the bench.
Luckily, the lens through which lenders view your bank account has evolved significantly throughout 2026. Instead of fixating solely on a FICO score to determine your future, many companies now prioritize your actual earnings and employment consistency. Your history of paying rent and monthly utility bills carries far more significance now than it did back in 2021.
By evaluating your complete financial narrative rather than a single digit, creditors can offer capital to millions who were once deemed “unscorable.” This move toward diverse data sets ensures that your steady paycheck and on-time bill payments are your greatest assets when meeting with a loan officer.
- JetzLoan
- Discover
- OppLoans
- OneMain Financial
- Coastline Credit Union
Our Methodology for Selecting Lenders for First-Time Borrowers
Our team set out with a clear mission: find financing options that welcome those without an established credit profile. We prioritized institutions that allow for a “soft pull” or a preliminary pre-qualification stage. This distinction is the difference between life and death for your credit score.
A soft inquiry allows you to browse potential interest rates without any negative consequences. Think of it like window shopping at a mall; you can check the price tags without a single penny being spent or any damage to your financial reputation.
In contrast, a “hard inquiry” occurs when a company conducts an intensive deep dive into your credit history to finalize an application. This specific action can unfortunately drop your FICO score. By favoring lenders that stick to soft checks during the first steps, we ensure your burgeoning credit score remains unscathed.
Efficiency and honesty topped our list of essential criteria. A lender that hides sneaky costs in the legalese or leaves you hanging for weeks while you wait for funds is not helpful in a crisis. When your transmission dies or a sudden doctor’s bill arrives, you want liquid cash, not a mountain of excuses.
We hunted for businesses that offer upfront transparency regarding costs and rapid disbursement. Our ideal partners provide straightforward loan amounts, lightning-fast transfers, and accessible customer support representatives. You shouldn’t have to fight a chatbot just to get a straight answer about your money.
We also demanded that every lender explicitly disclose their APR. This single figure serves as the ultimate truth, encompassing the base interest rate alongside any compulsory administrative fees. Relying on the APR reveals the actual price tag of your loan over the total life of the debt.
Furthermore, we scrutinized whether a loan serves as a stepping stone for financial health or a pitfall for endless debt. We gravitated toward providers that offer steady, predictable monthly installments. You must steer clear of predatory structures that trigger a downward spiral of repayment issues.
Our research included a deep dive into how interest is calculated. We examined the nuances between compounding interest and simple interest models. Since the former can cause your total debt to balloon much faster than most people realize, avoiding it is key to long-term stability.
| Provider | Available Funding | Transfer Timing | Score Impact Assessment | Loan Duration/Limits |
|---|---|---|---|---|
| JetzLoan | $500 – $35,000 | Could take 24 hours | No hard credit pull | see site |
| Discover | $2,500 – $40,000 | Potentially next business day | No impact to credit score | see site |
| OppLoans | see site | Same-day funding available | Does not affect FICO score | see site |
| OneMain Financial | $1,500 – $30,000 | Within 1 hour of signing | No credit score impact | 24-60 months |
| Coastline Credit Union | see site | see site | see site | see site |
Leading Lending Options for 2026
1. JetzLoan
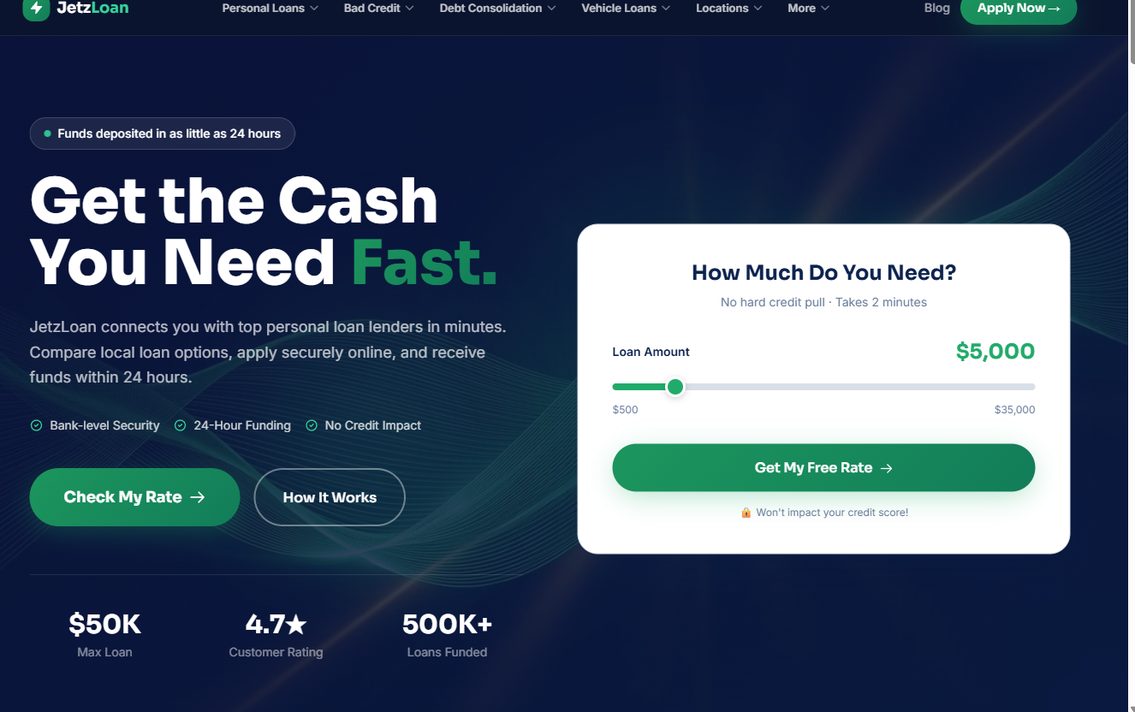
Navigating the murky waters of a thin credit file can feel like walking a tightrope. JetzLoan acts as your guide, bridging the gap between you and a variety of premier lenders. If you find yourself facing a sudden car repair or need to consolidate urgent debts, this service streamlines the entire search process.
Why spend your afternoon juggling a dozen different applications? Doing so risks a cascade of hard inquiries that can bruise your score. Instead, JetzLoan bundles your possibilities into one cohesive, efficient experience. This approach protects your financial standing while you are still getting your bearings.
The process moves at lightning speed, typically wrapped up in just two minutes. Because they utilize a “no hard credit pull” approach during the initial phase, you can shop around without any anxiety. You might even find yourself eligible for as much as $35,000 without any immediate pressure.
This is a goldmine for first-time borrowers who are still learning to decode complex loan offers. You can explore your boundaries without the fear of accidentally damaging your credit standing before you truly grasp the fine print.
Pros:- Funds can arrive within 24 hours
- Borrow up to $35,000
- Quick two-minute application process
- Inquiry does not affect your credit score
- Requires completing a basic form to start
2. Discover
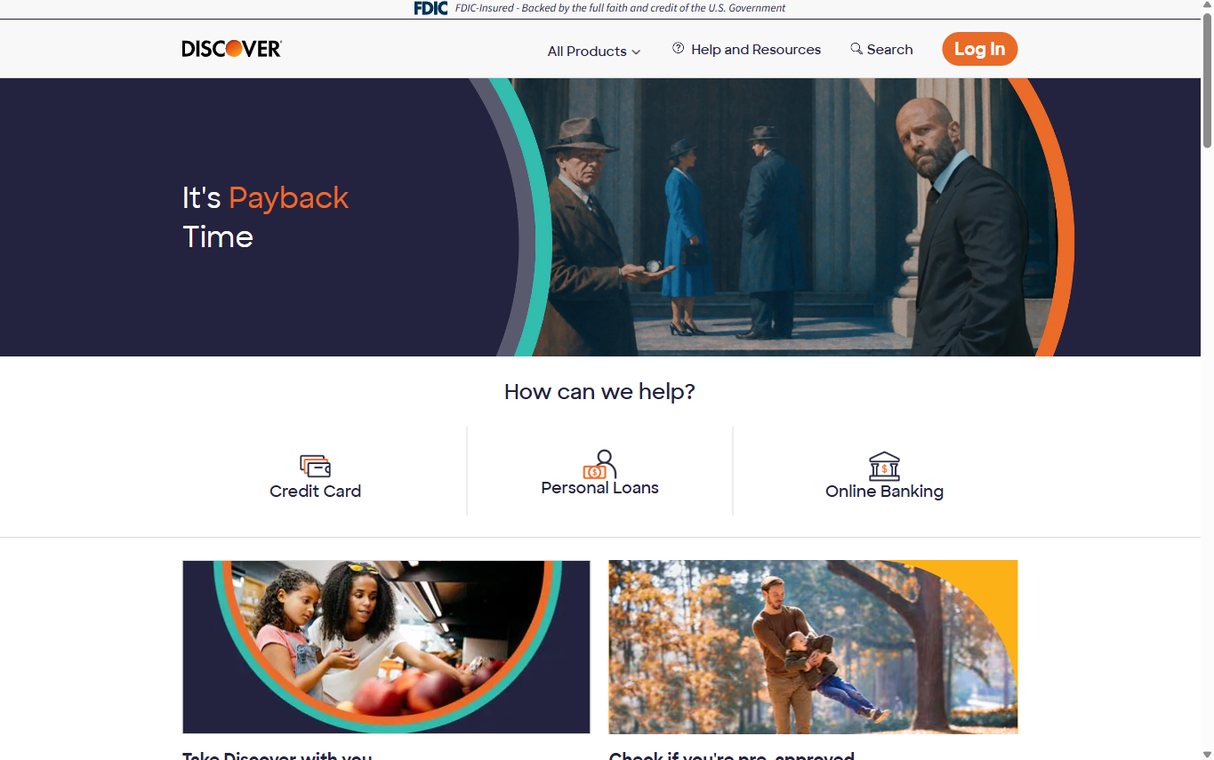
When you are looking for a sense of security, Discover stands as a titan of the banking world. They aren’t just looking to hand you a quick check; they aim to be a long-term pillar in your financial life. With APR rates starting as low as 6.99%, they offer a genuine ladder for upward mobility.
Transitioning from “no credit” to “rebuilding” requires a stable environment, and Discover provides exactly that. Their system rewards the discipline of on-time payments through a highly structured framework. Their pre-approval check is a “safety first” process that leaves your credit score untouched.
If the stars align and you get approved, the capital can land in your bank account as early as the next business day. This makes them an ideal partner for anyone with a steady paycheck who wants the prestige of a major institution.
Because of their massive scale, their digital ecosystem is top-tier. Managing your monthly payments or tracking your financial journey is a breeze thanks to an incredibly smooth mobile application.
Pros:- Loan ceilings reach up to $40,000
- Competitive APRs starting at 6.99%
- Next-day funding availability
- Highly reputable and FDIC-insured
- Income verification may be quite rigorous
3. OppLoans
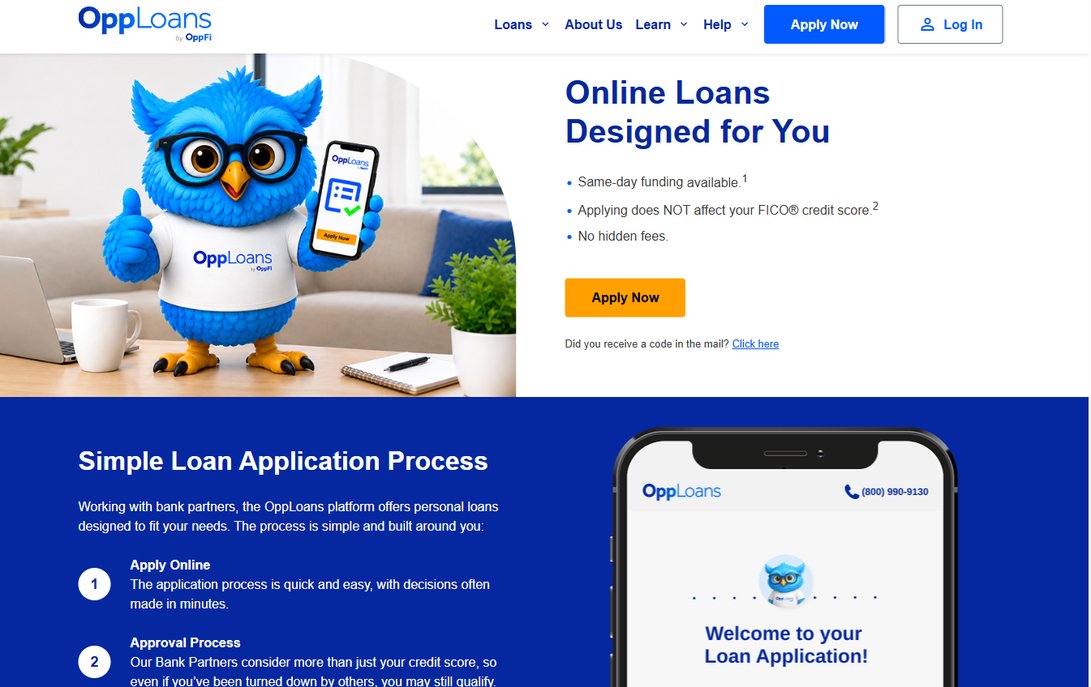
Have you ever felt like every big-name bank has slammed the door in your face? OppLoans was built for that exact person. Instead of obsessing over a static FICO number, they dig deeper to find reasons to grant you a “yes.” This makes them a lifeline for those facing sudden life hiccups, like job gaps or medical bills.
They prioritize your current ability to manage money, often looking at real-time bank activity rather than just a bureau’s snapshot. Speed is their specialty, with the potential for same-day funding. It is a significantly safer harbor than the treacherous waters of the payday loan industry.
We all know that payday loans are notorious for predatory interest rates that can soar above 400% APR. Such terms often act as a trap, pulling borrowers into a never-ending cycle of debt. OppLoans serves as a structured, healthy alternative to that trap.
You can address your immediate financial needs without the terrifying hidden fees or astronomical costs. It is a way to get cash without the predatory sting that makes other quick-loan options so dangerous for the unwary.
Pros:- Potential for same-day funding
- FICO score remains unaffected
- Tailored for those rejected elsewhere
- Transparency with no hidden fees
- Rates may exceed those of traditional banks
4. OneMain Financial
OneMain Financial strikes a perfect balance between digital convenience and the warmth of human interaction. Sometimes, a chatbot just won’t cut it, which is where their 1,300 physical branches become a massive asset. If your income has changed recently, you might want to sit down with a real person to explain your story.
That human touch can be the deciding factor between a rejection and an approval. They offer a wide range of repayment terms, from 24 to 60 months, allowing you to customize your monthly budget. With loans beginning at $1,500, they cover everything from tiny home fixes to major debt consolidation projects.
The turnaround time is nothing short of impressive. You could see those funds in your account just one hour after you sign the paperwork. It is quite rare to find such rapid delivery from a lender with such a massive physical footprint across the country.
Pros:- Huge branch network for face-to-face help
- Rapid funding (one hour after signing)
- Flexible repayment terms up to 60 months
- Pre-checks that carry no obligation
- Interest rates can fluctuate widely
5. Coastline Credit Union
For those just stepping into the world of borrowing, credit unions are often the industry’s best-kept secret. Coastline Credit Union operates on a member-focused philosophy, which typically translates to a much more personal touch. Unlike massive banks driven by shareholder profits, credit unions are cooperatives owned by the people they serve.
Because their mission is to support the community, their underwriting can often be more lenient for local residents. You might need to meet specific membership criteria, such as living in a certain county or working in a specific field. However, the long-term perks are frequently worth the extra step.
They provide a diverse array of loan solutions alongside modern digital tools to help you master your money. It is a “slow and steady” approach to building a rock-solid financial foundation for your future.
At the end of the day, this lender is actually invested in your long-term prosperity. They aren’t just looking for how much interest they can squeeze out of you this month; they want you to succeed.
Pros:- Service model centered on members
- Wide array of financial products
- Likely better rates over the long term
- Membership requirements may apply
Cracking the Code of Loan Costs
Scanning through various lending advertisements can feel like walking through a minefield of confusing figures. You are bound to encounter two distinct metrics that look similar but carry very different weights. To keep your finances from taking a hit, you must distinguish between them before signing anything.
The first figure you will stumble upon is the Simple Interest Rate. Think of this as the base price for renting someone else’s money. It represents the fundamental cost of borrowing the principal amount, yet it serves as an incomplete picture of your total financial commitment.
The second figure, which is the one that truly dictates your monthly budget, is the Annual Percentage Rate (APR). This number is a much more honest reflection of your reality. It wraps the interest rate together with every extra charge required to finalize the deal, such as documentation or origination fees.
To put this into a real-world scenario, imagine you secure a $5,000 loan. A lender might promise a 10% interest rate, but they slap a $500 “processing fee” onto the contract. In this case, your APR will be significantly higher than that initial 10% figure.
When you are shopping around, make the APR your primary compass. Let’s say Lender A offers a 7% rate but hides hefty fees in the fine print. Conversely, Lender B might offer an 8% rate with zero additional costs. In this comparison, Lender B is actually the more economical option for you.
Don’t let a flashy, low interest rate lure you into a bad deal. It is often a shiny distraction designed to hide the true expense of the loan. Always look at the APR to see the full truth of what you will ultimately pay back.
Smart Strategies for First-Time Borrowers
Stepping into the world of credit can feel like walking a tightrope without a net. To ensure you don’t lose your footing, you must follow a few golden principles that protect your wallet and your peace of mind.
Think of these guidelines as your financial compass. Without them, it is incredibly easy to drift into a sea of debt that feels impossible to navigate. Staying disciplined now ensures your future self stays solvent.
- The 30% Cap on Monthly Dues: A wise rule of thumb is to ensure your debt obligations never swallow up more than 30% of your net income. Suppose your paycheck lands in your account at $3,000 every month. Your total repayment amounts should stay significantly lower than that threshold. If a lender demands half of your take-home pay just to cover installments, you are walking straight into a financial storm where default becomes a real possibility.
- Beware the Trap of Extended Terms: It is incredibly seductive to opt for a 60-month repayment period rather than a 36-month one because the smaller monthly chunk looks easy on the pocket. However, length comes at a steep price in the form of extra interest. By stretching the loan out to 60 months, you might find yourself paying back almost twice the original principal. If your budget allows for it, grab the shorter timeframe to save cash.
- Calculate the Actual Price of Borrowing: Before you ink your signature on a contract, ask yourself a vital question: “What is the sum of every single payment I will make until this is over?” This final figure represents the real cost. If you take out a $2,000 loan but the total repayment amounts to $3,500, that extra $1,500 is the fee for using that capital. Checking this prevents a massive shock when your bank statements eventually arrive.
Mapping Out Your Initial Loan Journey
Before clicking that final application button, take a moment to sketch out a roadmap. Taking on debt is a long-term promise to follow a strict repayment calendar, rather than simply grabbing fast cash. You should determine the precise figure you require to avoid the trap of over-borrowing. It is far less stressful to tackle a modest debt than a mountain of it.
Many borrowers mistakenly grab the highest limit possible, thinking they are building a “safety net.” In reality, they just end up handing over extra interest on funds that stayed in their pockets. It is better to stay lean and focused on your actual needs. Don’t let the temptation of a large sum lead you into a financial hole.
Avoid focusing solely on the monthly installment. You must scrutinize the APR alongside the full sum you will ultimately repay over the loan’s duration. While a small monthly bill looks tempting, it often signals a much longer timeframe. This can end up costing you thousands of extra dollars in interest payments over time.
Try playing with an online calculator to see the real math at work. Adding just $25 extra to your monthly payment can be a total game-changer. Such a small tweak can save you hundreds of dollars over the long haul. It is a simple way to shave years off your debt commitment.
Get your paperwork organized before you even begin the process. Even if a lender claims they won’t perform a hard credit check, you will eventually have to verify your identity and earnings to finalize the deal. Having everything ready to go prevents a last-minute scramble when things get serious.
Keep your most recent pay stubs, bank records, and a valid ID close at hand. If your goal involves debt consolidation, make sure you have those specific creditor statements ready as well. Some lenders prefer to pay your old bills directly, which makes the entire transition feel much smoother for everyone involved.
