
Top-Rated Online Personal Loans in Laredo TX for Quick Cash
Last updated: 2026-10-16
Imagine standing in a parking lot as a mechanic hands you a bill that makes your stomach drop. A sudden transmission breakdown or an unexpected trip to the dentist can feel like being lost in a thick fog without a compass. For those living in Laredo, the weight of the debt is often secondary to the sheer panic of not knowing where the money will come from.
Life throws curveballs, and sometimes a medical emergency arrives without a moment’s warning. When the unexpected happens, you aren’t just looking for a quick fix; you are searching for transparent terms and real certainty. It is easy to feel overwhelmed when your bank account doesn’t match the urgency of your reality.
The digital landscape has completely rewritten the playbook for how we handle money. It is incredibly easy to get swept up by a glossy web advertisement that promises the world. However, many residents find that “instant” promises are just smoke and mirrors, often leading to slow transfers or predatory interest rates that dwarf standard bank offers.
Navigating the web requires a sharp eye to distinguish a local credit union from a high-speed digital platform. You need to know if a lender’s speed and borrowing limits actually align with your specific needs. Making this distinction is your best defense in keeping your household budget from sinking under the pressure of high-cost debt.
- Parra Loan Company
- JetzLoan
- Bridge Credit Union
- GoCredit
Assessing Your Choices Between Regional and Online Lenders
Our evaluation centered primarily on the velocity of fund distribution. When hunting for financing in the Laredo area, most people are racing against the clock. In this bustling border hub, where the rhythm of trade dictates your livelihood, a slow payout is a heavy burden.
Missing a deadline isn’t merely a nuisance; it can be a financial catastrophe. If your car breaks down and you can’t afford the fix, your ability to earn a paycheck vanishes instantly. We prioritize lenders that understand this urgency.
We also scrutinized the ceilings on borrowing limits and the impact on your credit profile. A “soft pull” serves as a golden ticket for those uncertain about their financial health. This method allows you to browse various interest rates without any penalty.
If a company utilizes a soft pull to present quotes, your credit report remains untouched. You could potentially weigh five different options and still see zero movement in your FICO score. This period of comparison is your prime opportunity to hunt for the most competitive APR.
Consult the following chart to grasp how various lending models operate in the current economic landscape:
| Lending Category | Core Advantage | Ideal Use Case | Funding Velocity |
|---|---|---|---|
| Online Marketplaces | Extensive options and high caps | Significant costs (Real Estate/Large Vehicle) | 1 to 2 Days |
| Rapid-Access Lenders | Instant liquidity | Brief emergencies (Bills/Maintenance) | Moments to a few hours |
| Credit Unions | Community ties and reduced rates | Enduring stability and minimal APR | 3 to 7 Working Days |
| Credit Enhancement Tools | Boosting your score | Fixing your credit track record | Depends on specific savings strategy |
Leading Laredo Online Loan Options
Parra Loan Company
When life throws a wrench in your plans, Parra Loan Company is there to provide a quick financial lifeline. They specialize in rapid-response lending rather than managing long-term debt. Their loans act as a temporary fix for immediate hurdles that pop up without warning.
Imagine your car breaks down, leaving you with a $400 repair bill that stands between you and your paycheck. In a situation like that, a multi-year repayment schedule feels like overkill. This lender excels at navigating these high-speed emergencies where time is of the essence.
The company offers multiple ways to get assistance, giving you much more freedom than your typical digital-only lender. You can submit an application via your smartphone, talk to a representative on the phone, or visit a branch in person. It is a very flexible system.
Pros:
- Borrow anywhere from $100 up to $1,840.
- Signature loans do not require any collateral.
- The approval process is lightning-fast, often within minutes.
Cons:
- The maximum ceiling for loan amounts is somewhat limited.
JetzLoan
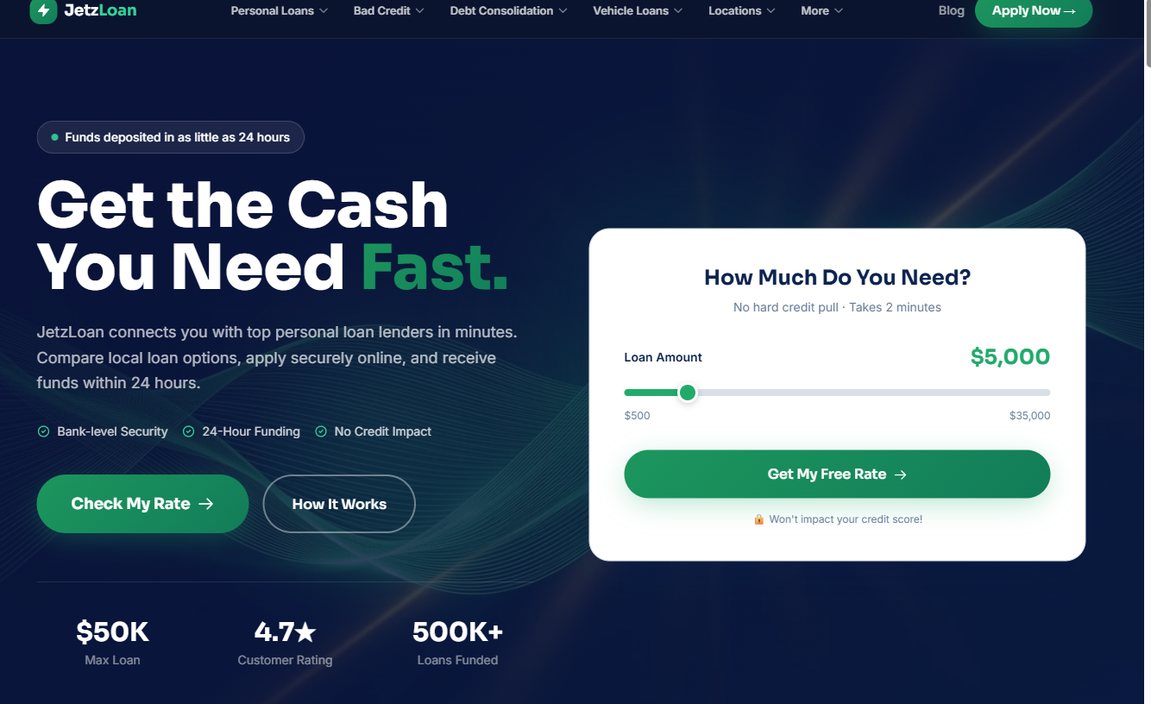
Think of JetzLoan as a massive intermediary within the financial landscape. Rather than acting as a single bank, they function as a bridge between you and a wide variety of lenders. This method allows you to access much larger sums, potentially reaching up to $50,000.
This approach is fundamentally different from visiting a traditional local bank. While a bank is limited by its own internal vault, JetzLoan scans a broad network of sources to find the best possible match for your specific credit profile.
For those with less-than-perfect credit, this service is a real breath of fresh air. Because they utilize a “no hard credit pull” system to check your rates, you can browse different options without your credit score taking a dive. It is perfect if you need $15,000 for a home upgrade or a medical expense.
Pros:
- Loan ceilings can reach as high as $50,000.
- You can receive your funds in as little as 24 hours.
- Checking rates won’t negatively impact your credit score.
Cons:
- The brokerage model means you are working with multiple lenders.
Bridge Credit Union
Bridge Credit Union offers a banking experience rooted deeply in community values. Their approach is far more conventional and personal than most. They provide helpful features such as “skip-a-pay” arrangements and specialized loans for the holiday season, which can be a lifesaver during a tight month.
Because credit unions are owned by their members, their primary goal is serving the local community rather than padding the pockets of shareholders. This distinction often results in much more flexible lending rules for members who maintain good standing with the institution.
If you are looking for stability, this is a fantastic choice. Their services extend to both household and professional needs, allowing you to manage everything under one roof. A Laredo small business owner might find it incredibly convenient to manage personal bills and commercial cash flow in one place.
Pros:
- Features specialized holiday deals and skip-a-pay options.
- Provides services for both personal and business applications.
- Operates with a strong emphasis on member-based banking.
Cons:
- The process may demand more formal paperwork than instant lenders.
GoCredit
GoCredit takes a unique angle by prioritizing the improvement of your credit history. Their mission goes beyond merely handing out cash today; they want to ensure you can secure much better terms in the future. This is achieved through a “loan-to-savings” framework.
Under this model, a specific portion of your monthly payments is channeled directly into a savings account that you eventually own. It functions as a dual-purpose financial instrument. This is particularly advantageous for younger borrowers or those working hard to repair their credit standing.
By merging a loan with a savings component, you transform a debt into a stepping stone toward long-term financial health. Instead of simply paying off a bill and returning to a zero balance, you end the process with a built-in cushion to ward off future debt cycles.
Pros:
- Access to loans with limits up to $4,000.
- Assists in building both credit history and personal savings.
- Features a fast and secure application setup.
Cons:
- The focus on credit growth might not suit those seeking very large sums.
Deciphering the Real Price Tag of Your Loan
Before you pick up a pen, you must scrutinize the Annual Percentage Rate (APR). It is a common mistake to focus solely on what you owe each month. That figure tells only a partial story of your true financial commitment.
The APR acts as the ultimate truth-teller for your debt. It wraps together the interest rate alongside pesky administrative charges and origination fees. Think of it as the full receipt for your borrowed funds.
Numbers can be deceptive if you aren’t watching closely. A loan offering a 10% interest rate paired with a $500 fee might actually be more expensive than a 12% loan that carries zero fees. Always look at the bigger picture.
The length of your repayment schedule is another crucial piece of the puzzle. Shorter durations act like a sprint; they save you a mountain of interest over time, but they require much larger monthly outlays.
Consider a $2,000 loan with a 15% interest rate. If you pay it back in 12 months, the total interest paid is significantly lower than if you stretched that same debt across a 24-month window. It is a classic balancing act.
You must weigh your current monthly cash flow against your long-term goal of staying debt-free. Finding that “sweet spot” between manageable payments and low interest is the key to financial peace of mind.
When you are weighing your options, keep these three distinct financial situations in your mind:
Rapid Emergency Repairs: Sometimes, you just need $300 to $1,000 right this second to fix a broken appliance. In these high-pressure moments, speed is king. A high-interest, short-term option might be a lifesaver if it prevents a job loss due to vehicle issues.
Strategic Debt Management: If you are looking to consolidate, you might need between $2,000 and $7,000. Your objective here is to migrate expensive credit card balances into a single, lower-interest loan to lighten your monthly weight.
Significant Life Transitions: When facing $10,000 or more for medical expenses or home upgrades, you need a marathon mindset. Focus heavily on securing the lowest possible APR and the most stable, predictable repayment terms available.
Steering Clear of Money Traps
When life throws you a curveball and you need cash fast, your first instinct might be to snap up the very first digital offer that lands in your inbox. However, acting on impulse is often a recipe for disaster. You should always verify whether a company conducts a hard credit pull before you sign anything.
A hard inquiry signals to the financial world that you are aggressively hunting for more debt. This can paint you as a risky bet to other banks, potentially driving up the interest rates on your future applications. It is like leaving a trail of breadcrumbs that tells everyone you are desperate for funds.
Don’t get blinded by the speed of the transaction. A quick deposit that arrives in mere minutes might feel like a lifesaver in a pinch, but the hidden costs can be predatory. If you aren’t careful, astronomical interest rates can transform a minor financial hiccup into a mountain of debt that takes years to climb.
Always demand a “Truth in Lending” disclosure from your provider. This specific document acts as a legal safeguard, forcing the company to be transparent. It must explicitly state the total amount you will have repaid by the time the loan term concludes, leaving no room for guesswork.
Scrutinize the fine print regarding your repayment schedule like a hawk. You might find that some lenders allow for “skip-a-pay” options if an emergency arises, while others are as rigid as a board. Knowing how they handle your monthly payments can save you from significant stress down the road.
Make sure you identify exactly what the late fees look like and whether you will face a penalty for paying the balance off ahead of schedule. Understanding these specific nuances is your most effective shield. It prevents a short-term loan from morphing into a permanent financial burden that follows you for years.
