
Best Personal Loans for High Income Individuals: Compare Top Rates Today
Last updated: 2026-10-16
Securing immediate liquidity can feel like a uphill battle for those at the top of the food chain. Even with a towering income on your tax documents, many lenders struggle to wrap their heads around intricate cash flows or unique tax arrangements. It is a real headache.
It is not merely a quest for capital. Instead, you are searching for a collaborator who acknowledges your financial intelligence and values your precious time. You deserve a lender that treats your complex portfolio with the respect it warrants.
For elite professionals like specialized engineers, corporate leaders, or surgeons, rigid automated credit algorithms frequently miss the forest for the trees. These computer-driven models often overlook the true depth of your wealth. They are far too blunt an instrument for your situation.
Your actual net worth might be hidden within seasonal bonuses, stock options, or deferred compensation packages. These elements rarely translate well on a standard paycheck for a basic credit model. Consequently, you might face rejected applications or poor rates despite having substantial assets.
When selecting a provider, staring solely at the interest rate is a rookie mistake. You must weigh how fast the funds arrive against the fluidity of your repayment schedule. A clunky digital interface can also turn a smooth transaction into a nightmare.
If you are jumping on a private equity play or a real estate opportunity, you cannot afford to waste days uploading documents to a dinosaur bank. For high-asset individuals, excessive administrative friction is a total dealbreaker. Efficiency is your most valuable currency.
Our selection focuses on lenders that marry rapid capital deployment with an understanding of high-net-worth requirements. We have leaned heavily toward digital-first providers that won’t drag their feet. You need momentum, not a mountain of tedious paperwork.
We have curated a list of institutions that keep pace with your lifestyle. These are the companies designed to move as fast as you do.
- Discover
- Avant
- JetzLoan
- OneMain Financial
- LendingPoint
- Upgrade
Our Methodology for Rating Lenders
We tailored our assessment to meet the unique demands of individuals with substantial earnings. The primary goal was to find institutions capable of issuing substantial sums of money without demanding physical assets as security. Many executives prefer leveraging their projected income or existing wealth rather than tying up collateral.
Because of this, we hunted for companies that employ “soft pulls” during the preliminary screening phase. This specific feature is a breath of fresh air for anyone worried about their credit standing. It permits a quick glance at potential terms without causing any damage to your financial history.
Testing the speed at which money actually hits your bank account was also vital. In the high-stakes world of investing, timing is everything. A missed window on a real estate deal can be a costly mistake for even the most seasoned professional.
Consequently, we gave top marks to firms that provide lightning-fast capital deployment. We prioritized those offering funds within twenty-four hours, and even those that could deliver in just one hour. Speed is often the deciding factor when a sudden opportunity knocks on your door.
We also peeked under the hood of their digital application platforms to check for transparency. A lender that buries “origination fees” in the fine print of a massive document is a major red flag. People with busy schedules need clarity, not a scavenger hunt for hidden costs.
Finally, the sheer scalability of each loan product was a deciding factor in our review. Offering a measly $5,000 might help with a small fix, but it does nothing for someone aiming to consolidate major debt or fund a massive lifestyle change.
We steered clear of small-scale lenders in favor of those with significant ceilings. We looked for providers that routinely offer $30,000 or much more. Such high limits ensure the liquidity actually serves a purpose in complex, high-net-worth strategic financial planning.
Comparing Leading Borrowing Options
Selecting the right lender often feels like navigating a maze without a compass. You might find yourself weighing various pros and cons while trying to secure the best possible terms for your financial goals. It is not just about the money; it is about the speed and the fine print that governs your debt.
Some companies promise to deliver funds before the sun sets on your application, while others require a bit more patience. High earners typically prioritize efficiency, wanting to see that capital hit their accounts without any unnecessary delays or bureaucratic red tape getting in the way.
Before you sign any contracts, it is vital to look at how these institutions handle your credit history. A soft inquiry is a breeze, but a hard inquiry can feel like a punch to the gut if you are not prepared. Knowing which companies offer a “no impact” pre-qualification is a real game-changer.
| Financial Institution | Maximum Borrowing Limit | Time to Receive Funds | APR and Interest Details | Credit Score Effect |
|---|---|---|---|---|
| Discover | $40,000 | By the following business day | 6.99% – 24.99% | Pre-approval does not affect score |
| Avant | Consult website | Consult website | Consult website | Consult website |
| JetzLoan | $50,000 | A minimum of 24 hours | Consult website | No hard credit pull |
| OneMain Financial | $30,000 | Within a single hour | From 11.99% APR | Checking results in no impact |
| LendingPoint | $36,500 | Consult website | Consult website | Checking results in no impact |
| Upgrade | $50,000 | Rapid disbursement | Consult website | Checking results in no impact |
Top-Tier Lending Options for High-Income Earners
1. Discover
For those who find comfort in institutional giants, Discover is a rock-solid contender. Their personal loans offer a range of $2,500 to $40,000, providing a dependable bridge for your financial needs. There is a certain peace of mind that comes with knowing a massive, established entity is managing your debt.
If you are weary of trendy fintech startups that might vanish overnight, this brand offers the permanence of a legacy institution. It’s like having an old, reliable lighthouse in a sea of unpredictable digital players. Their structure provides a sense of security that many modern apps simply cannot replicate.
The digital experience is remarkably smooth, designed specifically for the person whose time is worth more than gold. You can perform a soft check for pre-approval to see your potential terms without bruising your credit score. It’s a low-stakes way to scout your options without any heavy lifting.
The interface is stripped of all the clutter, ensuring you don’t get lost in a maze of sub-menus. For a busy executive, this streamlined workflow is a luxury in itself. It gets the job done quickly so you can get back to your high-level priorities.
Pros:
- You could have your funds as early as the very next business day.
- They offer flexible timeframes and a zero-fee structure.
- Checking your pre-approval status leaves your credit score untouched.
Cons:
- Your borrowing limit is capped at a maximum of $40,000.
2. Avant
Avant caters to individuals who are constantly in motion, moving their finances toward new horizons. They provide a versatile toolkit of products, from specialized credit cards to loans intended for home upgrades or debt consolidation. This makes them a great fit for those whose financial profile is ever-evolving.
Consider a professional climbing the corporate ladder; your debt-to-income ratio might shift as you move from an associate to a partner. Avant understands these transitions. They offer a menu of solutions rather than a rigid, “one-size-fits-all” template that might leave you feeling boxed in.
The company prioritizes a user-centric approach, pairing digital ease with helpful support. Whether you need a quick fix for a sudden expense or a long-term plan to reorganize your liabilities, their tools help simplify the path. It’s about finding the right gear for your specific financial velocity.
Pros:
- Customizable loan options designed for various life situations.
- Digital tools that make financial oversight a breeze.
- Offers diverse strategies for managing existing debt.
Cons:
- Details regarding specific limits and terms are not always transparent.
3. JetzLoan
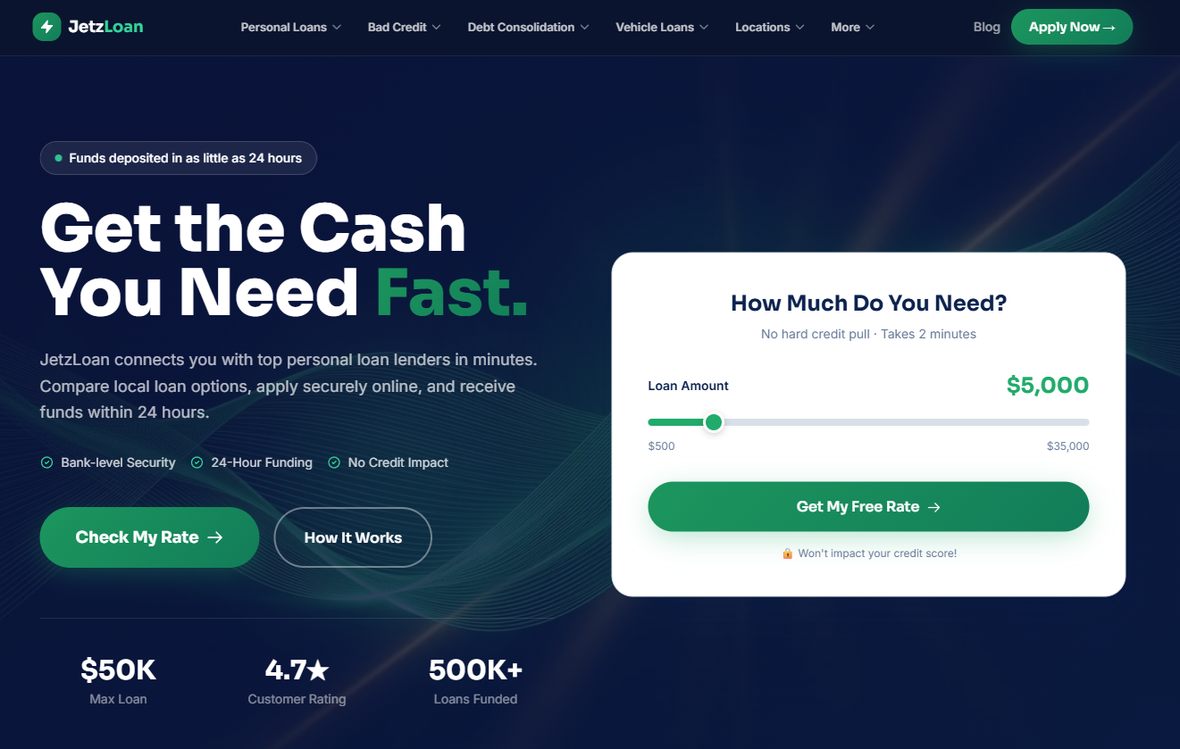
When time is the most expensive commodity, JetzLoan enters the ring as a high-speed contender. They act as a conduit, connecting you with premier lenders in mere minutes. You could potentially see funds land in your account in as little as twenty-four hours.
Traditional banking can often feel like wading through molasses when you are in a hurry. If a time-sensitive investment presents itself—like a high-stakes real estate auction—the velocity provided here becomes a massive competitive advantage. It’s built for the professional who needs capital yesterday.
Completing the initial application takes less than a two-minute sprint through a simple form. With a ceiling of $50,000, they handle significant needs without requiring a hard credit pull just to see your rates. It’s a clever way to survey the landscape without the usual administrative headache.
By utilizing this marketplace model, you can view a wide array of opportunities in one sitting. This saves you from the tedious chore of applying to multiple banks one by one. It’s a massive time-saver for the high-earning professional.
Pros:
- Lightning-fast funding, potentially arriving within a single day.
- Initial rate comparisons won’t harm your credit score.
- A substantial maximum borrowing limit of $50,000.
Cons:
- The service functions as a bridge to lenders rather than being the lender itself.
4. OneMain Financial
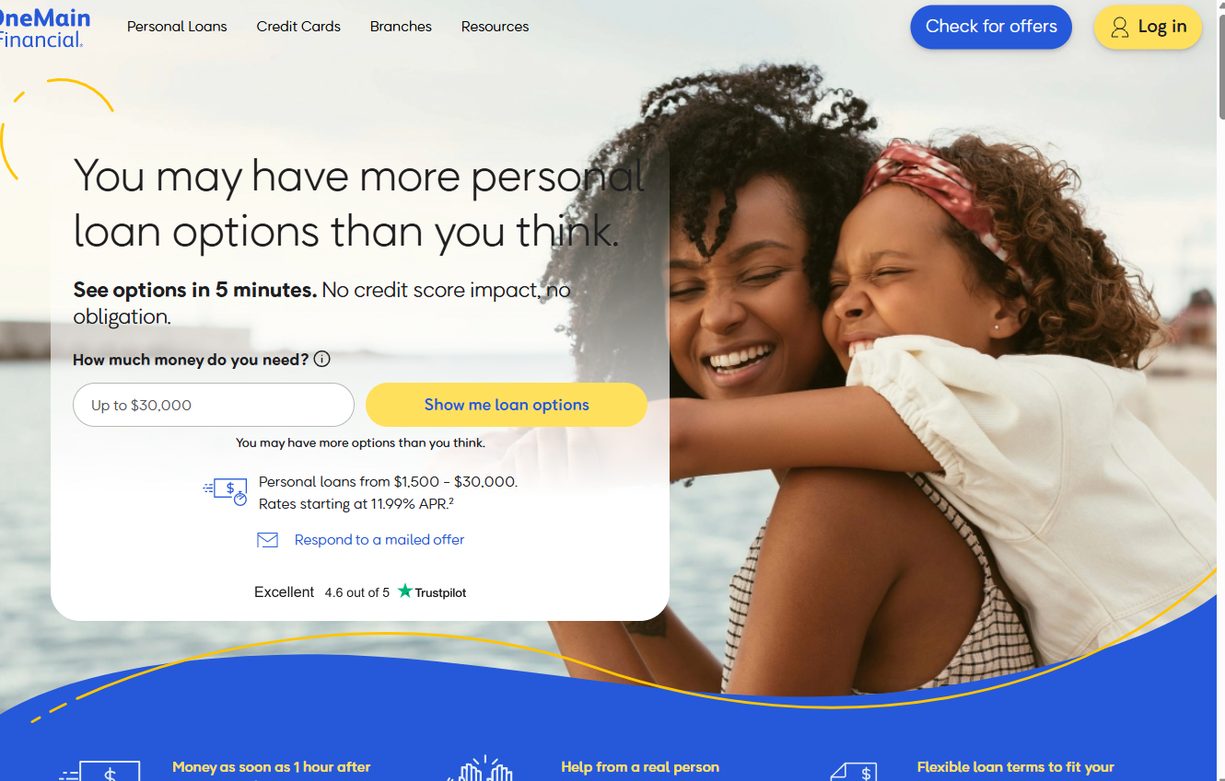
OneMain Financial serves those who want the best of both worlds: digital speed and human connection. Their personal loans range from $1,500 up to $30,000, with APRs starting at 11.99%. For urgent liquidity, the ability to receive money just one hour after signing is a game-changer.
In a market where unsecured loans are often slow, this level of urgency is a rarity. It makes them a premier choice for those facing unexpected emergencies. You get the efficiency of a modern app without losing the safety net of a physical presence.
With 1,300 branches available, you can always sit down with a real person if you prefer. This hybrid approach is perfect for high earners who want the convenience of a phone but the security of a face-to-face meeting. Sometimes, you just want to look someone in the eye when discussing complex money matters.
Having a physical office to visit can provide immense peace of mind. It is especially helpful if you need to iron out complicated repayment structures. A digital-only lender might reject a nuance that a human expert can navigate easily.
Pros:
- Rapid disbursement, sometimes in just sixty minutes.
- A massive network of branches for in-person assistance.
- Repayment windows ranging from 24 to 60 months.
Cons:
- Unsecured loan rates may exceed those of secured lending products.
5. LendingPoint
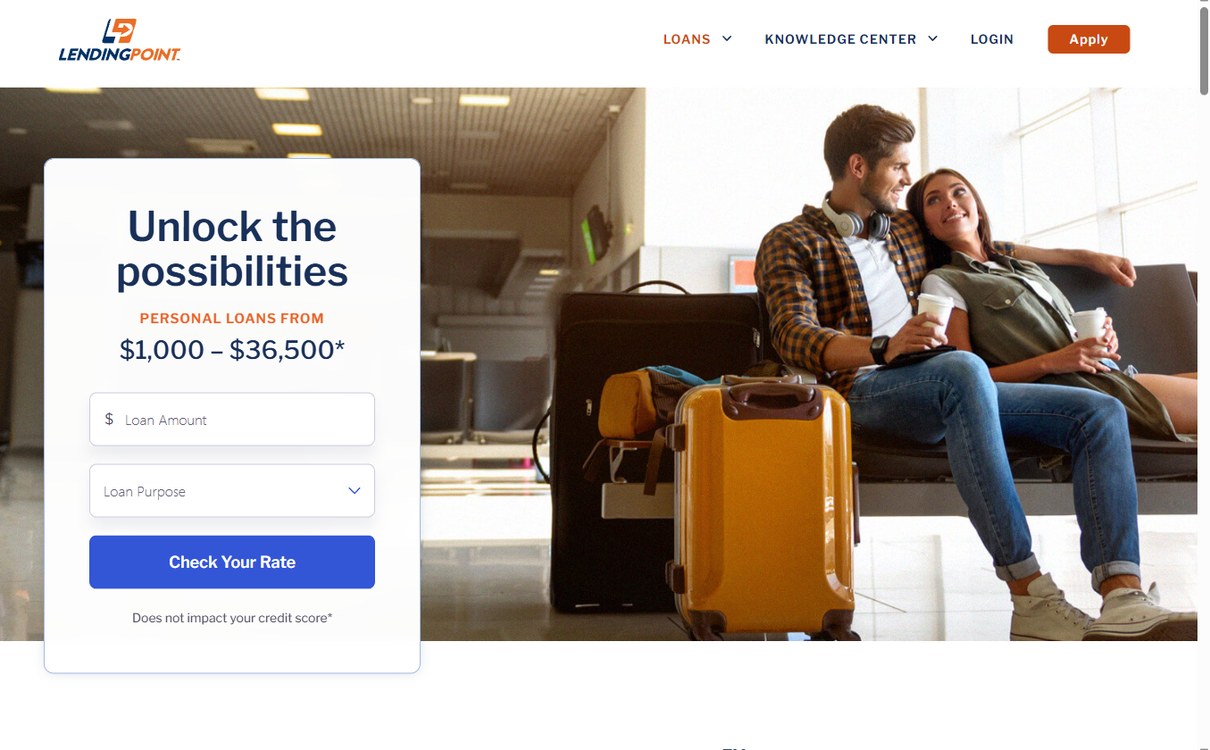
LendingPoint positions itself as a versatile tool for life’s various milestones, whether that is a wedding or medical bills. Their loan amounts fall between $1,000 and $36,500, hitting a sweet spot for those who need more than a tiny micro-loan. They provide a robust middle ground for significant expenses.
Their underwriting logic is built to be more sophisticated than your standard consumer lender. Instead of just glancing at a single number, they tend to view your broader financial health. It’s a more holistic way of looking at a professional’s creditworthiness.
The platform makes the “shopping around” process painless. You can check your specific rates without any impact on your credit score, which is a vital feature. This allows you to compare various offers with total freedom, ensuring you don’t pay more than necessary for your debt.
For high-earners managing multiple lines of credit, this “window shopping” capability is essential. You need to be surgical about which debt you take on and exactly what the cost will be. Precision in these matters can save a fortune over time.
Pros:
- Supports a diverse array of loan purposes.
- Rate checking is available without credit score penalties.
- Offers significant loan amounts up to $36,500.
Cons:
- The borrowing ceiling is lower than some specialized lenders.
6. Upgrade
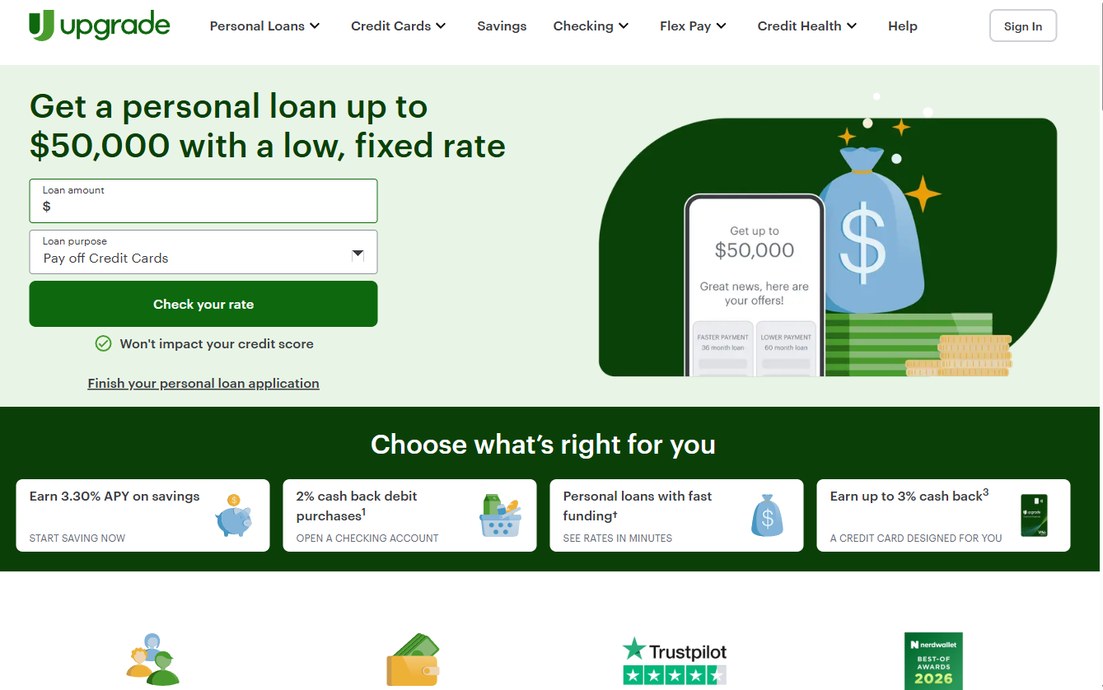
Upgrade acts as a comprehensive digital toolkit for the modern, high-earning consumer. They offer personal loans that reach up to $50,000, prioritizing speed and high-tech integration. You can often see your potential rates in just a few minutes.
It is a fantastic option for those who desire to manage their loans, checking, and savings in one unified ecosystem. Their approach focuses on reducing the “friction of friction,” effectively cutting out the unnecessary steps between your application and the actual disbursement of cash.
Their ecosystem is impressively robust, featuring cash back on various transactions and high APY on savings accounts. It is a “one-stop-shop” designed to appeal to those who crave efficiency. By centralizing your finances, you gain a clearer, real-time view of your total liquidity.
This bird’s-eye view of your cash flow is a vital component of sophisticated financial management. Instead of juggling five different apps, you have everything in one place. It turns a chaotic financial life into a streamlined, digital machine.
Pros:
- High borrowing limit of up to $50,000.
- A seamless ecosystem linking savings and checking.
- Quick rate checks that won’t touch your credit score.
Cons:
- The breadth of the ecosystem might feel complex to some users.
Leveraging Credit as a Wealth Management Catalyst
For individuals sitting in the upper echelons of earnings, a personal loan shouldn’t simply be categorized as a burden of debt. Instead, think of it as a sophisticated lever for moving capital around your portfolio. When you use these funds with precision, they act as a bridge toward lucrative ventures that might otherwise pass you by.
It is all about timing and the art of deployment. Rather than waiting for liquid cash to become available, a well-timed loan allows you to strike when the iron is hot. Consider these specific ways to put that capital to work effectively:
-
Capturing Arbitrage Spreads: Imagine a distressed real estate deal or a private equity play lands on your desk overnight. You might not want to wait for a bonus or a property sale to finalize. A loan provides the instant liquidity needed to lock in that deal, ensuring the potential profit far outweighs the interest cost.
-
Refining Cash Flow and Tax Timing: While you won’t get the same tax breaks on personal loan interest as you would with a mortgage, they remain powerful tools for managing liquidity. You might choose to finance a large purchase now to keep your own cash tucked away in high-yield vehicles, effectively deferring the use of your own capital.
-
Streamlining Existing Liabilities: Many high-net-worth individuals find themselves juggling several lines of credit and premium credit cards. By rolling these various debts into one low-interest personal loan, you simplify your monthly obligations. This consolidation reduces the sheer amount of interest bleeding out of your accounts over the long haul.
Steering Clear of Common Lending Traps
Even if you are pulling in a massive salary, it is remarkably easy to slip up and watch your net worth slowly bleed away. One frequent blunder involves obsessing over a small monthly bill while ignoring the actual price tag of the debt. When you are securing a $50,000 loan, a mere 2% discrepancy in interest can swallow thousands of dollars that should have stayed in your portfolio.
You must always scrutinize the APR instead of just looking at the monthly installment to grasp the real weight of your debt. This number is the ultimate truth-teller because it merges the interest rate with any compulsory fees. It paints the most honest portrait of what your borrowing will actually cost you in the long run.
Another blunder involves ignoring how fast the cash hits your account versus how much you actually need it right away. If a golden opportunity lands on your desk, a slightly higher interest rate might be a small price to pay for instant liquidity. Sometimes, speed is the secret sauce that turns a good deal into a great one.
Consider a scenario where a business venture demands a 24-hour turnaround to succeed. In that moment, a 12% loan that arrives in an hour is infinitely more precious than a 7% loan that sits in processing for ten days. On the other hand, if your goal is long-term debt consolidation, you should hunt down the lowest APR possible regardless of the wait.
Finally, you must read the fine print regarding prepayment penalties with a hawk’s eye. High earners often find themselves sitting on extra cash and may want to kill off a loan early to stop interest from accruing. If your lender hits you with a fee for early repayment, that “bargain” loan might end up being a total money pit.
Before you put pen to paper, don’t be afraid to ask the hard questions. Specifically, ask: “Is there a penalty for paying this loan off in full within the first twelve months?” For someone with fluctuating cash inflows, having that kind of freedom is a non-negotiable requirement for any smart lending partner.
