
Best Personal Loans for Low Income Individuals to Apply for Today
Last updated: 2026-10-16
Struggling to keep your head above water when every cent is spoken for is a heavy weight to carry. It feels like you are treading water in a storm, just trying to stay afloat. You might find yourself staring at an endless pile of invoices, searching for a helping hand that doesn’t demand a spotless credit history. This anxiety can be overwhelming.
Life has a knack for throwing curveballs exactly when you think you have things under control. One minute you are managing, and the next, an unexpected repair or a sudden doctor’s bill has turned your world upside down. Whether it is a broken car part or a spike in your heating bill, these surprises can wreck a budget in an instant.
When you are looking for a way out, ignore the shiny advertisements that promise the moon. Instead, you must dig into the gritty details of how quickly you get your funds and what the actual interest costs look like over the life of the loan. It is vital to know if looking for a quote will damage your credit rating.
The thin line between a useful financial lifeline and a crushing weight often depends on the Annual Percentage Rate (APR) and the specifics of your repayment schedule. Navigating these numbers is crucial for your long-term stability. Don’t let the marketing fluff distract you from what really matters: the actual cost of the money you borrow.
We have curated this selection to highlight lenders that actually look at people who are typically ignored by the major banking institutions. Our list covers a wide variety of financial needs. Some of these choices provide quick cash for emergencies, while others are designed to help you consolidate various debts into one manageable payment.
- JetzLoan
- Best Egg
- Avant
- OneMain Financial
- OppLoans
Our Vetting Standards
When we sat down to sort through these providers, our primary goal was to protect the person on the other side of the screen. We didn’t want to just list names; we wanted to see how these firms treat people facing a tight squeeze. It is a heavy responsibility to recommend financial help to those who need it most.
We dug deep into the ease of use for every platform. Speed is everything when the rent is due or a car needs fixing. We specifically hunted for services that offer lightning-fast determinations so you aren’t left hanging in uncertainty.
A major part of our investigation involved finding lenders that won’t ding your score just for checking your eligibility. There is nothing worse than getting a cold, automated rejection without any human interaction. We sought out companies that offer genuine clarity and real support.
Transparency shouldn’t be a rare find in the lending world; it should be the baseline. We scrutinized their fee breakdowns to ensure there were no hidden landmines waiting to trip you up. If a company hides its costs, it doesn’t pass our test.
We also weighed how different companies react to diverse credit histories. A one-size-fits-all approach rarely works for folks living on the edge. We needed to ensure these options were actually functional for a broad spectrum of financial backgrounds.
Timing is the heartbeat of our selection process. For anyone dancing from one paycheck to the next, a two-week wait is basically a lifetime. We leaned heavily toward providers capable of delivering cash within the same business day or within a twenty-four-hour window.
After all, financial aid is only useful if it hits your bank account when the emergency is actually happening. We prioritize those who treat your time with respect. Slow money often solves none of the problems it was intended to fix.
Finally, we looked closely at the “soft inquiry” mechanism. This clever feature lets you hunt for better deals without the sting of a hard credit inquiry. It is a vital tool for anyone trying to safeguard their credit standing while shopping around.
| Company | Borrowing Limits | Delivery Timeframe | Impact on Credit |
|---|---|---|---|
| JetzLoan | $500 – $35,000 | Minimum 24 hours | No hard credit pull |
| Best Egg | Up to $50,000 | See site | See site |
| Avant | See site | See site | See site |
| OneMain Financial | $1,500 – $30,000 | As little as 1 hour | No credit score impact |
| OppLoans | See site | Same-day funding available | Does not affect FICO score |
Leading Lenders Offering Accessible Credit Options
1. JetzLoan
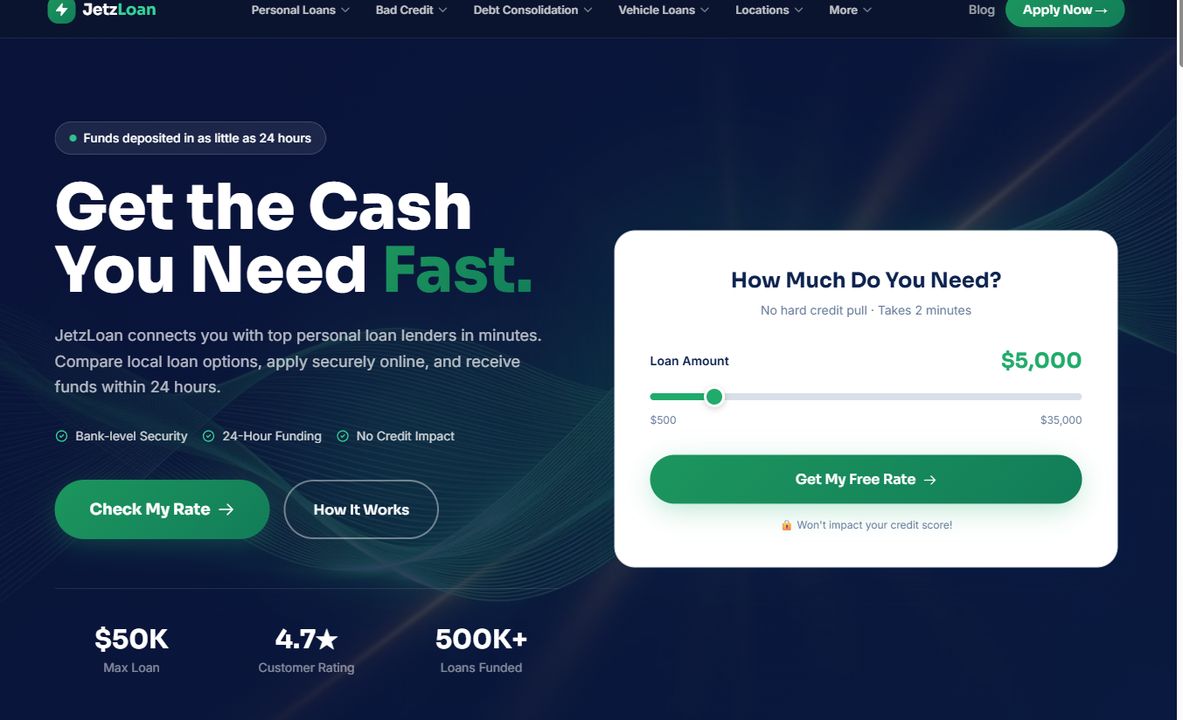
When time is of the essence, JetzLoan serves as a bridge between borrowers and a wide array of premier lenders. The system is engineered for lightning-fast simplicity. This makes it a top-tier remedy for anyone looking to roll multiple debts into one or cover a sudden vehicle expense. The entire path is smoothed out to ensure you aren’t drowning in paperwork.
They embrace a digital-first philosophy, which is a godsend for folks who cannot wait for the slow gears of traditional banking to turn. Because they offer a way to check your rates without a hard credit pull, the fear of a damaged score vanishes. This “pre-qualification” stage is a total game-changer for savvy shoppers. It lets you eye potential interest rates and terms before diving into a formal application.
In a crowded marketplace, this company has carved out a reputation for being a rock-solid partner. Boasting a 4.7-star rating and a history of funding over 500,000 loans, they truly know the ropes. It is a dependable route if you need to see your hard numbers before making a major financial leap.
Pros:
- Checking rates won’t impact your credit score
- Funds can arrive in as little as 24 hours
- Borrow up to $35,000
Cons:
- Loan amounts top out at $35,000
2. Best Egg
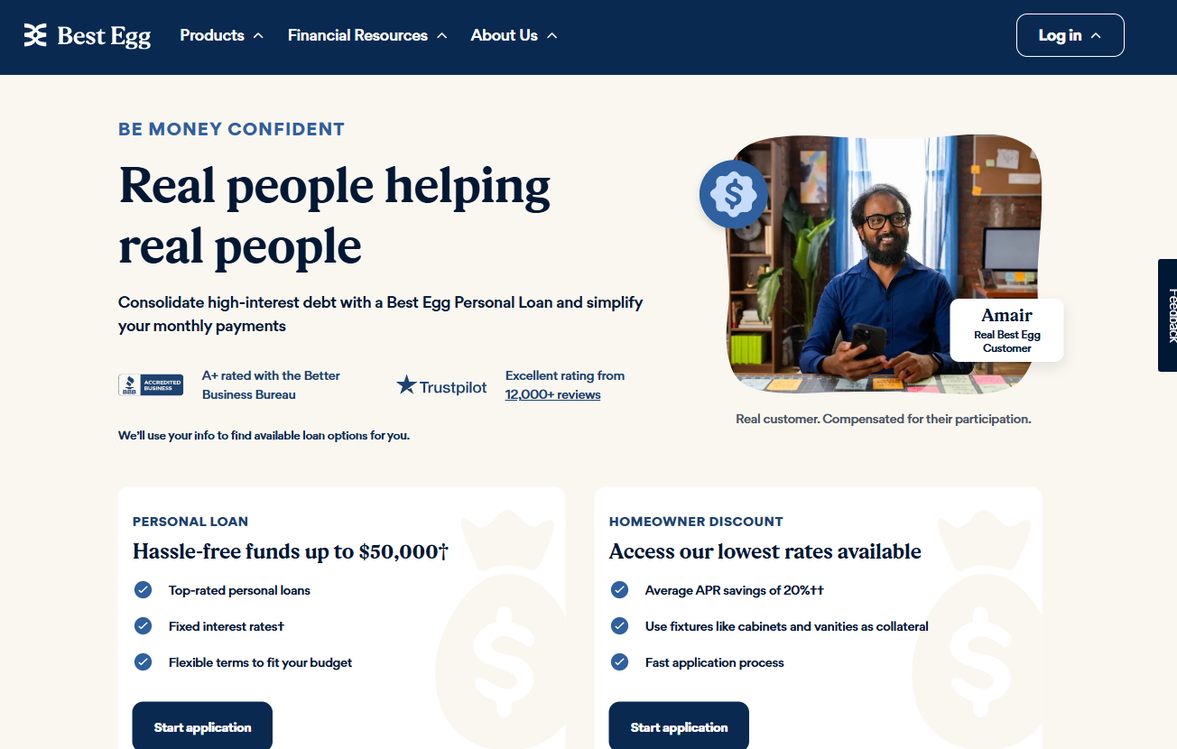
Best Egg acts as a heavy hitter in the personal loan arena. They are widely recognized for assisting individuals in tackling high-interest debt. Their primary mission is to simplify your financial life by streamlining your monthly obligations. Imagine taking a messy pile of medical debts or various credit card balances and turning them into a single, manageable payment. By consolidating, you can often snag a lower interest rate than your current cards allow.
This strategy can pave a clear road toward becoming debt-free while saving you serious cash over time. They have earned deep consumer trust, backed by an A+ rating from the Better Business Bureau and a mountain of positive testimonials. For those who own homes, there might be extra ways to lower rates by using assets like vanities or cabinets as collateral. However, the majority of clients stick to their standard unsecured loans.
This is a more methodical way to manage your money. It is perfect for individuals seeking a long-term strategy rather than just a temporary band-aid. If your goal is to get your finances organized and stay that way, this might be your best bet.
Pros:
- High borrowing ceilings reaching $50,000
- Outstanding BBB rating
- Potential savings for homeowners
Cons:
- The application process requires more detailed info
3. Avant
Avant operates on the belief that no two financial stories are exactly the same. They provide a toolkit of solutions, ranging from installment loans to credit cards. Their mission is to provide the wind in your sails as you move forward. Whether you are facing a sudden emergency or renovating your living space, they aim to offer choices that actually fit your unique lifestyle.
Unlike the rigid, robotic scoring used by many big banks, Avant takes a wider view of your overall financial health. They want to be a partner in your journey rather than just a lender. This provides a flexible cushion for people who might struggle with traditional banking hurdles. It is a versatile pick for those needing a specific tool, like debt consolidation, rather than a generic, one-size-fits-all product.
The platform is built for anyone seeking straight answers to tough financial questions. Their streamlined digital interface cuts through the thicket of paperwork usually found with personal loans. It is designed for the modern borrower who wants clarity and speed rather than endless, tedious forms.
Pros:
- A variety of credit card and loan options
- Tailored for different stages of life
- A philosophy of financial progress
Cons:
- Specific qualification rules aren’t always crystal clear
4. OneMain Financial
OneMain Financial is a premier choice for those who crave a human connection. With a massive network of over 1,300 branches, you can actually sit down and talk to a real person. This can be a total lifesaver when you are staring at confusing terms or dealing with a nuanced situation that a computer might miss. Having a physical storefront provides a sense of security for people who prefer face-to-face business.
Their speed is nothing short of impressive. You could potentially see your money just an hour after you sign the papers. They provide loans between $1,500 and $30,000 with the benefit of fixed monthly payments. This predictability is vital for families living on a tight budget, as it makes your monthly planning much easier.
It is a fantastic option if you need cash almost immediately to handle an urgent matter. If a car repair or a home maintenance issue pops up out of nowhere, having a local branch to visit can offer immense peace of mind. You can walk through the door, talk through your options, and get things moving quickly.
Pros:
- Huge network of physical branches for help
- Extremely rapid funding after signing
- Fixed payments lasting 24 to 60 months
Cons:
- Interest rates can fluctuate wildly
5. OppLoans
OppLoans is built on the principle that your credit score is not the whole story. Their lending partners look far beyond that single, lonely number. They take into account your income stability and your employment history instead. This makes them a viable lifeline for people who have faced a recent credit dip due to unexpected life events.
If life throws you a curveball like a medical emergency or a stint of unemployment, they may still be willing to work with you. It is a practical way to find relief without getting tangled in complicated fine print or hidden fees. The application is incredibly fast, and you often receive a decision within minutes. If approved, the cash might hit your account the very same business day.
This makes them a high-speed solution for emergencies where every second counts. Whether you are trying to keep the lights on or cover an immediate cost of living gap, they offer quick relief. Their commitment to fee transparency ensures you won’t be blindsided by the total cost of your loan.
Pros:
- Possibility of same-day funding
- Applying does not impact your FICO score
- Total lack of hidden fees
Cons:
- Might not be the best fit for long-term debt
Calculating Your Real Debt Burden
When life throws a curveball and money is tight, our eyes tend to fixate on the immediate cash availability. We often gloss over the interest percentage in our hurry to get things sorted. Yet, that tiny number carries the weight of your entire financial future. It is the heartbeat of your agreement.
It is vital to separate the base interest rate from the Annual Percentage Rate, or APR. While the interest rate is just the cost of the money itself, the APR tells the whole story. This figure absorbs everything, including pesky administrative charges or mandatory processing costs. Think of it as the true price tag.
Let’s say you need a $2,000 loan and see a 10% interest rate. If the lender sneaks in a $300 origination fee, your APR will jump much higher than that initial 10% suggests. Always look past the surface. The fine print is where the real costs like to hide from unsuspecting borrowers.
The Math Behind the Money
Before you put pen to paper, run a quick “monthly impact test” to see how this affects your wallet. This little mental exercise acts as a safety net. Take your scheduled monthly installment and multiply that amount by the total number of months in your repayment period.
Next, take that final sum and subtract the original principal you actually received. This simple subtraction reveals the true price of your convenience in cold, hard cash. It transforms abstract percentages into a real number that fits into your grocery or rent budget.
If a $2,000 emergency repair ends up costing you $600 in interest over time, you need to stop and think. Ask yourself if your monthly paycheck can handle that extra dent without breaking. Avoid the dreaded “debt trap” where you’re essentially running on a treadmill just to stay in place.
If you spend your whole paycheck just covering interest, you’re never actually paying down what you owe. You’ll find yourself spinning your wheels while the debt stays stubbornly high. Staying ahead of these calculations ensures you stay in control of your finances rather than the lender.
Navigating Potential Financial Traps
It is incredibly easy to let greed or desperation drive a wedge between your current reality and your future stability. Many people find themselves reaching for the highest ceiling a lender offers, even when their actual need is quite modest. For example, you might find yourself signing for $5,000 when a $3,500 loan would have solved your problem perfectly fine.
This extra cash might feel like a windfall at first, but it carries a hidden sting. Every additional dollar you borrow increases the weight of your monthly installment. If your paycheck varies from week to week, these higher costs can quickly turn into an anchor that drags you under a mountain of interest.
Before you sign any paperwork, try to cultivate a little breathing room in your existing monthly spending plan. Life rarely goes according to script; a sudden car repair or a spike in utility costs can throw everything off balance. You never want to find yourself choosing between servicing a debt and keeping the lights on.
Managing Credit Inquiries and Debt Cycles
Understanding how lenders peek at your financial history is vital to maintaining a healthy profile. Most companies allow you to shop around using a “soft pull,” which is a gentle way to gauge your interest rates without causing any damage to your standing. It is like window shopping at a boutique without actually taking anything to the register.
However, once you decide to move forward and officially accept the funds, the lender will perform a “hard inquiry.” This is a formal interrogation of your credit history that can cause your score to take a temporary tumble. Think of it as a commitment; make sure you are truly comfortable with the fine print before you cross that line.
Furthermore, steer clear of the dangerous habit of “rolling over” your short-term obligations into fresh, new loans. This maneuver is a classic trap that turns tiny, manageable debts into massive, crushing financial burdens. It creates a deceptive sense of stability that masks a much larger problem.
It might feel like you are simply treading water during a storm, but you are actually sinking just at a slower pace. Instead of moving forward, you are merely paying for the privilege of staying in the same precarious position. True financial freedom requires facing the debt, not just rescheduling it indefinitely.
