
Top-Rated Providers for Bad Credit Loans Louisiana to Secure Fast Cash
Last updated: 2026-10-16
Navigating your personal finances in Louisiana often feels as murky as a swamp during a heavy downpour. Many residents find that their credit ratings fail to reflect their true character or their genuine capacity for repayment. When a sudden engine failure or an unforeseen hospital invoice pops up, you crave clarity rather than more chaos.
From the bustling sidewalks of New Orleans to the tranquil parishes deeper in the state, financial stress is a common thread for many industrious Louisianans. Identifying a creditor that recognizes the nuances of a low credit score is your first step toward stability. This compilation examines various options, ranging from neighborhood credit unions to modern online platforms.
Every financial provider offers a distinct path forward. You might be hunting for a quick bridge to cover monthly expenses, or perhaps you want to merge various debts into one manageable payment. Making the smartest decision involves looking much deeper than the surface-level interest rate. You must scrutinize the specific contract details, the rules, and the various installment timelines.
- FastLendGo
- Coastline Credit Union
- LightStream
- United Finance
- Addition Fi
- GadCapital
The Criteria for Loan Approval in Louisiana
Hunting for a loan in the Pelican State is more like navigating a maze than a simple sprint. You shouldn’t just pick the first person to shout “yes.” Instead, many local institutions dig into the meat of your finances, specifically checking if your paycheck is reliable and how your monthly debts compare to what you earn.
While your credit score is definitely a piece of the puzzle, it isn’t the whole picture. Many providers focus on your employment history to ensure you can actually settle the debt. They want to see that you have the muscle to pay them back over time.
Think of it like a teacher looking at a student’s entire year rather than one bad test grade. For example, presenting bank records from the previous ninety days can prove your income is stable. This often outweighs a temporary FICO score drop caused by an unexpected hospital visit.
Timing is everything when life throws a curveball. If your vehicle’s transmission gives out on a Friday afternoon, waiting two weeks for an answer feels like an eternity. When you need to be back on the road by Monday morning, speed becomes your most important metric.
We evaluated these different services by looking at how easy they are for folks with bruised credit to access. We also weighed their maximum loan limits against the velocity of their payout process. It is vital to scrutinize the “Total Cost of Borrowing” before signing any paperwork.
Don’t let sneaky numbers catch you off guard. You need to account for the APR along with any hidden administrative charges or origination fees. Everything adds up when the final settlement comes due, so look at the full price tag, not just the monthly payment.
| Company | Borrowing Range | APR % | Payout Timing | Eligibility |
|---|---|---|---|---|
| FastLendGo | $500 – $5,000+ | see site | see site | Bad/Fair Credit |
| Coastline Credit Union | see site | see site | see site | see site |
| LightStream | see site | 9.99% – 24.94% APR | Next day | Excellent Credit |
| United Finance | Up to $20,000 | see site | see site | see site |
| Addition Fi | see site | see site | see site | see site |
| GadCapital | $100 – $5,000+ | see site | Instant | No Credit Check |
Premier Lending Solutions Across Louisiana
1. FastLendGo
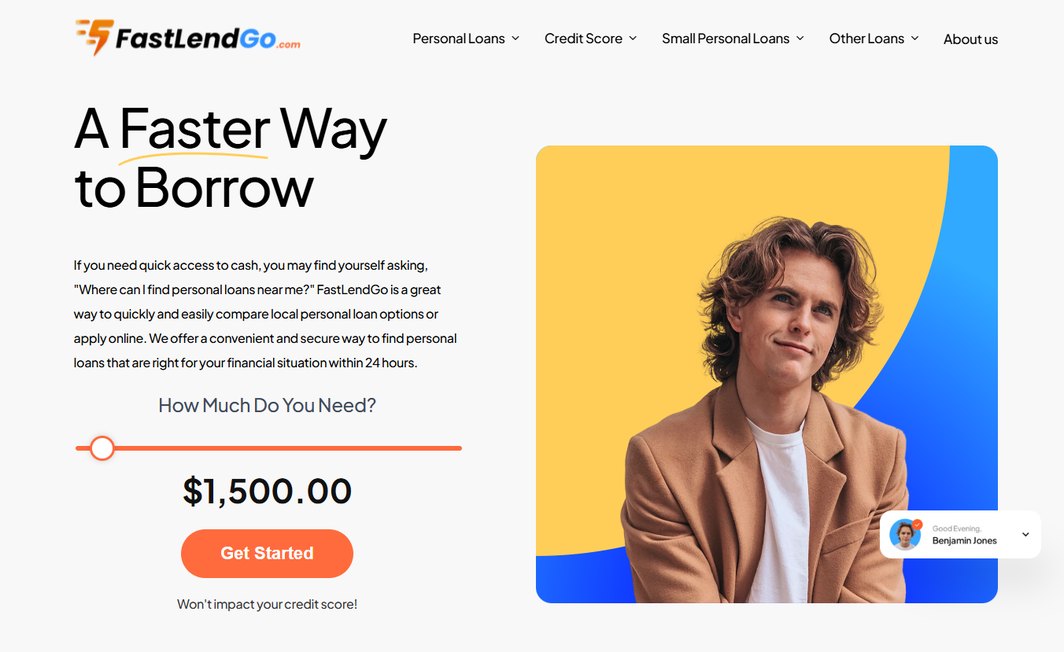
Sometimes, the big-name banks can feel like a brick wall when your credit score isn’t quite where you want it to be. FastLendGo acts as a bridge for those navigating similar hurdles. They focus heavily on personal financing options tailored specifically for individuals with less-than-perfect credit history.
Instead of making you hop through hoops or drive across several different parishes, this platform brings the market to your screen. You can weigh your different choices without ever leaving your sofa. It is a digital-first way to shop for cash through fastlendgo.com.
Whether you are staring down an unexpected dental bill or a sudden leak in your roof, their specialized loan types can help. They cater to various needs, covering anything from a quick $500 fix to larger requests reaching $5,000. It is a lifesaver for those caught in the pinch between a sudden crisis and a future paycheck.
Pros:- Expertise in managing fair and poor credit scenarios.
- Provides specific funding for medical or car repairs.
- Streamlined comparison tool for web users.
- Does not offer the cozy, small-town feeling of a local credit union.
2. Coastline Credit Union
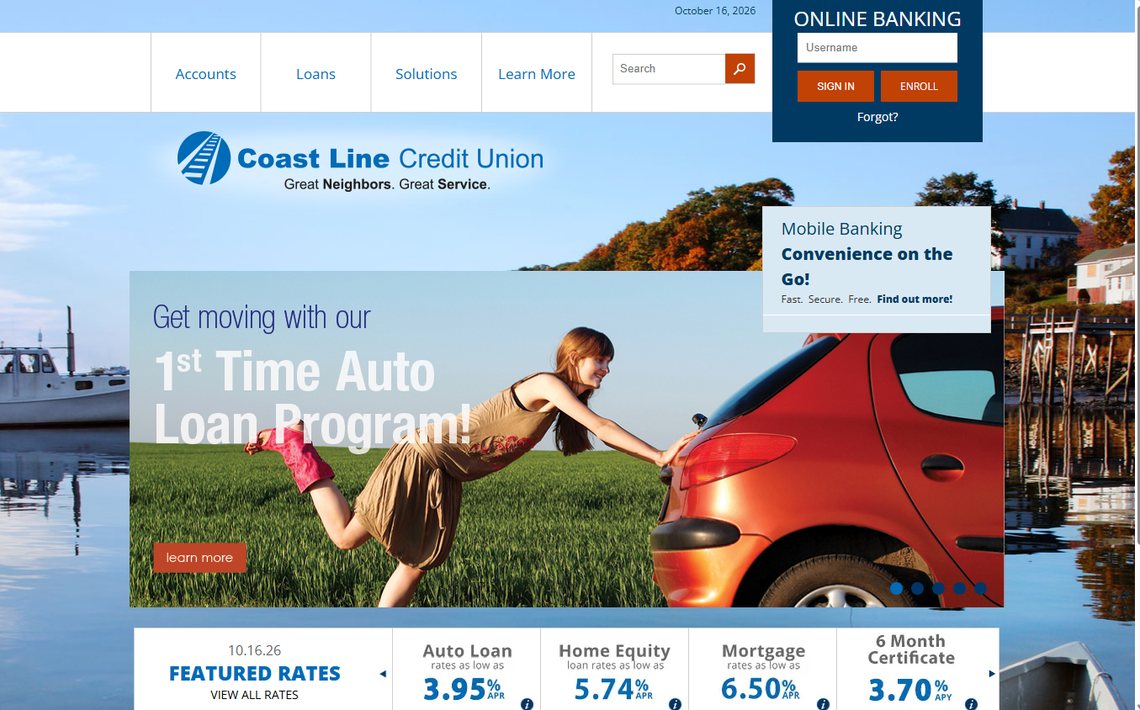
In the vast ocean of finance, credit unions are the quiet, reliable anchors. Coastline Credit Union provides a banking atmosphere that feels much more like a handshake from a neighbor. If you find the massive, faceless corporations a bit cold, this organization might be your perfect match.
Because they operate as member-owned cooperatives, their primary mission isn’t about padding the pockets of distant shareholders. Instead, they prioritize serving the people who use their services. This unique structure frequently results in more accommodating and flexible terms for the members who call them home.
They offer a robust menu of products, ranging from standard loans to modern digital banking. While their entry requirements might be slightly more rigorous than a quick-cash lender, the long-term payoff is significant. Building a history with them can pave a smooth road toward securing a mortgage or an auto loan down the line.
Pros:- A business model built around member welfare.
- Convenient tools via mobile and web banking.
- Potential for superior long-term interest rates.
- Eligibility for membership is typically required.
3. LightStream
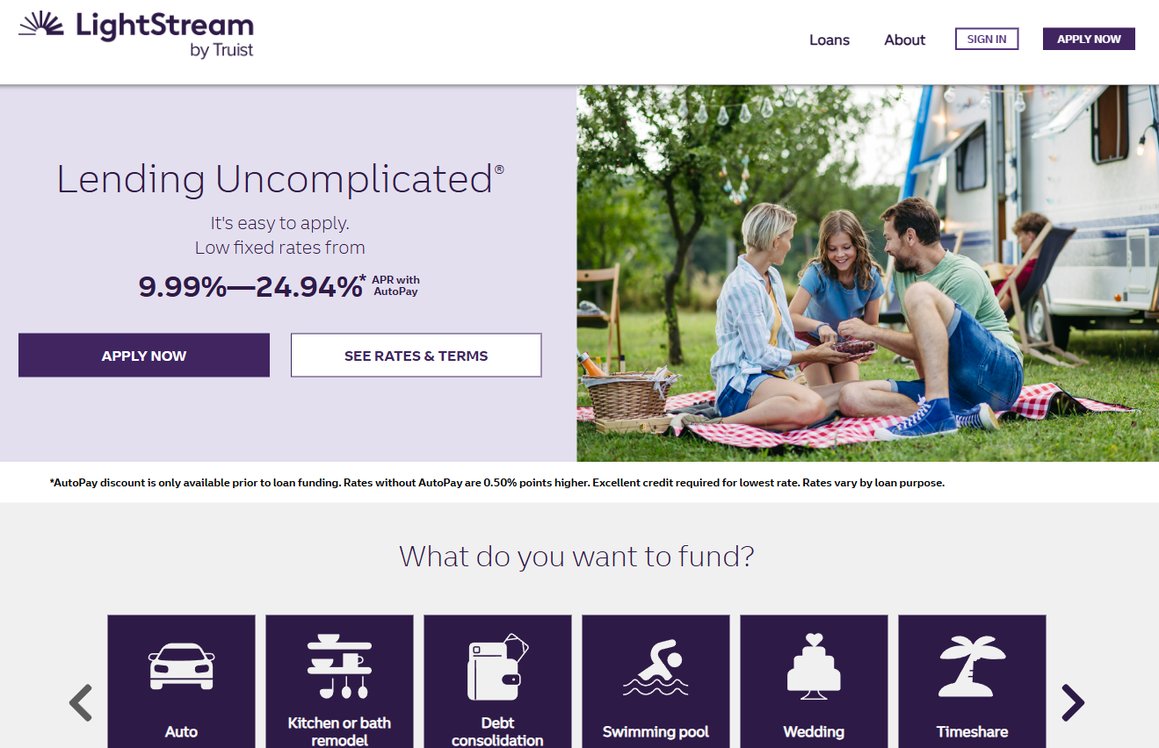
If your credit score is currently in the top tier, LightStream is a heavy hitter. They aren’t exactly the safety net you’d look for if you are currently sinking in debt. However, for those with a pristine financial reputation, they offer something quite special.
Their application journey is remarkably swift, ensuring they don’t waste a moment of your day. This makes them an excellent companion for major life milestones. When you’re planning something big, saving a chunk of change on interest can mean a massive difference in your overall budget.
The versatility of their platform is impressive, whether you’re remodeling your kitchen or celebrating a wedding. The speed of their funding is a standout feature, with many people seeing the cash in their accounts by the very next day. They are also a top choice for anyone looking to roll high-interest credit card debt into one manageable payment.
Pros:- Lightning-fast funding, often arriving within 24 hours.
- Competitive fixed rates with added discounts for AutoPay.
- Wide variety of approved uses for the funds.
- Only accessible to those with top-tier credit scores.
- Not a viable option for borrowers with poor credit.
4. United Finance
United Finance is a true veteran of the lending industry, boasting a history that dates back to 1922. In an era of fleeting fintech apps, they offer a sense of permanence and stability. They provide both auto and personal loans that are designed to play well with a realistic monthly budget.
Having weathered everything from the Great Depression to the rise of the internet, their longevity speaks volumes. They have mastered the art of staying steady through every economic storm. Their approach is centered on making the borrowing process straightforward and highly accessible for everyone.
When you work with them, you aren’t just a number; you get a dedicated team of friendly lenders to guide your way. This human touch is a godsend if you find online forms overwhelming. It is particularly beneficial for self-employed individuals or those with complex income streams that might get lost in an automated system.
Pros:- Massive institutional experience and proven stability.
- Personal loan amounts can reach up to $20,000.
- Provides both refinancing and auto loan options.
- A more traditional workflow might be slower than digital-only apps.
5. Addition Fi
Addition Financial focuses on empowering its members to expand their personal wealth while managing daily life. Rather than being just another place to borrow, they function as a holistic financial partner. They aim to be your one-stop shop for all things monetary.
From the day-to-day utility of checking accounts to the complexities of investment options, they cover it all. Having your entire financial ecosystem in one single place makes tracking your savings and spending habits much simpler. It takes the guesswork out of your monthly financial overview.
They offer very competitive rates and champion a community-centric way of banking. If you are looking to step away from the big national banks toward something more personal, Addition Fi provides the necessary toolkit. They support you through every season, from your very first car loan to your eventual retirement planning.
Pros:- An all-in-one suite of investment and banking tools.
- Community-focused referral incentives.
- Strongly competitive rates across many products.
- Full access to benefits requires membership.
6. GadCapital
When you find yourself in a tight spot and the clock is ticking, GadCapital acts as that “break glass in case of emergency” tool. They specialize in quick-turnaround installment and payday loans for people facing credit challenges. They are designed for rapid deployment when traditional banks simply say “no.”
This is a highly specialized service for moments of extreme urgency. If a standard three-day waiting period for approval feels like an eternity, GadCapital is built for this specific pressure. They handle the high-stress moments when you just need immediate relief.
Their platform allows for very small, rapid loans, starting at the $100 mark. If you are facing a utility shut-off or an urgent medical co-pay, they are built to assist without a long-winded credit check. However, you must be incredibly disciplined with your repayments to avoid getting trapped in a high-interest cycle.
Pros:- Certain loan types require no credit checks.
- Provides nearly instant access to cash.
- Loan amounts range from $100 to over $5,000.
- Payday-style structures often carry very high costs.
- Potential to enter a debt cycle without careful management.
Calculating Your Actual Debt Expense
It is incredibly easy to get blinded by a low monthly installment figure when you are in a pinch. You might see a $500 loan and a $50 monthly bill and think you have struck gold. However, math has a way of biting back when you aren’t looking.
If those $50 payments stretch across a full year, you end up shelling out $600 total. That extra $100 represents a 20% markup on the original amount you borrowed. It is like buying a steak but finding out you have to pay for the plate, the silverware, and the waiter’s tip too.
Before you put pen to paper, demand to see the “Total Repayment Amount” from your lender. This specific number acts as your financial North Star. It reveals the exact amount of hard-earned cash that will have vanished from your bank account by the time you are officially debt-free.
Don’t let the “nominal interest rate” fool you into a false sense of security. This number is often a sleight of hand used by lenders to make deals look sweeter than they actually are. It ignores the hidden sting in the tail of the contract.
You need to focus your attention on the Annual Percentage Rate, commonly known as the APR. This figure is much more honest because it wraps the interest rate and various administrative costs into one single number. It accounts for those pesky processing or origination fees that sneak in during the application phase.
When you are shopping around between different lenders, let the APR be your ultimate guide. A provider might promise a lower interest rate but bury you in upfront service charges. Always choose the option with the lowest APR, as it represents the most truthful cost of your borrowed capital.
How to Get Ready for Your Loan Request
Navigating the path to approval doesn’t have to be a headache if you play your cards right. Think of it as setting the stage before the curtain rises on your application.
By taking a few proactive steps, you can significantly boost your odds of landing a favorable rate. It is much better to walk in prepared than to stumble through the process blindfolded.
Follow these three essential habits to ensure your submission is as strong as possible:
- Review Your Paperwork: Start by rounding up your latest W-2 forms, pay stubs, and even basic utility statements. Lenders need solid evidence regarding your living situation and steady earnings to feel confident in your profile.
Having these items organized and ready for a quick upload can turn a multi-day waiting period into a mere matter of minutes.
- Scrutinize Your Credit Profile: Utilize complimentary resources like AnnualCreditReport.com to peek inside your file. If you spot a mistake—like an old, settled debt still appearing as unpaid—don’t just sit there; dispute it right away.
A tiny inaccuracy can be the bridge between a 650 score and a 620 score, so precision is your best friend here.
- Determine Your DTI Percentage: Sum up every monthly debt you owe, including car loans, rent, and minimum credit card payments. Then, divide that total by your overall gross monthly income to find your Debt-to-Income (DTI) ratio.
Keep in mind that most lenders prefer to see a DTI falling somewhere between 36-43%. Knowing this specific figure helps you gauge exactly how much extra borrowing you can actually handle without drowning in interest.
Steering Through the Lending Landscape
Before putting pen to paper, pause and scrutinize the small text. It is incredibly tempting to dive headfirst into an immediate approval, yet the real story lies in the cumulative expense of the debt. Do not merely focus on what you owe each month; instead, dissect the APR to grasp the actual price of your borrowed funds.
Mistakenly disregarding the fallout from tardy installments is a frequent stumble. Even when a company accepts your poor credit score, missing a deadline is like a pebble in your boot, creating discomfort for a long duration. You must guarantee that every installment fits snugly into your current financial plan, allowing enough leftover cash for basic necessities like food and housing.
Maintaining a “safety net” within your monthly spending is your primary shield against unexpected life events. Without this cushion, you might find yourself back in the deep end when a car repair or medical bill arrives. Financial stability requires a bit of breathing room to avoid a downward spiral.
Beware the siren song of the “instant solution.” While rapid options, such as payday loans provided by GadCapital, can pull you from a sudden crisis, they often snowball into a massive debt mountain if handled recklessly. Treat these funds as a last resort, reserved only for genuine emergencies that cannot wait.
Whenever possible, aim for more permanent financial structures like credit unions or personal loans from reputable organizations. Relying on short-term fixes is a band-aid on a much larger wound. Instead, focus on the long game by consistently meeting your deadlines to repair your standing.
Cultivating a track record of punctual repayments remains your most powerful tool for escaping a credit deficit. It is the most reliable ladder to reach a state of enduring fiscal independence. Patience and discipline are your best allies in this marathon.
