
Best Ways to Secure Loans for Postal Employees with Bad Credit Today
Last updated: 2026-10-17
Navigating your personal finances while grinding through grueling mail delivery shifts often feels like wading through heavy sludge. Sometimes, life hits you with a sudden punch that your regular salary simply cannot blunt. Whether it is a sudden mechanic’s bill or a surprise hospital invoice, many postal workers find themselves in a pinch that standard banks are all too eager to ignore.
Trying to balance the physical exhaustion of the route with the mental weight of mounting bills can make any obstacle seem like a mountain. When your credit rating takes a hit, the road to securing capital starts feeling like a labyrinth. You aren’t just hunting for a quick fix; you are searching for a lender that appreciates the inherent security of a government job.
A big-name bank might look at a temporary dip in your FICO score and simply slam the door. Specialized lenders, however, see past the numbers to the steady reliability of your federal wages. This evaluation examines how various lenders assist those needing a lift, prioritizing ease of use, rapid funding, and genuine empathy for your unique financial landscape.
Our analysis breaks down the leading options for 2026, specifically tailored to your needs.
- USPS Federal Credit Union
- Federal Employee Loans
- JetzLoan
- BMG Money
- Acorn Finance
- Credit Ninja
Our Criteria for Selecting Lenders
Hunting for a trustworthy money source involves more than just chasing flashy web banners or those tempting “get approved instantly” slogans. We decided to dig much deeper than the surface level. Our team aimed to see how these companies actually handle the unique financial life of a mail carrier.
Instead of obsessing over a perfect FICO, we examined if these lenders respect the ironclad security of a government-issued paycheck. We specifically sought out institutions that value payroll allotments as a way to offset risk. For many in the postal service, a steady federal salary matters far more than a damaged credit report.
We also had to strike a delicate balance between the speed of the cash and the long-term cost. When a delivery truck breaks down unexpectedly, you need help fast. A provider that can wire funds within a single day acts as a vital safety net during those sudden, stressful emergencies.
Yet, a quick fix can turn into a financial anchor if the interest rates are predatory. We carefully vetted the borrowing limits, how much wiggle room exists in repayment, and the impact of the application itself. We hunted for “soft pull” mechanisms that let you check your eligibility without harming your score.
| Company | Borrowing Limits | Timeframes | Payout Pace | Eligibility Standards |
|---|---|---|---|---|
| USPS Federal Credit Union | To $15,000 | Check website | Check website | Check website |
| Federal Employee Loans | $500 to $3,000 | 6 – 12 months | Within the day | No FICO check |
| JetzLoan | Up to $35,000 | Check website | In under 24 hours | No hard pull |
| BMG Money | $500 – $12,000 | 6 – 48 months | Immediate access | Regardless of score |
| Acorn Finance | Check website | Check website | Check website | No score impact |
| Credit Ninja | Check website | Check website | Decision within one day | Check website |
Top-Rated Lending Options for Postal Staff
1. USPS Federal Credit Union
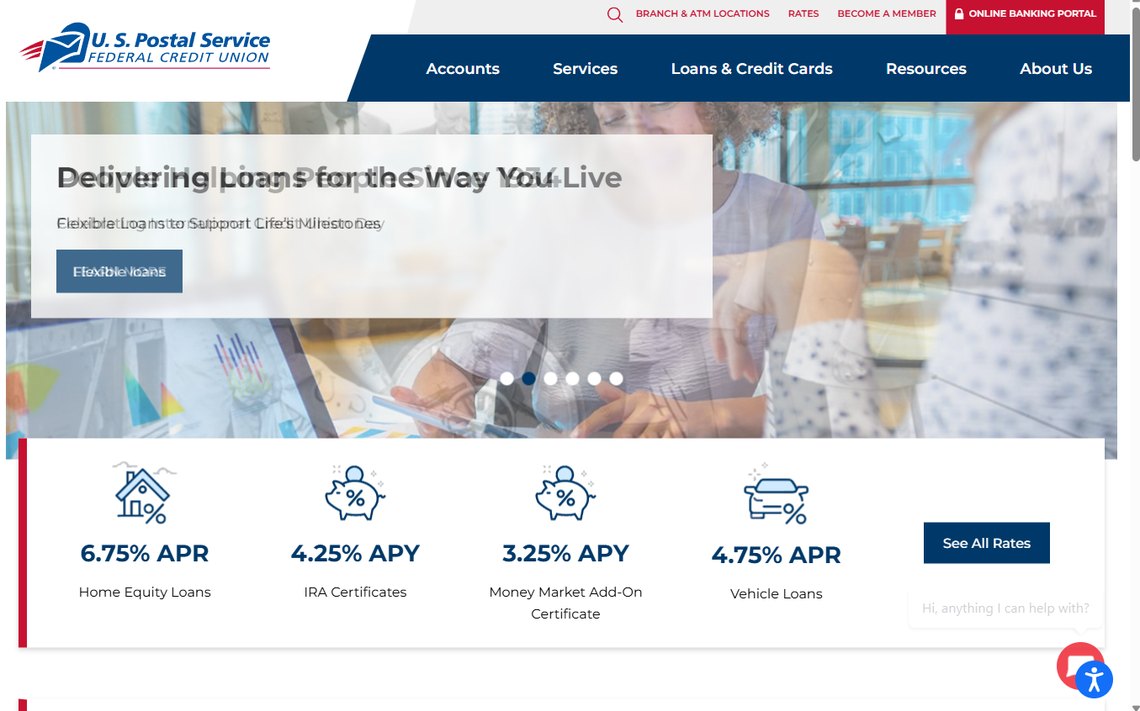
Since 1934, this organization has functioned on the principle of community solidarity. For anyone working in the postal service, there is a unique comfort in banking with a group that understands your specific professional background. It offers a sense of kinship that a cold, massive national bank can’t quite match.
Because these are nonprofit, member-owned cooperatives, their mission is to serve you rather than enrich distant shareholders. They provide various financial tools, including personal loans that can reach up to $15,000. These can help you navigate life’s twists, whether you are merging several expensive credit card balances or managing an unplanned relocation.
They truly grasp the intricacies of federal pay structures, such as seniority-based raises and regular adjustments. Because of this, their loan products feel custom-built for the lifestyle of a dedicated carrier or clerk. When you walk in, you aren’t just another number; you are a vital part of their legacy.
Pros:
- Built specifically for USPS staff
- Personal loans up to $15,000
- Versatile terms for life’s changes
Cons:
- Eligibility requirements or membership may apply
2. Federal Employee Loans
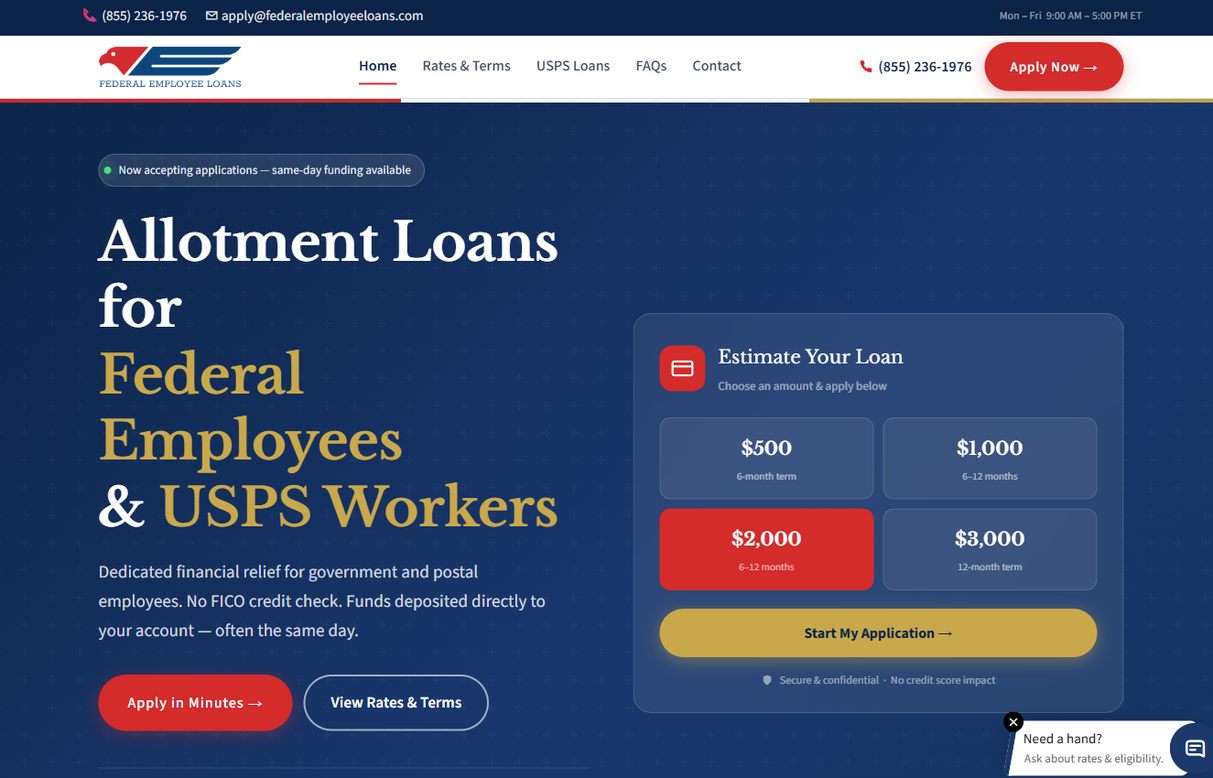
You might not need a massive lump sum; sometimes, you just need a way to bridge the gap until your next paycheck arrives. This lender focuses on allotment loans, which are tailored specifically for those in the USPS and government sectors. This method allows a portion of your earnings to be sent directly to the lender for repayment.
This setup offers a level of assurance to the lender, which enables them to provide much more forgiving terms to you. It is a straightforward path for anyone needing a quick financial fix without the usual headache of intense underwriting. The sheer simplicity of this method is its greatest strength.
They don’t fixate on your FICO score; instead, they look at your federal employment status and your steady income shown on pay stubs. If you need a small amount to cover groceries or fuel, this is a remarkably efficient route. It’s like a helpful, silent nod from a trusted coworker in the sorting facility.
Pros:
- No need for FICO credit checks
- Get funds the same day for rapid help
- Small, easy-to-manage loan amounts
Cons:
- Lower borrowing ceilings than other lenders
3. JetzLoan
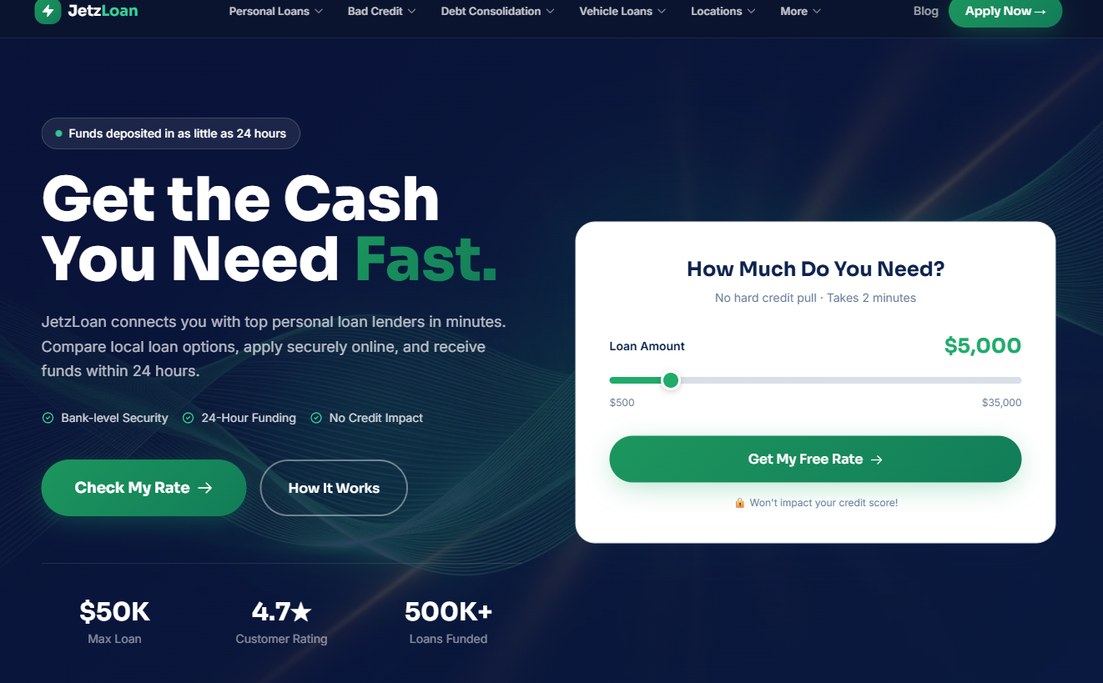
In a modern age where speed is everything, waiting weeks for a loan feels like a relic of a bygone era. JetzLoan prioritizes velocity, working to ensure money hits your bank account within a single day. This is perfect for those facing an immediate crisis, like a broken washing machine or a sudden house repair.
They act as a vital middleman, introducing you to several different lenders so you can compare deals without hurting your credit score. This marketplace approach is a real game-changer. Rather than hitting ten different banks and triggering ten separate “hard pulls” on your report, JetzLoan lets you check eligibility with just one inquiry.
This is a contemporary solution for anyone wanting to see their true options without the anxiety of guessing at interest rates. You get to face the reality of your financial choices without the stress of endless, repetitive applications.
Pros:
- Money can arrive in as little as 24 hours
- Checking rates won’t trigger a hard credit pull
- Maximum loan limits reaching $35,000
Cons:
- Functions as a marketplace, not a direct lender
4. BMG Money
Your worth is much more than a single digit on a credit report. BMG Money operates on the belief that a score doesn’t define your whole potential. They focus on employees and retirees working toward financial stability who need help right this moment. They understand that a credit score is just a look back at the past, while your current job and future salary are much better indicators of your reliability.
Their loan amounts are quite flexible, spanning from $500 up to $12,000. This makes them useful for everything from small home fixes to majorly tackling debt. For instance, instead of paying high interest on various retail cards, you could use a BMG Money loan to merge those debts into one single, manageable payment.
Their goal is to act as a partner in your journey toward better health in your finances. It is a very practical way to tidy up your debt with a more reasonable interest rate and a single monthly due date.
Pros:
- Open to everyone regardless of credit history
- Options for instant funding are available
- Flexible repayment terms up to 48 months
Cons:
- Some borrowers may face higher interest rates
5. Acorn Finance
If your money troubles are specifically about your house, Acorn Finance is the specialist you want. They concentrate on financing for contractors, making it much simpler to fund home upgrades even if your credit history isn’t perfect. This is incredibly helpful for postal workers who have spent years building their community and now want to boost their own property value.
They emphasize a transparent experience, letting you scout rates without any negative impact on your credit score. It is an ideal way to see what a new roof, deck, or kitchen remodel might cost without the pressure of a formal application. By smoothing the path between homeowners and specialist lenders, they remove the friction often found in home renovation loans.
Pros:
- Contractors face zero dealer fees
- No impact on credit when checking rates
- Top-tier customer feedback on Trustpilot
Cons:
- Mainly restricted to home improvement needs
6. Credit Ninja
When big banks tend to shut their doors on you, Credit Ninja is often the one standing there with an invitation. They specialize in assisting people who might not fit the mold for standard loans, such as those with recent credit setbacks or thin credit histories. Their application setup is built to be swift, easy, and incredibly fast.
They cut through the red tape that typically stalls small loan requests. Their mission is to provide a way out when unexpected costs arrive and you feel like you’ve hit a dead end. If you cannot find a “yes” elsewhere because of a specific credit issue, their installment loans might offer the breathing room you need.
Think of them as a safety net for those sailing through choppy credit waters. They provide a path forward even when every other door seems to be locked tight.
Pros:
- Quick decisions on the same day
- Straightforward and rapid online application
- Built for those with non-traditional credit
Cons:
- Not a fit for every single credit scenario
Navigating the Hidden Dangers of Lending
Before ink hits the paper on any credit contract, you must truly grasp the machinery of your agreement. It is easy to get swept up in the allure of flashy advertisements that promise tiny monthly installments. Unfortunately, these often act as bait, masking the actual price of borrowing within the microscopic text of the fine print.
To ensure you aren’t walking into a financial ambush, demand a comprehensive breakdown of the “Total Cost of Loan.” This number serves as your North Star, revealing the full amount of capital that will vanish from your bank account throughout the entire life of the debt.
Keep a sharp eye on these three critical areas to keep your finances on the straight and narrow:
- The Prepayment Penalty: It feels like a slap in the face if you try to settle your debt ahead of schedule. Some institutions levy extra charges if you attempt to clear your balance early. If a sudden windfall or a tax return lands in your lap, you should be able to pay it off without being penalized for your prudence. Seek out lenders that offer “no prepayment penalties.”
- The Origination Fee: Think of this as a processing toll that the lender collects for setting up your account. This amount is frequently sliced directly from your initial disbursement. If your car repair requires exactly $2,000, a lender applying a 5% origination fee will only deposit $1,900 into your hands. Never forget to confirm the “net proceeds” before committing.
- Variable vs. Fixed Rates: A variable interest rate can feel like a rollercoaster ride in a shifting economy. While the initial rate might seem incredibly tempting, your monthly obligation could skyrocket if market conditions change. For someone who needs a steady, predictable budget, locking in a fixed-rate loan is generally the much smarter, safer path forward.
Setting Yourself Up for a Smooth Approval Process
Securing a loan when your credit isn’t stellar requires more than just hope; it requires a strategy. Even when dealing with lenders who offer a bit of grace regarding your score, arriving fully prepared acts as your best wingman. Being organized signals to the creditor that you are a serious, reliable candidate.
Lenders essentially want a clear roadmap of your financial life. They need to verify that every dollar you claim to earn is actually hitting your bank account. Taking a quick thirty minutes to round up your files can save you from a massive headache later on.
There is nothing worse than needing cash urgently only to find your application stuck in limbo because of a missing document. Preparation is the bridge between a “maybe” and a “yes.” By doing the heavy lifting now, you ensure that your funding arrives exactly when you need it most.
Use this checklist to iron out the kinks before you hit submit:
- Collect Income Evidence: Keep your last two or three pay stubs in a neat folder. Since you work for the USPS, having your latest W-2 at your fingertips is a smart move. It provides a quick way for lenders to confirm how long you’ve been on the job.
- Map Out Your Monthly Costs: Lenders will scrutinize your “debt-to-income ratio,” which is just a fancy way of measuring your monthly obligations against your take-home pay. Total up your rent, vehicle loans, and any other debts to get a realistic view of your budget.
- Double-Check Personal Data: Make sure your current address, workplace details, and phone number are identical to what your bank has on file. If these details don’t line up, it might trip a red flag for fraud, which will slow everything down.
- Scrutinize Your Credit History: Even if you are pursuing a “no credit check” loan, you should still know exactly what is on your record. If you spot a mistake, like a payment marked late by error, fix it now to improve your future borrowing power.
Finding the right lender is a lot like picking out a new pair of work boots. You need a fit that accommodates your unique feet, provides enough ankle support for the long haul, and won’t crack under pressure. Don’t just look at the sticker price; look at the long-term wear and tear.
It is vital to look beyond the initial “easy” pitch. While a “no credit check” offer might seem like a lifeline in a pinch, the interest rates can often be quite steep. Always run the numbers to see the full cost of the loan over its entire lifespan.
You never want to be blindsided by a mountain of interest when you thought you were just making a small monthly payment. Knowing the total amount you will ultimately repay is the only way to avoid a financial trap. Transparency is your best friend when entering into any contract.
Lastly, lean into the fact that you have a stable career. Many lenders see postal workers as gold because of the job’s inherent reliability. You might find better terms or more lenient requirements by specifically seeking out lenders that favor federal employees or highlight your professional stability.
