
Get Quick Loans for the Unemployed with Bad Credit Today
Last updated: 2026-10-16
Getting laid off hits like a ton of bricks. One day you are thriving, and the next, you are staring at a growing pile of invoices that simply do not care that your income has evaporated. It is a gut-wrenching experience that leaves many feeling like they are drowning in a sea of mounting debt.
The fear isn’t just about trimming your luxuries; it is about the fundamental need for shelter and warmth. When that regular direct deposit stops arriving, the pressure to settle rent or electricity costs can become truly overwhelming. It feels like trying to walk a tightrope during a thunderstorm.
You are essentially performing a frantic balancing act. You must find a way to settle your immediate debts while desperately trying to preserve some shred of long-term solvency. It is a high-stakes game where the rules seem rigged against those facing sudden hardship.
Adding a bruised credit score to this mix is like pouring gasoline on a fire. Standard banking institutions tend to slam the door shut the second they notice a lapse in your employment or a dip in your rating. To them, a lack of a steady job is just a red flag for potential non-payment.
Most large-scale lenders use rigid algorithms that trigger instant denials for anyone without a traditional paycheck. They view unemployment as a high-risk gamble they aren’t interested in taking. This leaves many people feeling completely abandoned by the traditional financial system.
We have put together this review to highlight which providers actually offer a lifeline for those navigating these murky financial waters in 2026. The following companies might provide the breathing room you need right now.
- Avant
- Upgrade
- FastLendGo
- Wells Fargo
- NetCredit
- OneMain Financial
Our Selection Methodology
Finding the right lender requires digging beneath the surface of flashy marketing campaigns. We prioritized speed of disbursement and how accommodating the signup process truly is. For anyone currently between roles, the ability to present bank statements instead of standard pay stubs is a game-changer.
Being able to prove your financial reliability without a traditional boss can be the difference between a successful application and an immediate decline. We looked closely at how lenders validate income via third-party data aggregators. This technology serves as a vital safety net for freelancers or anyone with a fluctuating paycheck.
Instead of asking “does this person have a job?”, these lenders ask “can this person manage their debt?” This fundamental shift in perspective is crucial for those without a conventional salary. It turns a potential roadblock into a navigable pathway.
Honesty is paramount in this industry. A company might promise instant cash, but if the interest is predatory, you’re just digging a deeper hole. We avoided lenders that hide the true cost of borrowing behind long-term extensions.
For example, a low monthly bill might look enticing, but a 72-month term can cause you to pay back double the original principal. Our goal was to find a sweet spot between credit accessibility and sustainable, fair repayment terms.
| Provider | Credit Limit | Terms & Interest | Disbursement Time | Credit Criteria |
|---|---|---|---|---|
| Avant | See site | See site | See site | Bad Credit Options |
| Upgrade | Up to $50,000 | See site | Fast funding | See site |
| FastLendGo | $500 – $5,000+ | See site | Quick access | Bad/Fair/Good |
| Wells Fargo | See site | See site | See site | Traditional Requirements |
| NetCredit | Up to $10,000 | See site | Same-day available | Advanced Algorithms |
| OneMain Financial | $1,500 – $30,000 | From 11.99% APR | As soon as 1 hour | See site |
1. Avant
Avant attempts to provide a stepping stone for people navigating life’s unexpected turbulence. Their product suite includes various installment loans and credit cards designed for those seeking a financial reset. Unlike the rigid structures of massive banks, they utilize a unique proprietary model.
Rather than focusing exclusively on a static FICO number, they scan a broader spectrum of financial health indicators. This nuanced view makes them an excellent tool for consolidating debt or building an emergency cushion. If a sudden car repair threatens your ability to attend job interviews, they provide a way out.
They also cater well to those managing inconsistent income streams or transitioning between employment. It is a pragmatic solution for anyone looking to tidy up several high-interest obligations into one manageable monthly bill.
Pros:
- Diverse loan products tailored to various needs
- Complementary credit card availability
- Designed to facilitate financial progress
- Standard rates aren’t always transparently listed online
2. Upgrade
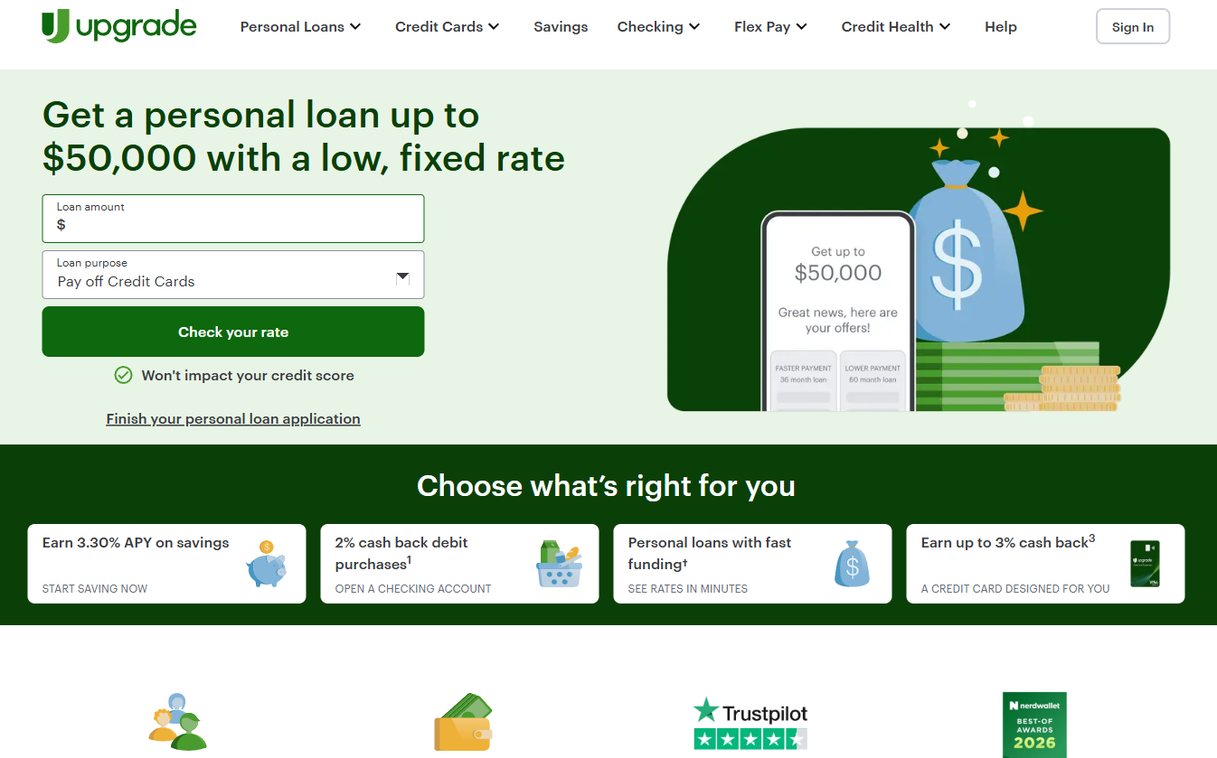
A heavy hitter in the personal lending space, Upgrade provides significant capital, reaching up to $50,000. Their funds can cover anything from major home renovations to one-off large expenses. Their entire digital infrastructure is built around rapid delivery to the borrower.
One standout feature is their ability to offer rate checks in mere minutes without any damage to your score. They achieve this through a “soft pull” mechanism for the initial evaluation. This is a massive advantage when you are comparing different offers to find the best deal.
Shopping for terms becomes a stress-free endeavor because you aren’t accumulating a mountain of “hard inquiries” that could tank your rating. They also feature a checking account that rewards you with cash back on debit spending, acting as a comprehensive financial ecosystem.
For those needing substantial funds to wipe out existing debt or jumpstart a project, the process is incredibly slick. Since the application is optimized for mobile devices, it is perfect for people who rely on smartphones rather than traditional desktop computers.
Pros:
- Large borrowing capacity up to $50,000
- Check rates quickly without hurting your credit
- Added value through checking account rewards
- Top-tier interest rates may require higher credit
3. FastLendGo
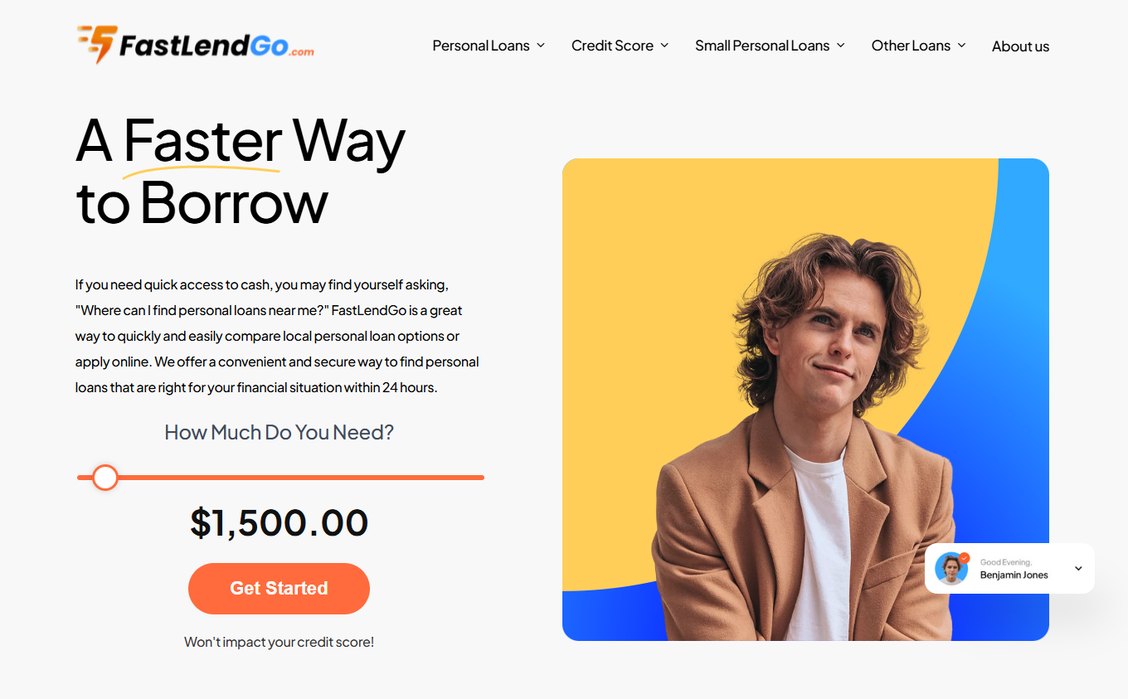
FastLendGo is a reliable partner for those facing urgent, smaller financial hurdles. Their specialty lies in modest personal loans, with entry points starting at just $500. This makes them an ideal choice for immediate needs like dental work, auto repairs, or utility deposits.
Because these loans aren’t massive, the barrier to entry is often much lower than at a giant commercial bank. They have streamlined their online interface so you can weigh your options in a snap. (fastlendgo.com)
Whether your credit profile is considered good, fair, or poor, there is likely a product tier meant for you. For example, if you maintain a “fair” score but have a history of consistent income, you might secure better terms here than elsewhere.
They offer a rapid infusion of cash for people in a pinch, helping to prevent a small problem from spiraling into a catastrophe. It is about providing immediate relief for pressing, real-world issues.
Pros:
- Low starting point for small-scale needs
- Tailored for specific emergencies like auto or dental
- Easy comparison of localized lending options
- Small loan limits may not cover heavy debt
4. Wells Fargo
Wells Fargo stands as a titan in the financial world. As a cornerstone of American banking, they provide an array of services ranging from basic checking to specialized auto and home financing. They offer a level of physical stability and institutional presence that many newer apps cannot replicate.
However, for those currently without a job, securing a loan here can feel like climbing a mountain without gear. Traditional banks usually demand two years of continuous, documented work history and a specific debt-to-income balance. They are generally risk-averse when it comes to unverified income.
That said, once you have secured a new position, they become an excellent partner for rebuilding your credit. If you are already a customer, it is often worth talking to a live representative about potential hardship programs or assistance.
A real-world conversation with a bank employee can sometimes bypass the rigid “no” of an automated algorithm. It is a place for long-term financial stability rather than quick, emergency fixes.
Pros:
- Massive variety of banking products
- Extremely well-established and trusted name
- Wide array of wealth management services
- Rigid requirements for standard lending
5. NetCredit
NetCredit operates under the philosophy that your identity is more than just a single number on a screen. They utilize sophisticated algorithms to look beyond a standard FICO score. This makes them a lifeline for those with less-than-perfect credit who still need meaningful funding.
By analyzing how you manage day-to-day expenses like rent or utilities, they can detect a level of reliability that traditional reports often overlook. This holistic view helps them offer loans up to $10,000 with incredibly fast turnaround times.
Their application is designed to be simple and efficient, which is perfect for managing urgent costs or rolling multiple high-interest debts into a single, more affordable monthly payment. It’s a strategic way to regain control of your finances.
Pros:
- Underwriting through sophisticated algorithms
- Possibility of same-day funding
- Borrowing amounts up to $10,000
- Governed by specific partner bank regulations
6. OneMain Financial
If you find comfort in face-to-face interaction, OneMain Financial is an ideal choice. With a massive footprint of 1,300 branches, they offer a personal touch that digital-only lenders lack. They provide loans between $1,500 and $30,000, with rates starting at 11.99% APR.
One of their most impressive features is the speed of their disbursement. In some cases, you can see the funds in your account just an hour after the paperwork is finished. This is life-saving when you’re facing an emergency, such as a broken heating system.
The ability to sit down with a professional and explain your unique situation provides a level of psychological relief that a web form simply cannot provide. It is a human-centric approach to personal finance.
Pros:
- Rapid funding, potentially within the hour
- Large network of physical branch locations
- Fixed, predictable monthly repayment amounts
- Requires an in-person or manual signing process
Decoding the Actual Expense of Your Loan
Before putting pen to paper, you really need to grasp how the Annual Percentage Rate (APR) differs from your scheduled monthly installment. While many eyes fixate solely on what leaves your bank account each month, the APR provides the full picture by incorporating both interest and compulsory service charges. It is the gold standard for evaluating a loan’s actual weight on your wallet.
In the middle of a financial storm, it is easy to let a small monthly bill blindside you. However, a low installment amount can act as a siren song if the repayment period stretches out indefinitely. You might think you are getting a break, but a long term can actually deepen your hole.
Imagine a scenario where you are paying $500 every month. On the surface, that seems like a walk in the park. Yet, if that commitment spans five years, you will end up returning a mountain of cash far exceeding the initial sum you received. It is a clever mirage of affordability that often pulls people into a cycle of endless debt.
As you weigh your various options, keep these three critical indicators at the forefront of your mind:
- The Complete Loan Price: To find the true cost, take your monthly amount, multiply it by the total duration of the term, and then add any initial processing charges. This number tells you exactly what that borrowed capital costs you in the long run.
- Early Repayment Charges: Should you land a new position and want to wipe out your debt early to dodge more interest, verify if the lender charges a penalty. Always hunt for a “no prepayment penalty” clause to keep your flexibility.
- Processing or Origination Costs: Certain companies deduct fees from your capital before the funds ever hit your account. If you request $1,000 but only receive $950 in your hand, your effective interest rate is actually much steeper than the figure they initially advertised.
A Roadmap for Navigating Financial Hardship
Think of a temporary loan as a life jacket rather than a luxury cruise. While you’re between roles, this capital should only serve as a bridge to cover the bare necessities like groceries, your rent, electricity, and transit costs. It is vital not to spend this cash attempting to maintain a social facade or a standard of living your current situation simply cannot sustain.
The primary objective is to secure enough breathing room to hunt for your next career move without sinking into a whirlpool of predatory interest. If you treat this money as a permanent fix rather than a temporary patch, you might find yourself in a hole that is incredibly difficult to climb out of later.
During this transitional phase, you need a tactical approach to shield both your mental peace and your credit score. Staying proactive can prevent a temporary setback from turning into a permanent catastrophe. Consider these vital maneuvers to keep your head above water:
- Reach Out to Lenders Early: If a car payment or mortgage bill seems out of reach, don’t wait for a missed deadline to act. Call your bank immediately. Most institutions have specific programs for financial hardship or forbearance designed to help people in exactly your position.
- Rank Your Needs: When the wallet is light, prioritize survival. Your roof, your food, and your utility bills must come before the credit card companies. Keeping your basic needs met is far more urgent than maintaining a perfect credit score.
- Slash Unnecessary Costs: It might seem trivial, but pruning your digital life pays off. Cutting a gym membership or a streaming service might save $50 or $100 every month. When you are living on a skeleton budget, those small wins accumulate quickly.
- Maintain Detailed Records: Treat every loan application, email from a creditor, and specific term like a legal document. Store them in a dedicated folder. If a conflict arises down the road, having a complete paper trail will be your strongest ally.
Every single cent carries significant weight when you don’t have a steady paycheck. A single oversight can lead to an expensive mess. Before signing anything, look past the monthly installment amount and scrutinize the total cost of borrowing in the fine print. You must avoid being ensnared by skyrocketing interest rates while you are already struggling.
It is tempting to grab multiple small loans from various lenders to patch different holes, but this is a dangerous game. Such behavior often sparks a debt cycle that feels impossible to break. Instead, seek a single, cohesive solution that tackles your most pressing crisis with a repayment plan that aligns with your actual income.
If the walls feel like they are closing in, remember that high-interest debt isn’t your only option. Negotiating with your current creditors or seeking out local community assistance might offer more relief than a new loan ever could. Always balance the immediate relief of a loan against the long-term consequences for your future self.
