
Best Ways to Secure Dental Financing for Your Next Procedure
Last updated: 2026-10-16
Few things sting quite like the sudden realization that dental care carries a heavy price tag. It feels like a financial gut punch when you realize the cost of a new crown or dental implants. Many patients sit in the waiting room staring at estimates, dreading the impact on their savings.
Sometimes, you are facing a sudden crisis, like an agonizing infection requiring an immediate root canal. Other times, you are dreaming of a cosmetic overhaul via veneers to refresh your appearance. Regardless of the reason, the initial expense can feel like a mountain too high to climb without help.
Navigating these costs without draining your life savings is vital. You need to protect your oral hygiene without sabotaging your long-term budget. Finding a middle ground between health and wealth is the goal for every savvy patient.
Selecting a payment plan involves much more than just checking a monthly figure. You must scrutinize the interest percentages and how a provider evaluates your credit history. Speed of approval is also a massive factor when you are in discomfort.
A low monthly payment might look tempting on paper. However, if the interest is sky-high, a 24-month plan could inflate your total debt by thousands. You might end up paying for the procedure twice just to cover the interest accrued over two years.
On the flip side, lenders with strict credit requirements can be a headache. They might demand a perfect score, leaving you in physical agony while waiting weeks for a decision. This comparison examines the leading industry names to guide your journey toward a bright smile.
- CareCredit
- Cherry
- FastLendGo
- iCare
How These Dental Payment Solutions Were Evaluated
The selection process focused on the specific needs of patients facing unexpected oral health costs. We looked at whether a lender provides quick decisions, which is vital when a toothache won’t quit. Speed often matters just as much as the actual cost of the loan when you are in pain. If you are sitting in a waiting room with a throbbing molar, you don’t want to be told you have to wait three business days for a manual underwriting process to finish. You need a solution that works in real-time.
We also weighed the accessibility of these options for individuals with varying credit profiles. Some patients have pristine scores and can qualify for the lowest possible APRs, while others are just trying to keep their heads above water and may have a history of late payments or high credit utilization. A good financing partner should offer a way forward, regardless of whether your credit history is a polished gem or a bit of a mess. We evaluated lenders based on three primary pillars: speed of approval, ease of application, and the breadth of credit eligibility. We also considered the “hidden” costs, such as origination fees or penalties for early repayment, which can turn a simple payment plan into a long-term debt trap.
| Lender Name | Primary Use Case | Speed of Decision | Credit Requirement | Loan Amounts |
|---|---|---|---|---|
| CareCredit | Health & Wellness | Instant | Subject to Approval | See site |
| Cherry | Flexible Payment Plans | Fast | Broad Eligibility | See site |
| FastLendGo | Personal Loans | Quick | All Credit Tiers | $500 – $5,000+ |
| iCare | No-Nonsense Financing | Instant | No Credit Check | See site |
The Hidden Price of Postponing Treatment
It is incredibly easy to shove a dental invoice into a drawer and forget about it. We often tell ourselves we will handle it “sometime later,” but waiting is a dangerous game. In the dental chair, time is a luxury that translates directly into your bank account balance.
Health problems in your mouth do not stay still or sleep through the night. They tend to snowball rapidly. For example, a tiny cavity might only demand $200 for a quick fix right now. If you wait half a year, that same tooth could crack, forcing you to pay $1,500 for a crown.
If the infection migrates toward the nerve, the situation becomes a financial nightmare. You might find yourself staring down a $2,500 bill for a root canal and a buildup. It is like watching a small leak in a roof; ignoring it today ensures a massive renovation bill tomorrow.
Evaluating Your Financial Choices
When you weigh your various financing paths, try looking at the numbers through a different lens. Do not just look at the interest rates; instead, compare that amount to the escalating price of the untreated tooth. It changes your perspective on what “expensive” really means.
Imagine a lender offers a 0% interest plan for a six-month window. Using this is like finding money on the sidewalk. It allows you to keep your cash flow smooth without paying a single extra cent for the privilege of spreading out your payments.
On the other hand, you might be tempted by a high-interest personal loan to get care immediately. Before signing, run the math carefully. You need to ensure the interest you pay is actually lower than the projected cost of the procedure if the dental issue gets worse.
Often, paying a bit of interest is a small price to pay for peace of mind. It is much better to deal with a predictable monthly payment than to face a sudden, costly surgical emergency when you least expect it.
Top-Rated Financing Options for Your Dental Procedures
1. CareCredit
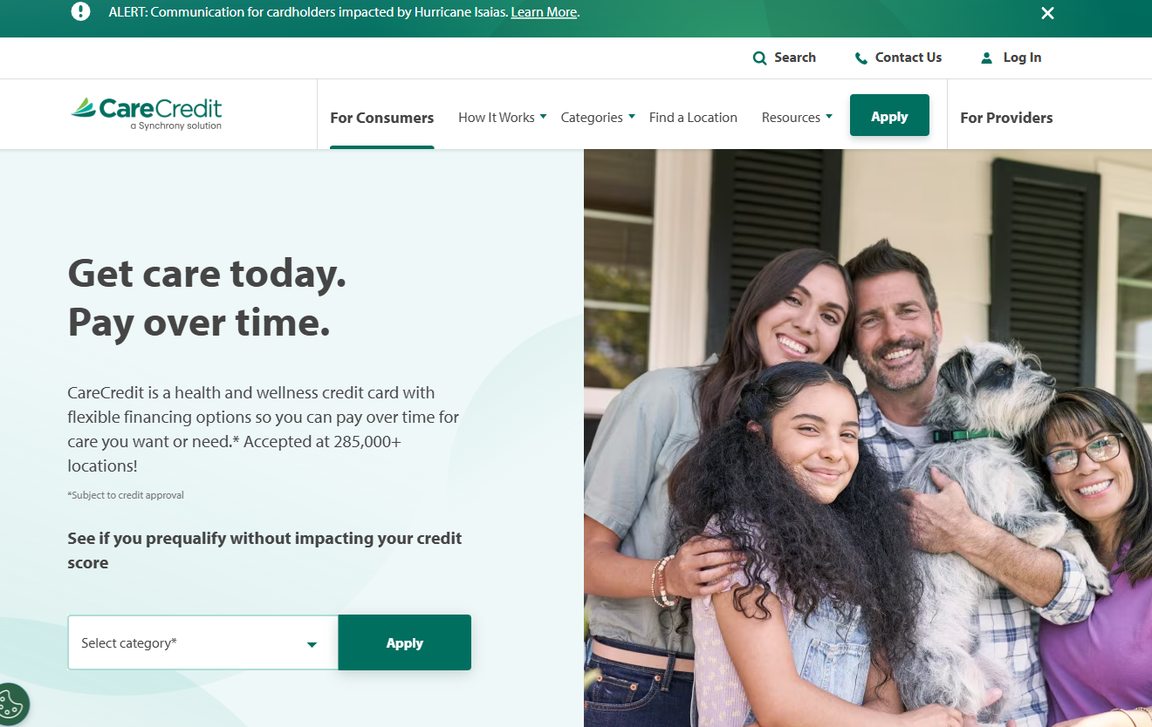
Think of CareCredit as a specialized tool in your medical toolkit, designed specifically for wellness and dental expenses. It is a major player in the sector, boasting acceptance at more than 285,000 locations. You won’t have to hunt for a place that takes it, as many dental offices already have it on file.
Using this dedicated line of credit can be a smart move for your financial health. Because it is a separate account, it won’t bloat your primary card’s utilization, helping you keep your credit score on an even keel. If you’re in a rush, you’ll be pleased to find that the application process is lightning-fast, providing decisions on the spot.
Many clinics offer promotional windows where you can enjoy 0% interest for 6, 12, or 24 months. However, don’t treat this like a free lunch. If you miss the deadline for paying the full balance, the interest is often backdated to day one, which can sting quite a bit. You really need a disciplined budget to make this work for you.
Pros:
- Widely recognized by dental practices across the country.
- Rapid approval allows you to begin your care almost immediately.
- Checking your eligibility via prequalification won’t hurt your credit score.
Cons:
- Approval depends on your credit and standard card regulations.
2. Cherry
Cherry has really hit a stride by offering payment arrangements that feel much more human. They have broadened their eligibility requirements, which is a huge relief for patients who feel intimidated by traditional banking hurdles. It feels less like signing a heavy contract and more like using a helpful service.
Instead of a revolving credit line that can be hard to track, Cherry tends to work like a structured installment loan. You will know exactly what your monthly commitment is and when it is due. This clarity is a breath of fresh air for anyone trying to manage their household budget while tackling dental costs.
The checkout experience is incredibly smooth, often integrated directly into the dentist’s office software. You can usually finalize your plan with just a few taps on a tablet. This seamless integration makes the whole process of securing care feel quick and remarkably straightforward.
Pros:
- Broadens access by offering wider eligibility for many applicants.
- Serves as a flexible alternative to the standard credit card model.
- Simple, streamlined setup for your payment plan.
Cons:
- Credit limits might be lower than what you would see with traditional lines.
3. FastLendGo
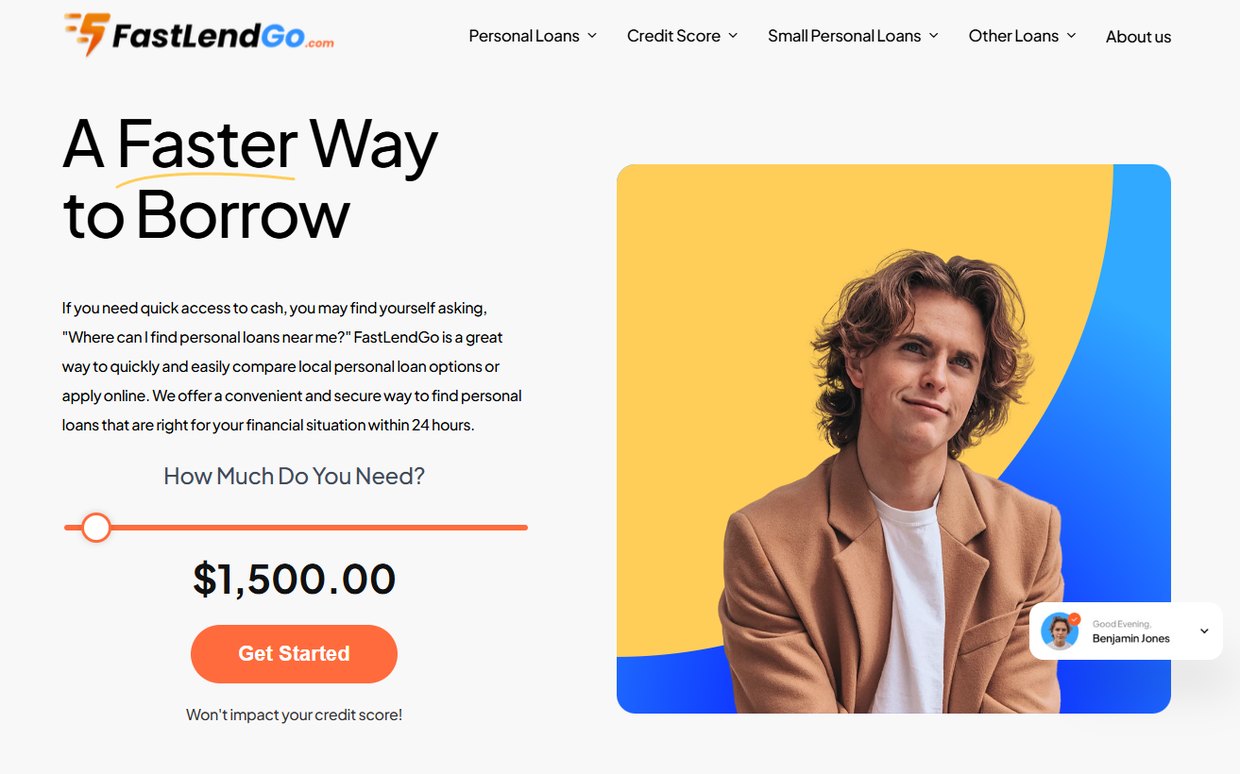
FastLendGo acts as a versatile ally for those seeking personal loans for various needs, including dental work. They cover a vast spectrum of borrowers, ranging from those with impeccable credit to those navigating bad credit. This makes them a reliable fallback when a dentist’s internal financing isn’t an option or is too restrictive.
Unlike a credit card that you swipe at the counter, a loan from FastLendGo is typically sent straight to your bank account. This gives you a lump sum of cash to handle large procedures. They offer flexible amounts, starting from $500 and scaling up to $5,000 or even higher.
This approach is particularly handy if your provider doesn’t work with third-party financing. Having that cash ready in your account might even allow you to haggle for a “cash discount,” which can help offset the interest you pay on the loan itself. It’s a strategic way to handle significant dental expenses.
Pros:
- Accommodates various credit profiles, including those with bad credit.
- Provides specific loan amounts tailored to your actual needs.
- Delivers quick access to cash for urgent dental repairs.
Cons:
- Interest rates can fluctuate significantly depending on your credit history.
4. iCare
iCare has taken a completely different path with their unique, straightforward program. Their most notable feature is the ability to provide 0% interest financing without requiring a credit check. This can be a total game-changer for patients who need immediate care but cannot wait for a lengthy financial investigation.
For many, the mere thought of a credit check causes significant stress, fearing a rejection or a permanent scar on their score. iCare removes that “fear factor” entirely. This allows patients to focus on getting their teeth fixed rather than worrying about their financial standing or future interest rates.
It works beautifully as a bridge for people experiencing a temporary cash crunch who still have the steady income to handle monthly payments. By moving away from traditional credit scoring, they open doors for many people who might otherwise have had to put off essential medical work.
Pros:
- Offers options to pay with 0% interest.
- Instant approval is possible without a credit check.
- Provides highly adaptable financing structures for the user.
Cons:
- Whether it’s available depends on your specific dental provider.
Weighing Your Options: Loans, Credit, and Monthly Payment Plans
Picking the right way to pay for your smile is a bit like choosing a vehicle for a long road trip. You wouldn’t want to end up stranded on the side of the highway halfway through the journey. You need to grasp how these different monetary instruments actually function before signing any paperwork. Not every form of borrowing carries the same weight on your wallet or your credit score over time.
Think of your debt as a living thing that evolves based on how you handle it. The specific mechanics of your repayment schedule will ultimately dictate your financial stability in the years to come. It’s better to weigh these choices now rather than dealing with the fallout of high interest later. Let’s pull back the curtain on how these popular options stack up against each other.
| Category | Credit Card (e.g., CareCredit) | Personal Loan (e.g., FastLendGo) | Installment Plan (e.g., Cherry) |
|---|---|---|---|
| Format | Revolving (available for reuse) | Lump Sum (single disbursement) | Fixed Term (set monthly amounts) |
| Interest Rate Style | Frequently 0% intro (then high APR) | Steady APR for the entire period | Generally fixed or inexpensive |
| Credit Score Effect | Changes utilization and payment records | Changes debt-to-income proportions | Very little impact if a service model |
| Ideal Use Case | Expensive, long-term treatments | When you require liquid cash directly | For simple, steady monthly planning |
If you are looking at a massive overhaul, like full implants, a credit card might seem enticing. Many people jump at the chance of zero-percent interest, but it is a double-edged sword. If you miss a deadline, that high APR will come knocking like an unwelcome guest. You must be disciplined to make those promotional windows work for you instead of against you.
On the flip side, some patients prefer the simplicity of a personal loan. It’s like receiving a gift of cash that you eventually pay back in a single, straight line. Since you get the money directly into your bank account, you have more control. However, keep a close eye on how that new debt changes your overall financial profile.
Lastly, there are installment plans, which are the “set it and forget it” option for many. They are perfect for those who want to keep their monthly budget as predictable as a sunrise. Because these are often structured as service agreements, they tend to leave your credit score largely untouched. It is a smooth path for those who value peace of mind above all else.
Steering Clear of Budgetary Traps
Before putting pen to paper, scrutinize the tiny print concerning interest rates. It is incredibly tempting to jump at a “no credit check” deal, but you must realize if the final price of your treatment climbs because of hidden fees or deferred interest. Don’t let the shiny promises blind you to the actual math.
For example, consider a plan boasting 0% interest for 12 months that demands a 5% “origination fee” right away. In that scenario, your real cost of borrowing is much steeper than the advertisement suggests. Always inquire with your dental office about their relationship with specific lenders and if administrative fees are tacked on during setup.
Another blunder is failing to weigh how this affects your wallet long-term. A monthly installment might seem like a mere drop in the bucket—perhaps $75 a month—but once it clashes with your car loan, cell phone bill, and the skyrocketing cost of eggs, it becomes a mountain. It can feel like you are drowning in debt.
This “payment shock” happens when a patient suddenly realizes they have juggling several different credit obligations at once. Ensure your repayment timeline aligns with your actual lifestyle, rather than just your immediate desire for a fresh smile. It isn’t just about fixing teeth; it’s about keeping your head above water.
Try to settle your dental debt as rapidly as you can manage. Even if you managed to snag a 0% interest deal, paying it off ahead of schedule offers immense peace of mind. Furthermore, it clears up your monthly cash flow, leaving you with more breathing room for other essential life expenses.
