
Get motor cycle loans for bad credit and ride away today
Last updated: 2026-10-16
Hunting for a fresh set of wheels when your credit score has taken a dive can feel like running headlong into a solid wall. It is a gut punch for any enthusiast. Many bikers mistakenly believe that a tarnished financial record condemns them to riding clunkers for the rest of their lives.
Perhaps your files show a pattern of missed due dates or a mountain of existing debt relative to your earnings. Maybe a recent bankruptcy still lingers like a shadow on your reports. Regardless of the reason, facing a rejection when your eyes are fixed on a specific model is a massive blow.
The truth is, the banking landscape has undergone a massive transformation lately. The days of rigid, cookie-cutter loan policies are rapidly becoming a thing of the past. We are living in a fractured market where niche providers find immense potential in the very areas that giant, mainstream banks tend to ignore.
The following selection highlights companies that prioritize the individual rather than just a cold spreadsheet. These lenders provide a bridge to motorcycle ownership, even if your fiscal journey has been somewhat chaotic or erratic. Whether you crave a screaming sportbike or a sensible daily driver, a suitable financing route exists.
- Roadrunner Financial
- FastLendGo
- OneMain Financial
- SCU Credit Union
- Sound Credit Union
Our Selection Methodology
Scouring the market for lenders when your credit is bruised requires a completely different strategy than when you have a pristine score. If you’re sitting on a 740 or higher, big banks will practically throw money at you to snag your business. However, once you drop into the 500s or low 600s, the game changes entirely.
At that stage, the conversation isn’t about hunting for the absolute lowest interest rate available. Instead, you’re just praying that a lender will even open their doors to you. We didn’t just chase the cheapest APRs; we focused on finding companies that actually provide a lifeline to riders with less-than-perfect financial histories.
It wasn’t enough for us to find companies that say “yes” to everyone. We dug deeper into their data privacy habits and their actual business ethics. We wanted to separate the predatory sharks from the companies that offer legitimate, albeit difficult, paths to ownership. Our goal was to find lenders that prioritize speed and offer no-risk prequalifications.
We also looked at the variety of rides they would finance. A lender that only touches brand-new showroom models is useless to a guy hunting for a vintage cafe racer or a beat-up dirt bike. We wanted versatility for every kind of rider, from the commuter to the weekend warrior.
Finally, we hunted for those pesky “hidden” traps lurking in the fine print. Charges like prepayment penalties or origination fees can turn a seemingly affordable monthly bill into a financial nightmare. This is vital if you plan to kill the debt early once your score recovers.
You never want to realize you are trapped in a high-cost cage just because the initial sticker price looked enticing. We looked for transparency so you can ride free without worrying about expensive surprises down the road.
| Provider | Loan Range | Duration | Approval Speed | Credit Standards |
|---|---|---|---|---|
| Roadrunner Financial | Check website | Check website | Rapid | All levels welcome |
| FastLendGo | $500 – $5,000+ | Check website | Fast access | Fair/Bad Credit |
| OneMain Financial | $1,500 – $30,000 | 24 – 60 months | ~1 hour | Check website |
| SCU Credit Union | Check website | Up to 60 months | Check website | New or Used |
| Sound Credit Union | Check website | Check website | Check website | Boat, RV, or Moto |
1. Roadrunner Financial
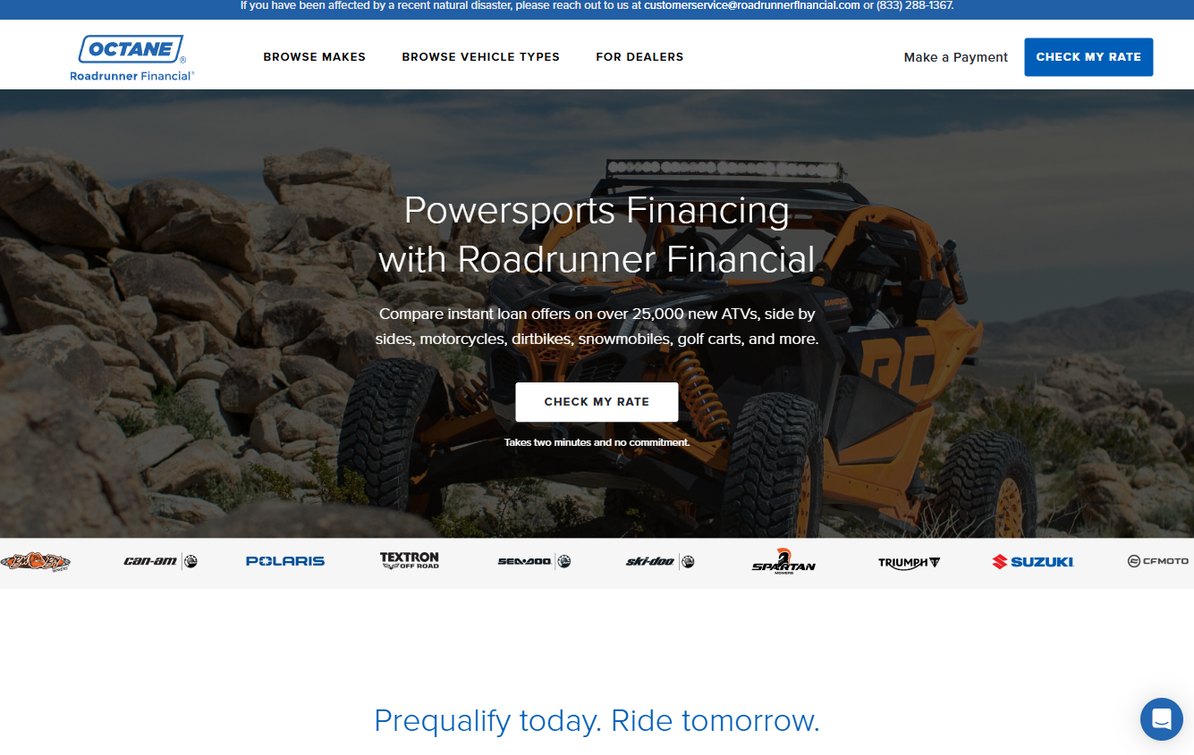
Think of Roadrunner Financial as the bridge between a rider and the local dealership lot. They are specialists in the powersports realm, meaning they cover everything from snowmobiles and dirtbikes to side-by-sides and ATVs. They are a heavy lifter for anyone trying to walk away from a dealership with a new ride without facing a massive wall of bureaucracy.
Instead of forcing you to play phone tag with a dozen different banks, they partner with a broad network of dealers to smooth out the approval process. It is a much more seamless way to get on two wheels. Their focus is entirely on making the dealership experience as painless as possible for the buyer.
The real magic happens with their two-minute rate check. Because they utilize a “soft pull” method, checking your potential rate won’t leave a dent in your credit score. You can shop around with confidence, testing the waters to see what you can actually afford without the fear of tanking your points.
Imagine you spot a used Yamaha XT250 on a lot. Instead of driving all the way there just to find out you can’t get financing, you can use Roadrunner to see if you qualify in minutes. This level of instant insight is a game-changer for anyone serious about buying.
Since they are deeply woven into the dealership ecosystem, the money is often moving before you’ve even finished your coffee. When the salesperson walks over, the financing might already be in motion. It makes the whole purchase feel like a simple transaction rather than a stressful, high-pressure negotiation.
Pros:
- Check rates without hurting your score
- Wide variety of powersports including golf carts
- Immediate decisions to streamline dealership visits
Cons:
- Primarily geared toward dealership financing over direct personal loans
2. FastLendGo
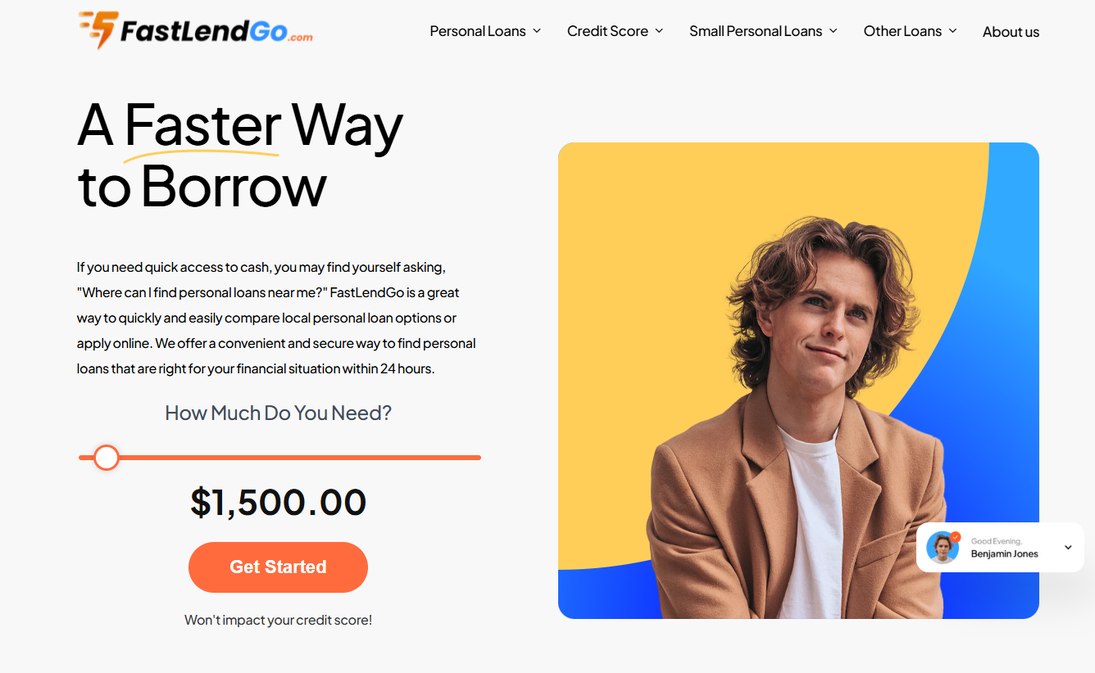
If you are in a tight spot and need quick cash to grab a deal, FastLendGo provides a direct route. They offer personal loans specifically designed to help those struggling with fair or bad credit. Unlike a standard auto loan that is tied to a specific vehicle’s VIN, this is straight cash in your hand.
This flexibility is a lifesaver if you are looking for a bargain on Craigslist or Facebook Marketplace. If you find a used Honda Rebel from a private seller, a traditional bank might balk because there is no collateral to back the loan. FastLendGo’s unsecured model is built for exactly those kinds of private-party deals.
They offer several different tiers of funding, ranging from $500 to $5,000 and up. This makes them a versatile partner for a huge range of financial needs. Whether you just need a small amount to patch up a ride or a larger sum to buy a bike outright, they have you covered.
Pros:
- Tailored options for fair and bad credit
- Easy comparison for various personal loan paths
- Flexible amounts starting as low as $500
Cons:
- Interest rates can be quite steep for those with low credit
3. OneMain Financial
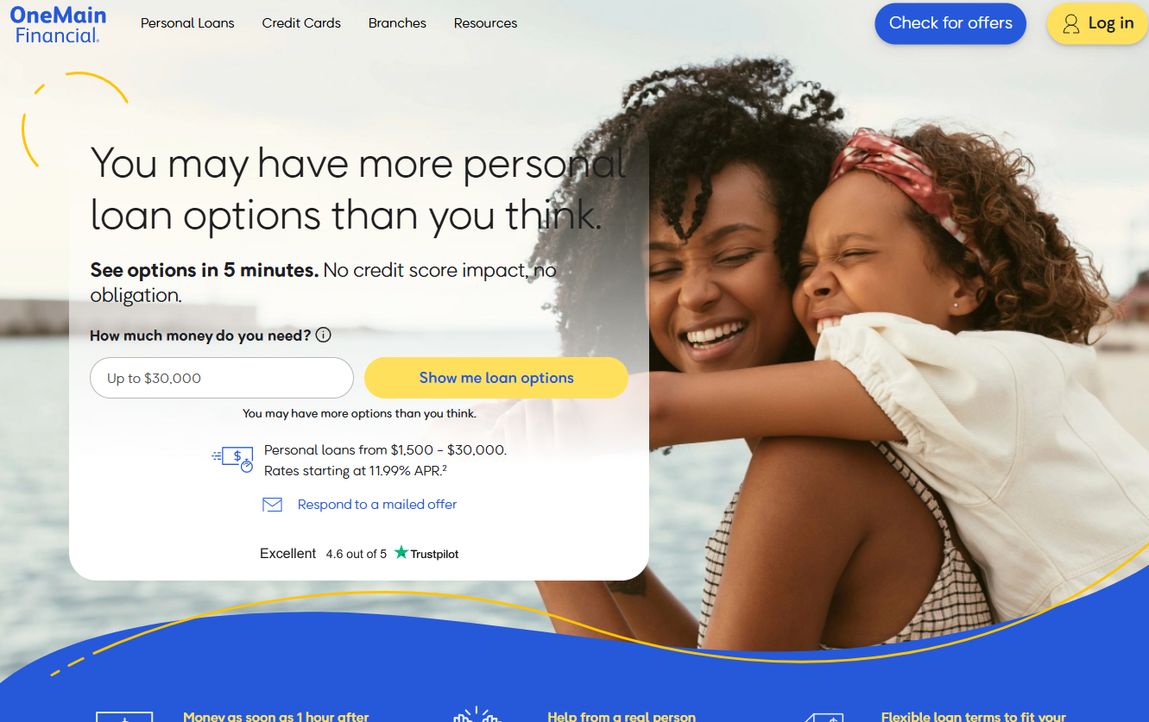
OneMain Financial is a massive heavyweight in the personal loan world, bringing a very structured approach to your borrowing needs. They provide significant funds, ranging from $1,500 up to $30,000. For most riders, this amount is plenty to cover the price of a solid used motorcycle.
If you are looking to move up from a small 250cc commuter to a beefier cruiser, their loan ceiling should easily cover that jump. They provide the financial muscle needed to make a significant upgrade without breaking the bank or your budget.
The speed at which they move is nothing short of impressive. You could potentially have your funds ready to spend just one hour after you sign the papers. This is perfect for when you find a “unicorn” bike—that rare model that won’t stay on the market for more than a day.
With fixed monthly payments and terms that run from 24 to 60 months, your budget stays predictable. You won’t have to deal with the stress of your monthly bill shifting unexpectedly. It allows you to enjoy your new hobby without worrying about the math changing halfway through the ride.
Pros:
- Rapid funding, potentially in just one hour
- Substantial loan limits up to $30,000
- Predictable, fixed monthly payments
Cons:
- Requires either a branch visit or interacting with their specific platform
4. SCU Credit Union
Credit unions often hold the “secret sauce” when it comes to finding better interest rates. Because they are member-owned non-profits, they aren’t beholden to the same profit pressures as the big commercial banks. SCU Credit Union provides financing for both used and new motorcycles, covering heavy hitters like Harley-Davidson or Honda.
They are an incredible resource if you are looking to clean up your financial life while picking up a new ride. For example, if you’re drowning in high-interest credit card debt, you might use an SCU loan to consolidate those balances. It can be a smart way to simplify your monthly outflows into one lower-interest payment.
These institutions tend to look at you as a person, not just a number on a screen. They might weigh your employment history or your ties to the community more heavily than a single, stagnant credit score. This holistic view can be a massive advantage for people working to rebuild their credit.
Whether you want a 60-month term or you’re looking to build up a savings account simultaneously, they have a suite of tools. They are a fantastic choice for the rider who wants to grow a long-term relationship with their financial institution.
Pros:
- Financing for both new and used bikes
- Debt consolidation capabilities
- Deep expertise across many vehicle types
Cons:
- Certain benefits may be limited by membership requirements
5. Sound Credit Union
Sound Credit Union is built to handle a massive variety of lifestyle needs. They offer specialized loans not just for motorcycles, but for boats and RVs as well. They take a comprehensive look at your entire financial life, making them a true “lifestyle” lender for those with diverse hobbies.
If you’re the type of person who needs a trailer to haul your bike or a boat for the weekend, Sound is built for you. They understand that your passions often come in sets, and they offer the specialized financing to support that entire way of life.
Building a banking relationship with Sound can be a very wise long-term move. Once you have a history of making on-time payments with them, your future loans—like a car or a mortgage—might be much easier to obtain. They are a strong contender for those seeking a reliable partner for their financial journey.
Pros:
- Focus on motorcycles and various powersports
- Full range of standard banking services
- Holistic approach to financial support
Cons:
- May involve more paperwork than instant-approval online lenders
Strengthening Your Application Profile
The lenders mentioned earlier are quite open to riders with less-than-stellar credit scores. However, if you want to snag a better interest rate, you shouldn’t just jump into the deep end. It is better to perform a little “pre-flighting” on your finances to ensure everything is shipshape before you actually press that application button.
Start by grabbing your credit reports from Equifax, TransUnion, and Experian to hunt for any inaccuracies. A random mistake, like an incorrectly logged late payment from a utility firm, might cause your score to plummet by as many as 50 points. If you spot a blunder, get those disputes filed right away.
Sometimes, a “pending dispute” note on your file can actually help when a human underwriter manually reviews your profile. Taking these steps ensures you aren’t fighting against ghosts in your financial history. It is a small effort that can yield massive dividends in the long run.
Next, you should assemble a thorough “financial dossier” to keep in your back pocket. If you are approaching institutions like SCU Credit Union or Sound, having two months of pay stubs, proof of your residence, and a breakdown of monthly costs ready to go is vital. It shows you aren’t just some dreamer, but an organized person.
Being prepared in this manner builds a sense of trust, which is essentially the golden currency for subprime lenders. When you present a clear picture of where your money goes, you stop being a gamble and start looking like a solid bet. It’s all about presenting your best self to the bank.
Finally, having a co-signer might just be the silver bullet you need to cross the finish line. If a relative with a rock-solid credit history is willing to stand behind you, the landscape changes completely. They are essentially telling the bank, “If this rider misses a payment, I will cover it.”
This arrangement dramatically shrinks the hazard for the lender. Because the risk is lowered, you might find yourself moving from a “denied” letter to an “approved” one with much friendlier, more manageable interest rates. It is a powerful way to turn a difficult situation into a smooth ride.
Charting Your Financial Path
Before ink hits the paper, keep in mind that a financing agreement is a serious pact. If your credit score is struggling, expect the interest rate to act as a surcharge for getting that bike today. You must scrutinize the entire cost of the debt rather than just focusing on the monthly installment amount.
A $200 monthly bill might appear easy on the wallet at first glance. However, if that installment stretches across 72 months at an 18% interest rate, you are essentially paying almost twice what the motorcycle is actually worth. It is a steep price to pay for a piece of iron and chrome.
Never hesitate to demand a “Truth in Lending” disclosure from your lender. This specific document is a legal requirement that simplifies the complex math for you. It provides a clear breakdown of every cent you will spend, including all mandatory fees and cumulative interest over the term.
If a salesperson starts sweating or dodging your request for this paperwork, turn around and walk out the door. If they attempt to bury the real costs in tiny, illegible print, consider it a massive red flag. Transparency is your best friend when navigating these murky waters.
Don’t let a pushy dealer bully you into signing a contract on the spot. The powersports industry can be a shark tank, particularly when they realize your credit profile is less than stellar. They might tempt you with a “no money down” option that sounds like a dream come true.
In reality, those tempting offers often hide astronomical interest rates that trap you in a cycle of debt for years. Take a deep breath and revisit the quotes you gathered when you first checked your prequalification status. A little bit of restraint today can keep thousands of dollars in your pocket tomorrow.
Remember, your ultimate objective isn’t merely to ride away on two wheels. Your true aim should be to enjoy your new machine without being shackled by financial weight. Aim to secure the bike while keeping your financial freedom firmly in your grip.
