
Best Rates for a 12 year personal loan: Compare Top Lenders Today
Last updated: 2026-10-17
Searching for a bank that permits a 12-year repayment timeline feels like trying to find a unicorn in a crowded city. Most mainstream lenders cap their terms at seven years. This leaves those craving extended flexibility in a real bind. To keep your monthly outlays low, you’ll need to look past standard “quick cash” outfits.
You’ll probably require a firm comfortable with large-scale asset financing or complex debt restructuring. Finding the perfect match isn’t just about spotting a low APR. You must balance the speed of funding against the cumulative interest accrued over twelve years.
A 144-month plan might seem like a dream due to the small monthly chunks. But, do the math carefully. You might discover that your interest costs nearly double what you originally borrowed. This selection highlights the best options to navigate long-term borrowing without drowning in debt.
- U.S. Bank
- Wells Fargo
- JetzLoan
- Citi
- OneMain Financial
- Alliant Credit Union
Our Selection Criteria for Borrowing Options
Our team went on a hunt to find lenders that actually offer flexibility and long-term options. Since many old-school banks pull the plug at 84 months, we steered clear of those rigid limitations. Instead, we prioritized companies that can handle longer timelines without breaking a sweat.
We dissected every step of the application journey to see how fast the money actually hits your bank account. It is not just about the speed of cash delivery, though. We also scrutinized whether these lenders play fair or hide sneaky costs in the fine print.
We dug deep into how these firms communicate their fee structures to the public. Transparency is the name of the game when you are looking at a massive financial commitment. If a company makes the math feel like a riddle, they didn’t make our final cut.
One non-negotiable for us was the ability to pay off your debt early without getting slapped with penalties. Making extra payments is a lifesaver for slashing the interest you pay over many years. If a lender punishes your proactive behavior, they simply aren’t the right fit.
Reliability is the backbone of any good financial partner. A rock-solid interest rate doesn’t mean much if the process feels like a marathon of paperwork. We wanted to ensure that our list included lenders who respect your time as much as your wallet.
Finding that sweet spot between established institutions and slick, digital-native apps was essential. We wanted to provide a toolkit for every type of borrower out there. Whether you want a big name or a fast app, we had you covered.
Finally, we looked past the surface-level interest rates to find the true cost of borrowing. We weighed the APR against the base rate to ensure our readers aren’t caught off guard. We wanted the real story, not just the marketing pitch.
| Lender Name | Maximum Borrowing | Length of Term | Time to Fund | Credit Check Method |
|---|---|---|---|---|
| U.S. Bank | see site | see site | see site | see site |
| Wells Fargo | $100,000 | 12-84 months | see site | see site |
| JetzLoan | $50,000 | see site | 24 hours | No hard pull |
| Citi | $30,000 | 12-60 months | see site | see site |
| OneMain Financial | $30,000 | 24-60 months | 1 hour | see site |
| Alliant Credit Union | see site | see site | see site | see site |
Leading Providers for Extended-Term Financing
1. U.S. Bank
Think of this institution as a cornerstone of the American financial landscape. They offer a vast array of tools that make life much easier for the organized borrower. Instead of jumping between apps, you can keep your savings, checking, and personal loans all tucked away in one tidy, centralized home.
For the seasoned planner who prefers a traditional approach, their setup is a dream. They prioritize stability, which is a lifesaver when you are committing to a long-term debt cycle. Having your entire financial life under one roof makes monthly budgeting feel like a walk in the park rather than a mountain to climb.
Imagine the relief of setting up an automatic transfer to cover your monthly installment. It’s a simple trick that guards you against those pesky late fees that can snowball over a decade. If you desire a one-stop shop for all your fiscal needs, you’ll feel right at home here.
Pros:
- A seamless banking environment for effortless management.
- A diverse selection of services, including investment options.
- A storied and reliable institutional background.
Cons:
- Application processes might demand more paperwork than online-only startups.
2. Wells Fargo
When the stakes are high, Wells Fargo steps up to the plate. If you are eyeing a massive project like a kitchen remodel or need to consolidate a mountain of debt, their ability to hand out up to $100,000 is a major selling point. They entice serious players with very competitive introductory rates, especially for those with a solid credit history.
This makes them a heavy hitter for anyone needing a large injection of capital right away. Their fixed interest rates provide a steady hand in an unpredictable economy. You won’t have to lose sleep worrying about your monthly payment suddenly ballooning because of market shifts.
That predictability is worth its weight in gold. While a variable-rate lender might offer a slightly lower starting rate, the peace of mind provided by a fixed payment often wins the day. It’s about knowing exactly where your money is going every single month without any surprises.
Pros:
- Massive borrowing ceilings reaching $100,000.
- Fixed rates that ensure your budget stays predictable.
- A vast network of physical branches for face-to-face help.
Cons:
- Securing the highest amounts usually requires top-tier credit.
3. JetzLoan
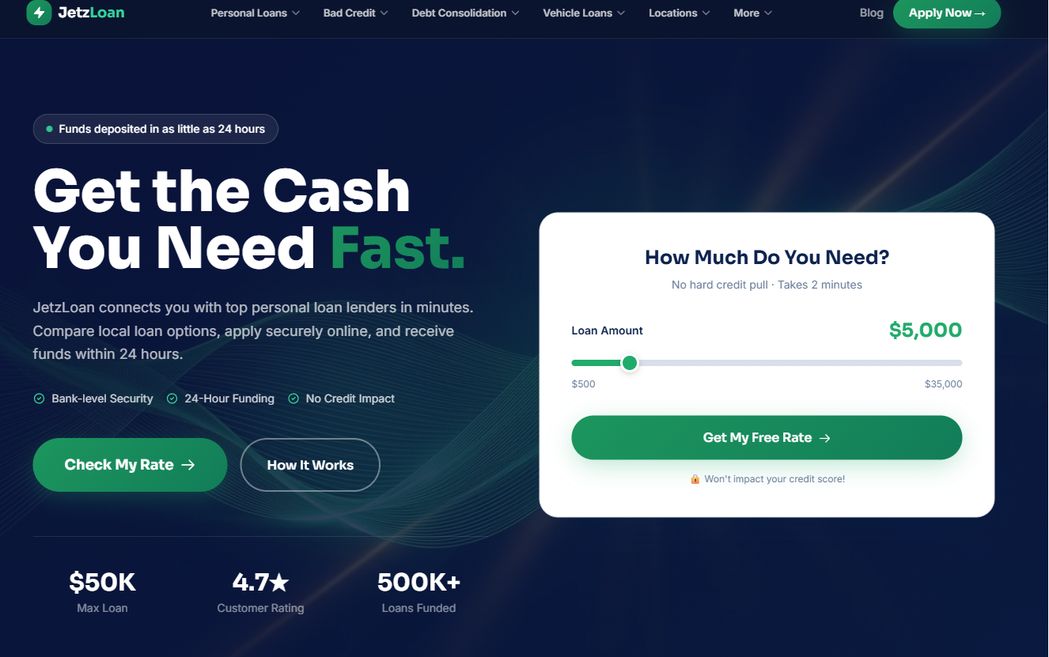
In the world of JetzLoan, time is the most precious commodity. If you find yourself in a financial pinch and need cash yesterday, JetzLoan is your fastest route to relief. They are built for speed, often getting funds into your pocket in as little as 24 hours.
This is the perfect solution for those sudden, “oh no” moments—like an emergency car repair or an unexpected medical bill. Sometimes, paying a slightly higher interest rate is a small price to pay for the speed you receive. Best of all, you can scout your rates through a soft credit pull, which keeps your score perfectly safe.
This “soft pull” approach is a breath of fresh air for anyone tired of playing the guessing game. It lets you weigh your options and compare different lenders without any risk to your credit profile. You get the raw facts without any lasting damage to your standing.
Pros:
- Lightning-fast funding, sometimes within a single day.
- No impact on your credit score when checking rates.
- Highly rated customers love the streamlined digital process.
Cons:
- Loan amounts are capped at a maximum of $50,000.
4. Citi
Citi has mastered the art of the digital-first experience, catering perfectly to the tech-savvy borrower. Their personal loans are a smooth ride, making the application process feel almost effortless. With terms stretching up to 60 months, they provide a perfect middle ground for various mid-range financial goals.
Their mobile app is often the gold standard for usability. It makes tracking how much principal you’ve knocked off or how much interest you’ve paid a total breeze. This is a premier choice for those who want to run their finances through a sleek, modern interface rather than wading through paperwork.
If your goal is to sweep up high-interest credit card debt and roll it into a neat 5-year plan, Citi is a top contender. It is an ideal fit for someone wanting a streamlined digital life without needing a decade-long commitment. The numbers on their interface are incredibly easy to read.
Pros:
- A world-class digital banking and user experience.
- Repayment windows structured up to 60 months.
- A strong reputation for handling significant credit limits.
Cons:
- Term limits cap out at 60 months, not 12 years.
5. OneMain Financial
If the big-box banks have left you out in the cold, OneMain Financial might be your way back in. They specialize in helping folks who might not have a spotless credit history. Their ability to deliver funds sometimes just one hour after the paperwork is signed is nothing short of legendary.
Rather than just staring at a frozen credit score, they look at your actual ability to pay the money back. This makes them a lifesaver for people navigating life’s transitions. They also keep a heavy human touch, boasting a massive footprint of over 1,300 physical branches across the country.
It’s a lot better than arguing with an unhelpful chatbot when things get messy. Having a real person to look you in the eye provides a level of accountability that pure fintech companies just can’t match. It offers a sense of stability when you feel like you’re on shaky ground.
Pros:
- Rapid funding that can happen in as little as an hour.
- Massive physical presence with over 1,300 locations.
- Accessible for borrowers with non-traditional credit profiles.
Cons:
- Interest rates might climb higher for certain borrowers.
6. Alliant Credit Union
Credit unions bring a unique flavor to the table, and Alliant is a standout in the crowd. Because they belong to their members, their mission often centers on providing better perks and better rates. Their high-yield accounts are an excellent place to let your savings grow.
This member-focused philosophy often leads to much lower fees than the massive national banks. While they are titans in the savings and certificate sectors, their loans are part of a much larger, integrated system. They are perfect for those wanting their money to work a little harder for them.
For the borrower aiming to build wealth while tackling existing debt, Alliant offers a holistic financial path. It is a savvy move for those who want to stay within a community-focused environment. You get top-notch credit tools alongside some of the best savings options available.
Pros:
- A member-owned model that often yields better rates.
- Attractive high-yield checking and savings accounts.
- Top-tier improvements to their digital banking tools.
Cons:
- You may need to meet specific membership requirements.
The Price of Extending Your Repayment Period
Choosing to stretch your debt over a decade or more is like trading your future wealth for immediate breathing room. While your monthly budget might feel lighter, the long-term mathematical toll is significant. You aren’t just paying back what you borrowed; you are essentially buying time with very expensive currency.
Let’s look at a practical scenario involving a $20,000 loan. If you opt for a 5-year timeline at a 10% interest rate, the total interest cost settles at around $5,500. It is a straightforward transaction where the cost of the money is clearly defined and manageable.
However, if you decide to push that same $20,000 debt out to a 10-year horizon at that same 10% rate, the math changes drastically. You end up shelling out roughly $11,700 in interest. You have doubled your monthly liquidity, yet the total expense has more than doubled as well.
It is crucial to grasp the “Effective Cost of Borrowing” before signing the dotted line. Without this perspective, you might find yourself blindsided by the sheer scale of what you owe. Many borrowers realize too late that their “affordable” loan is actually an expensive trap.
Keep a sharp eye on these specific financial pitfalls:
- Setup Charges: Many institutions deduct a percentage—usually between 1% and 8%—directly from your loan disbursement to cover administrative costs. This means if you borrow $10,000, you might only see $9,500 in your bank account, despite owing the full amount.
- Early Settlement Fees: Some contracts contain sneaky clauses that penalize you for being responsible. If you try to pay the debt off ahead of schedule, lenders may charge a fee to recoup the interest they expected to earn from you. Seek out “penalty-free” options instead.
- Delayed Payments and Interest Cycles: Over a long 12-year window, life happens. If you miss a payment, you might trigger compounding interest, where you are effectively paying interest on top of interest. This can cause your principal balance to stagnate or even climb higher.
How to Navigate Long-Term Borrowing
Before you sign on the dotted line, you must realize that a twelve-year loan is a massive commitment. While the monthly payments might look tiny, the total interest you pay over a decade can be staggering. It is like a marathon; you need to ensure you have the stamina to keep running for the full duration.
Your income, career stability, and cost of living will all change over twelve years, and you must plan for that volatility. Avoid the temptation to take the longest term just because you can. A longer term reduces your immediate monthly burden, but it increases the total cost of the loan significantly. If you can afford to pay more each month, you will save thousands of dollars in the long run.
A common strategy is to take the long term to ensure you can always meet the minimum payment, but to aggressively pay extra whenever you receive a bonus, tax refund, or raise. This gives you the “safety net” of a low monthly requirement with the “wealth-building” benefit of a short-term loan. It is about having flexibility when things are tight and speed when you have extra cash.
Watch out for hidden fees that can sneak into the contract. Always ask about prepayment penalties. If you come into some extra cash and want to pay off the loan early, you don’t want the bank to punish you for being responsible. Always read the fine print before you let anyone access your bank account.
Specifically, look for the phrase “all payments are applied first to interest and then to principal”—this is standard, but you want to ensure you can make extra payments that go directly toward the principal balance. This is the fastest way to accelerate your path to debt freedom and stop the interest from eating your income.
