
Get Fast Cash with Bad Credit Loans New York Residents Can Access Today
Last updated: 2026-10-17
Navigating your finances within the five boroughs can feel like dodging taxis in a sudden downpour. When your credit score isn’t exactly stellar, locating a lender that won’t immediately slam the door can seem like an impossible feat. Between the relentless price of living in the city and those sudden, stomach-churning medical costs, cash is often needed yesterday.
This resource is crafted specifically for residents dealing with unforeseen costs who require dependable solutions. You shouldn’t find yourself trapped between a rock and a hard place by choosing between rent and predatory street-corner lenders. Balancing quick access to funds with reasonable rates is the ultimate way to keep your head above water in this frantic urban jungle.
Choosing your lender involves much more than a quick glance at the interest percentage. You must carefully weigh the velocity of the deposit against how much that debt will ultimately cost you. A cheap rate means nothing if the bank takes a fortnight to transfer funds while your landlord is knocking at the door.
On the flip side, a loan that arrives in a heartbeat might carry massive APRs that leave you drowning in repayments. We examine how these companies approach credit inquiries, their speed of fund distribution, and whether their contracts are crystal clear or riddled with fine-print surprises. We judge them based on how they function for real people in the city.
Our aim is to pierce through the flashy advertising to identify genuine financial tools. We focus on what actually works when life throws you a curveball. Use these insights to navigate your way toward a smarter financial future without the typical headaches.
- SkyOne
- United Finance
- JetzLoan
- Experian
- GreendayOnline
How These New York Loan Options Were Evaluated
The evaluation process focused on accessibility for individuals with less-than-perfect credit scores. We looked at whether a lender performs a hard credit pull during the initial inquiry phase. This matters because a hard pull can impact your score before you even know if you are approved. In a competitive market like New York, where credit utilization and score fluctuations are closely watched, a “soft pull” for quotes is a vital safeguard.
Speed of funding is also a massive factor for those in urgent situations. Whether it is a car repair needed to get to work or a sudden utility shut-off notice, time is of the essence. We prioritized lenders that move quickly without sacrificing the transparency of their terms. We wanted to see who actually gets money into your account when you need it most.
We also scrutinized the range of loan amounts available to ensure a variety of needs are met. A $500 loan might fix a broken appliance, but a $25,000 loan might be necessary to consolidate high-interest credit card debt that is stifling your monthly cash flow. We prioritized clarity regarding repayment terms to ensure the lenders listed provide a genuine service rather than a debt trap.
We specifically looked for indicators of “predatory lending,” such as excessive origination fees that are tacked onto the principal. We also checked for a lack of clarity regarding the total cost of credit over the life of the loan. If a lender hides the real cost behind fine print, they didn’t make our list.
| Lender Name | Loan Amounts | Funding Speed | Credit Requirement |
|---|---|---|---|
| SkyOne | $500 – $50,000 | see site | Personal Loans available |
| United Finance | see site | see site | Installment loans available |
| JetzLoan | $500 – $35,000 | As little as 24 hours | No hard credit pull |
| Experian | $2,000 – $50,000 | Same-day funding available | see site |
| GreendayOnline | $100 – $5,000 | As soon as the same day | Bad credit welcome |
Top-Rated Lending Providers for Your Needs
1. SkyOne
Operating as a federal credit union, SkyOne brings a more human touch to the world of personal finance. Instead of relying solely on cold, automated rejection algorithms common in big banks, they treat members with a holistic perspective. This community-centric approach often opens doors that traditional commercial lenders might slam shut.
Whether you need a personal loan or a flexible line of credit, their products act as a vital lifeline. Many clients use these funds to steady their shaky financial footing. If you are staring down a massive debt pile or planning a major home renovation, their limits reach as high as $50,000.
The interest rates are quite refreshing, starting as low as 13.99% APR. When you compare that to the predatory rates on high-interest credit cards, it feels like a breath of fresh air. This makes them an excellent choice for funding significant life milestones, such as a new vehicle down payment.
Choosing this institution means opting for a collaborative partnership rather than an impersonal transaction. They are a rock for those chasing long-term stability. If you want a lender that feels like a neighbor rather than a giant corporation, this is your best bet.
Pros:
- Personal loan APRs begin at a competitive 13.99%.
- Borrow up to a maximum of $50,000.
- Provides flexibility through both loans and lines of credit.
Cons:
- You may need to meet specific credit union membership criteria.
2. United Finance
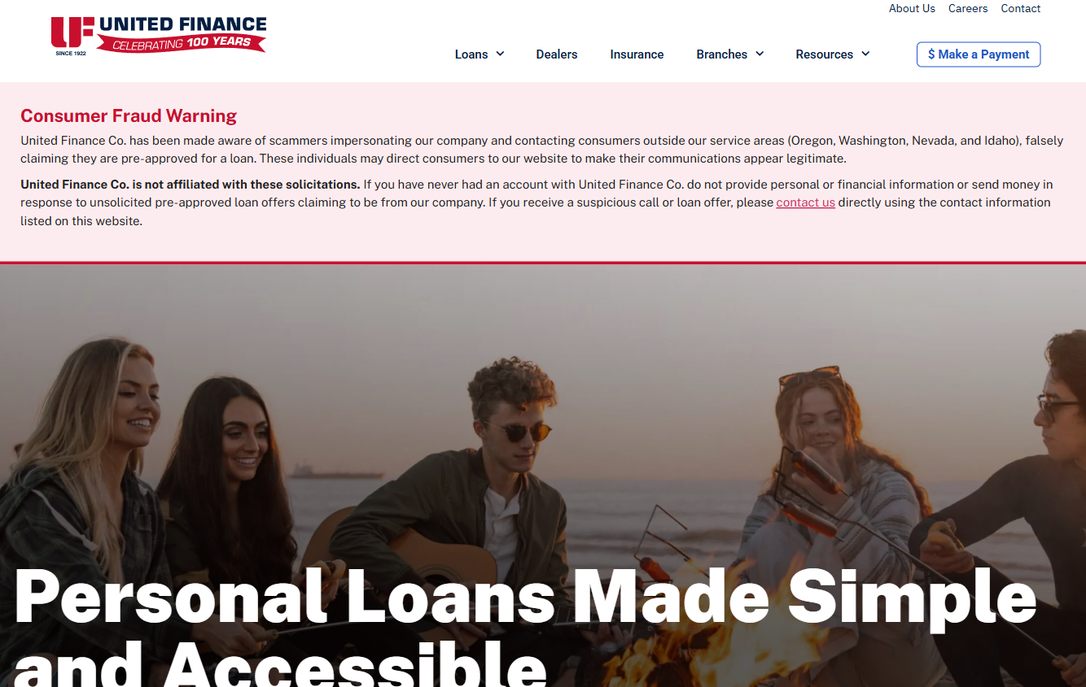
Since 1922, United Finance has been a cornerstone of the lending industry, bringing a century of wisdom to every application. They focus heavily on installment loans, which offer a predictable rhythm for your repayments. Unlike the chaotic cycle of payday loans, these fixed payments of principal and interest make budgeting a breeze.
This structure is a total departure from revolving debt. With payday loans, interest can snowball so fast that you feel like you are running on a treadmill that never stops. United Finance emphasizes ethical practices, frequently warning consumers about scammers attempting to steal their identity by mimicking their brand.
This commitment to security is a godsend for New Yorkers who are constantly dodging predatory phishing texts or emails. Their long history means they have survived countless economic storms. That institutional stability is something many newer fintech startups simply cannot claim to offer.
If you want a traditional, dependable lending experience, they are a very solid choice. You get the peace of mind that comes with knowing exactly what your monthly obligation will be. It is a steady hand in an unpredictable financial world.
Pros:
- Boasts a massive reputation built since 1922.
- Prioritizes installment loans over high-risk payday options.
- Maintains a fierce stance on fraud prevention and consumer security.
Cons:
- Availability is restricted to certain states, including Nevada and Oregon.
3. JetzLoan
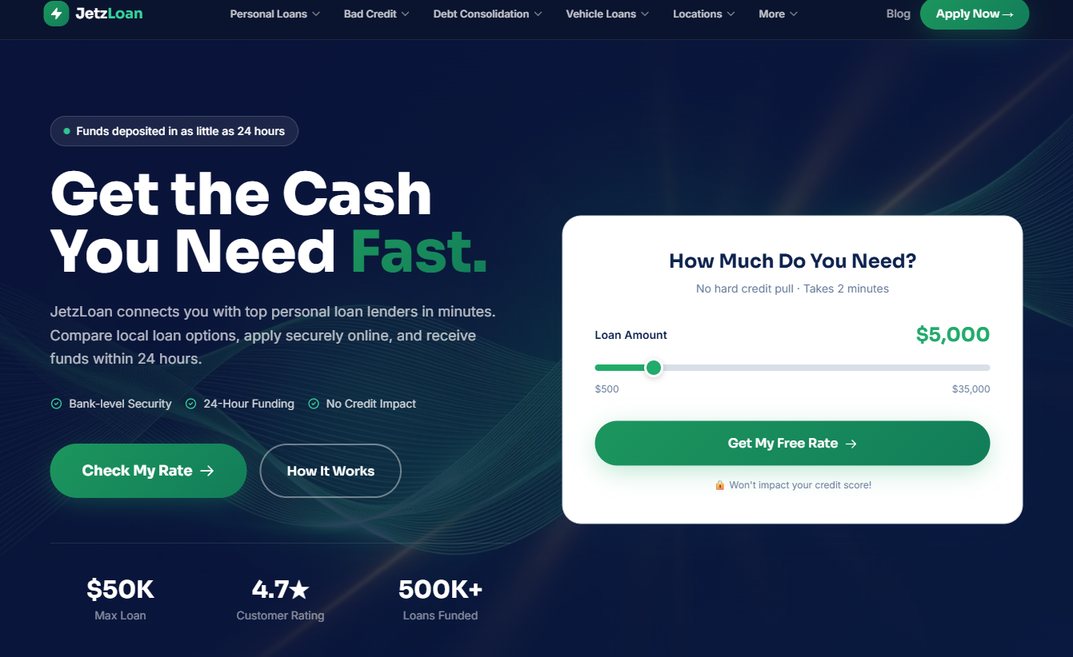
When you are in a tight spot and need cash yesterday, JetzLoan is the fast lane. They specialize in bridging the gap between you and top-tier lenders in mere minutes. The real magic here is their ability to let you check your rate without a hard credit pull.
This “pre-qualification” step is a total game-changer for your credit score. Most people walk on eggshells, fearing that every application will cause a nasty dip in their rating. With JetzLoan, you can window-shop for the best terms while keeping your credit report perfectly intact.
Forget about the mountain of paperwork found at a dusty brick-and-mortar bank. Their digital setup is built for the modern, frantic lifestyle. You can whip through the two-minute application while riding the subway or waiting for coffee. It is streamlined for ultimate efficiency.
If you are in a rush, this is your go-to solution. Funds can land in your bank account in as little as 24 hours. For those who simply cannot afford to wait for the slow-moving gears of traditional banking, this speed is a lifesaver.
Pros:
- Initial rate checks do not require a hard credit pull.
- Rapid funding, with many seeing cash in 24 hours.
- A lightning-fast, two-minute application process.
Cons:
- Total borrowing is capped at $35,000.
4. Experian
Experian is a household name when it comes to the science of credit, and their loan offerings reflect that deep-seated expertise. They understand the complex math behind your score better than just about anyone. They provide personal loans from $2,000 all the way up to $50,000.
Flexibility is their middle name, with repayment windows ranging from 24 to 72 months. This is a massive advantage if you are trying to balance a tight monthly budget. While a longer term lowers your monthly payment, remember it does mean you pay more in total interest over time.
They are a powerhouse for anyone looking to rehabilitate their financial standing. By utilizing their specialized credit-boosting tools—which can report on rent or utility payments—you can actively work on your score. It is about working smarter, not harder, to improve your credit profile.
Think of it as a virtuous cycle for your wallet. You use a loan to clear a hurdle, then use Experian’s ecosystem to climb even higher. It is a way to take a temporary financial stumble and transform it into a long-term leap forward.
Pros:
- Certain loan types qualify for same-day funding.
- Repayment windows are flexible, lasting up to 72 months.
- Includes built-in tools designed to boost credit scores.
Cons:
- An increase in your score or loan approval is never a certainty.
5. GreendayOnline
GreendayOnline is built for those needing a quick, small injection of cash to cover a sudden gap. They provide installment loans between $100 and $5,000. This is a niche service tailored for those “oh no” moments where speed and ease are the only things that matter.
While this won’t help you tackle a massive mountain of debt, it is perfect for bridging the gap between paychecks. The entire journey happens online, which is incredibly convenient for a busy New Yorker on the move. They don’t shy away from applicants with bad credit.
Instead of a grueling, traditional application, they provide a straightforward path to quick cash. It is an essential fallback for anyone who has been stung by credit setbacks in the past. If you just need a little extra help to make it to next month, they are ready.
Pros:
- Very low entry point, with loans starting at just $100.
- Quick approvals and same-day cash availability.
- Specifically tailored to help those with bad credit.
Cons:
- The maximum loan amounts are quite small compared to other lenders.
Navigating Your Loan Choices: A Tactical Roadmap
Staring at a pile of different loan documents can feel like trying to solve a puzzle in the dark. Between the shifting numbers and varying deadlines, it is easy to get lost in the weeds. You need a clear strategy to separate the golden opportunities from the traps.
Instead of letting the data wash over you, try to slow down and dissect each offer piece by piece. Taking a methodical approach ensures you don’t sign away your financial peace of mind just to get a quick fix. Here is how to stay ahead of the game.
Think of it as a checklist for your wallet. By looking at the fine print through a different lens, you can find the terms that actually suit your life. Don’t just take the first handshake you’re offered; make sure the math actually adds up in your favor.
- Prioritize the APR Over Interest Rates: It is a common trap to only watch the interest rate, but that only tells half the story. While that number represents the cost of the principal, the Annual Percentage Rate (APR) is the real truth because it incorporates extra costs like processing or origination fees. Always use the APR to weigh one deal against another.
- Identify Your Hard Budget Ceiling: Before you dive into a contract, take a hard look at your monthly cash flow. If your budget only has room for a $150 increase each month, steer clear of a deal requiring a $200 installment, even if the interest looks tiny. Don’t let a “good” rate push you into a deficit.
- Scan for Early Repayment Fees: Some companies will punish you for being responsible by charging prepayment penalties if you settle your debt early. If you are anticipating a windfall like a tax return or a work bonus, ensure your chosen loan allows you to clear the balance ahead of schedule without any extra costs.
- Confirm the Exact Payout Schedule: In a crisis, timing is everything, so don’t settle for vague promises. Ask the lender, “When exactly will the cash be sitting in my bank account and ready for use?” Remember that being officially “approved” is quite a different beast than having the actual funds cleared and ready.
Navigating the Hidden Traps of the New York Credit Landscape
Trying to find a loan in the concrete jungle can feel like walking through a minefield of fine print. Many lenders in the city use high-pressure psychological plays to force a quick signature. They might bombard your phone with incessant calls or use scare tactics, claiming you will miss out on funds if you do not act instantly.
A legitimate company won’t try to corner you like a street hustler. Instead, they maintain a professional demeanor and grant you the space to review every clause. If someone is shouting about your “final opportunity” to secure cash, take a step back. It is often a red flag rather than a genuine offer.
One dangerous habit that many New Yorkers fall into is the cycle of “loan stacking.” This is essentially playing a high-stakes game of musical chairs with your debt. You take a new, expensive loan to settle an old one, thinking you have found a way out of the woods.
In reality, you are merely shifting the weight of your debt around while the interest rates continue to snowball. It feels like a temporary fix, but it is actually a recipe for a financial disaster. If your strategy involves borrowing more to pay off what you already owe, stop immediately and reach out to a debt counselor.
Finally, do not let a slick website fool you into thinking an online lender is trustworthy. A beautiful, modern interface is nothing more than digital window dressing. It is the bare minimum requirement for any business operating in the modern age.
You must dig a little deeper to ensure they are actually registered to work within New York state regulations. Check for a verifiable physical office and hunt for authentic feedback from past customers. True stability is found in a long-standing reputation and absolute transparency, not just a pretty web design.
Making Smarter Choices with Your Credit
Before you ink your signature on any contract, try to slow down and catch your breath. The rush of getting a fast “yes” can feel like a shot of adrenaline, but you need to keep a cool head. It is vital to scrutinize the true price of every cent you borrow.
Don’t let the shiny numbers on the advertisement fool you. You should always demand clarity regarding any hidden costs, such as prepayment penalties or origination fees. These sneaky additions can make a loan much pricier than it initially appeared to be.
For instance, imagine you secure a $1,000 loan, but the lender demands $100 in upfront fees just to hand over the cash. In reality, that money is far more expensive than the interest rate suggests on paper. Always look past the surface level to see the real financial impact.
Resist the urge to grab several tiny loans from various lenders just to settle one massive debt. This approach is a slippery slope that often leads to a financial tailspin from which it is incredibly hard to climb out. It’s like trying to put out a fire by throwing more gasoline on it.
Whenever you can, aim to bundle your various debts into a single, consistent monthly installment. This strategy keeps your household budget predictable and prevents your stress from skyrocketing. It is much better to handle one clear obligation than to juggle a messy pile of different due dates and fluctuating rates.
