
Best Ways to Secure Land Loans for Bad Credit Online
Last updated: 2026-10-17
Locating the perfect plot of earth is frequently a breeze compared to securing the capital required to purchase it. Many folks chasing the dream of a tranquil wooded area or a rural sanctuary find their aspirations hitting a brick wall. Often, a bruised credit history stands in the way of those eager to settle down.
Big-name banks typically turn a blind eye when your score falls below specific thresholds. They might insist on upfront costs ranging from 20% to 30% of the total price. For most people buying their first piece of property, that amount of cash simply isn’t sitting in a bank account waiting to be spent.
From the perspective of a traditional lender, undeveloped ground is a gamble. Unlike a house, a vacant lot lacks a building to act as security if you can’t pay the debt back. This reality turns the quest for financing into quite an uphill battle for the average seeker.
You essentially need to hunt for specialists who prioritize the worth of the terrain. These lenders care more about the potential of the soil than the numbers printed on a credit report. It takes a bit of luck and persistence to find someone willing to take that specific leap of faith.
This guide highlights several routes through those daunting economic obstacles. Whether your heart is set on a tiny garden, a weekend getaway, or a sprawling farm, knowing your choices is vital. You must also learn the distinction between “finished lot” sites with utilities and “raw land” that lacks any infrastructure.
Getting these details straight is the best way to find the right money source. Understanding what you are actually buying will help you navigate the complex landscape of property financing. Take a look at these top contenders for your next big investment.
- Acorn Finance
- JetzLoan
- LightStream
- Country Bank
- Lendersa
- USDA
Our Methodology for Comparing Financing Choices
When we sat down to vet these options, our main goal was determining who would actually answer the door for various credit scores. It is a bit like shopping for shoes; not every brand is designed for every foot. You must grasp the massive chasm between a simple personal loan, a high-interest hard money setup, and federal assistance schemes.
Choosing a provider for a quick cash boost is a different beast than seeking a permanent mortgage. While a personal loan acts like a sprint, offering rapid capital, you will likely pay a premium through elevated interest rates compared to a standard mortgage tied to the land itself.
On the flip side, conventional bank financing can be a slow turtle, often taking up to 45 days to reach the finish line. In that agonizing wait, your ideal plot of dirt might slip through your fingers to a more aggressive buyer. We also weighed the velocity of capital against the fallout of credit inquiries.
Some firms permit you to scout rates through a “soft pull,” which leaves no scar on your score. This is a total lifesaver when you are trying to gauge your financial reach before making a serious move. We kept our eyes glued to transparency throughout this entire investigative journey.
Our team scrutinized how fast money hits your account and how many hoops you must jump through during the paperwork phase. We dug into the specific collateral demanded for each transaction. Understanding whether an inquiry is a “hard pull” or a mere “soft” informational glance can make or break your monthly budget.
| Provider | Maximum Limit | Payout Velocity | Score Criteria | Primary Use Case |
|---|---|---|---|---|
| Acorn Finance | Check website | Check website | Fair to Poor Scores | Renovations/Contracting |
| JetzLoan | $50,000 | Within 1 day | Soft Inquiry Only | Rapid Liquidity/Debt Management |
| LightStream | $100,000 | Check website | Prime to Superb | Premier Credit Profiles |
| Country Bank | Check website | 60 Day Fixed Rate | Based on Review | Unimproved Lots/Acreage |
| Lendersa | Check website | Quick Turnaround | Variable (Private Capital) | Property Flippers/Real Estate Pros |
| USDA | Check website | Check website | Variable | Countryside Living/Residences |
Top Rated Land Financing Providers
1. Acorn Finance
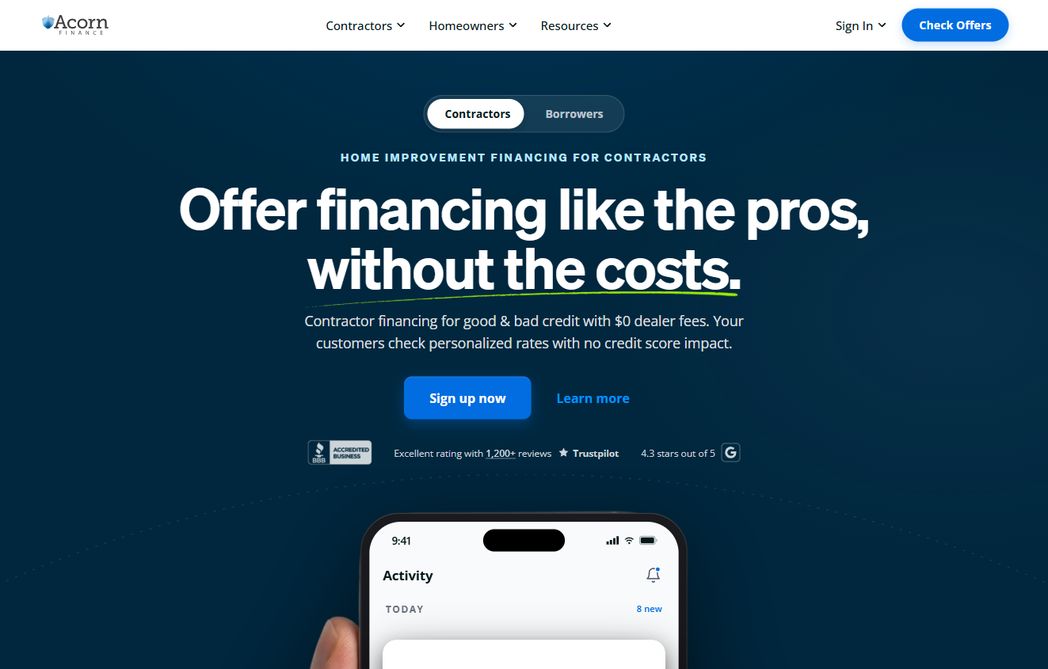
Think of Acorn Finance as a specialized intermediary that connects you to a vast network of financing sources. One of their standout features is the complete absence of dealer fees, which helps you avoid those sneaky costs that often inflate total debt. It is a refreshing change in a market where service charges can unexpectedly drive up your costs.
This service is a perfect match if you are looking to buy acreage and immediately start working on it. If you need to clear brush or lay down a new driveway right away, this flexibility is gold. They bridge the gap between acquiring the dirt and making it habitable.
For those struggling with less-than-perfect credit history, this provider is a lifeline. Unlike big banks that might turn you away based on a single score, Acorn Finance links you with specialists who look at the bigger picture. This increases your chances of finding a lender who says “yes” even when your FICO might say “no.”
It is a smart, versatile choice for modern property seekers. Instead of hitting a brick wall of rejections, you are being matched with people who understand your unique financial journey. It is all about finding a partner that works for your specific situation.
Pros:- $0 dealer fees for contractors and borrowers
- Personalized rates with no credit score impact during checking
- High customer satisfaction with 4.3 stars on Trustpilot
- May not offer the lowest rates compared to prime lenders
2. JetzLoan
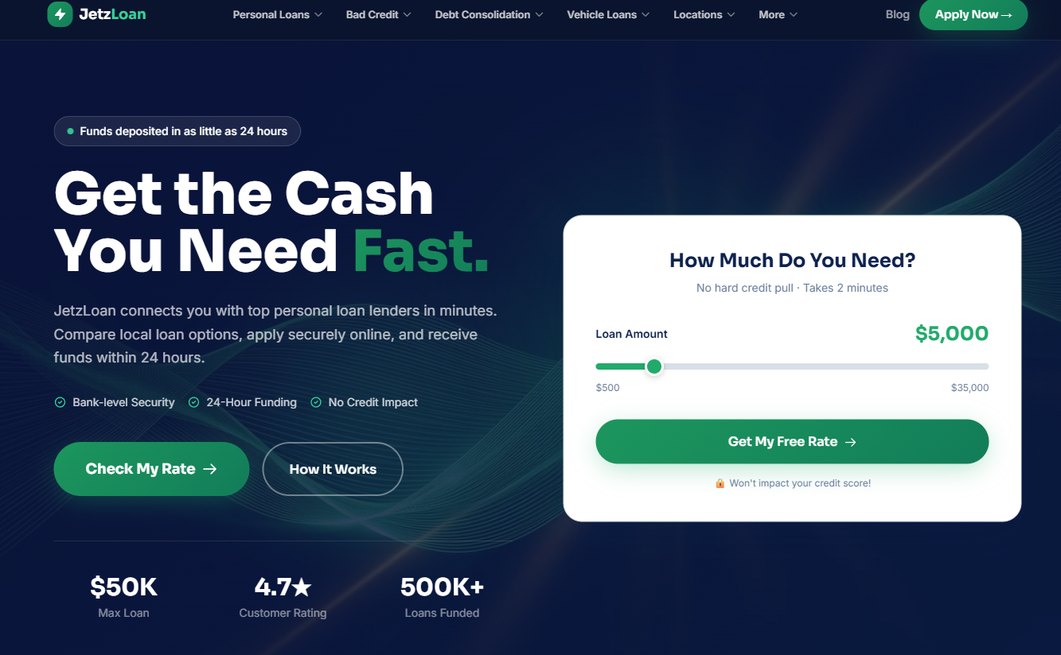
When a real estate deal moves at lightning speed, JetzLoan is often the first call to make. They have the incredible ability to get cash into your hands in as little as 24 hours. This makes them a vital tool for urgent acquisitions or when you need to consolidate debts quickly.
In a hot market, having cash on hand is like having a golden ticket. Sellers often favor “cash offers” because they skip the long, drawn-out inspections and appraisals that traditional banks require. This speed can be the deciding factor in winning a property auction or a competitive bidding war.
The application itself is a breeze, taking roughly two minutes to finish. This is ideal for the shopper who spots a perfect lot on a weekend and needs to prove they are a serious buyer immediately. You can explore your options without the fear of damaging your credit score.
By allowing you to check rates without a hard credit pull, they protect your financial standing while you shop. It is a high-octane solution for anyone living in a fast-moving real estate landscape. If you need to act now, this is your best bet.
Pros:- Funding in as little as 24 hours
- No hard credit pull to check rates
- High loan limits up to $50,000
- Limited to personal loan structures rather than traditional land mortgages
3. LightStream
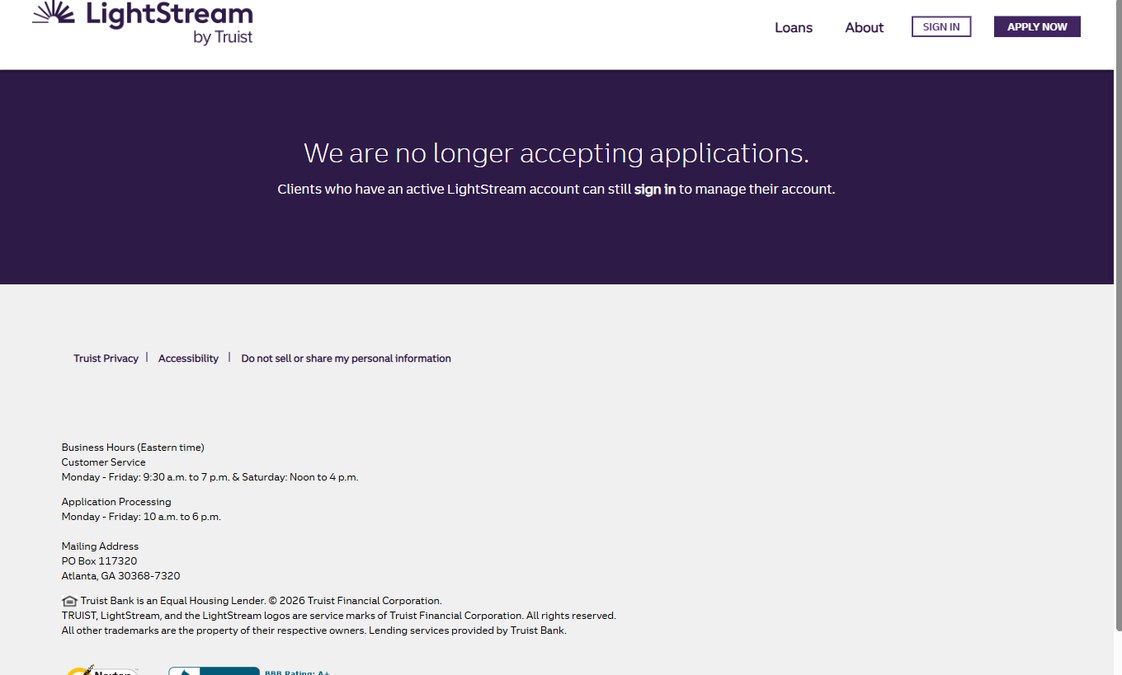
LightStream operates on an entirely different level than the others. This is the premier choice for individuals who have successfully navigated their way to a high credit standing. They offer incredibly competitive, fixed interest rates that are hard to find elsewhere if your profile is excellent.
If you crave stability, this is the place to be. You can lock in your interest rate and know exactly what your monthly obligations look like for the entire life of the loan. It takes the guesswork out of your long-term financial planning, providing peace of mind.
With loan amounts reaching up to $100,000, you have plenty of capital for large land purchases or even subdividing a massive plot. However, if your credit is currently in the “bad” category, you will likely find these doors firmly shut. Their automated systems prioritize those with impeccable FICO scores and consistent income.
This is a top-tier destination for those who want to avoid the high costs of subprime financing. If your financial house is in perfect order, LightStream offers one of the smoothest paths to property ownership. It is efficient, predictable, and highly professional.
Pros:- Low fixed interest rates
- Loan amounts up to $100,000
- Highly reputable through Truist
- Requires good to excellent credit; not for bad credit
4. Country Bank
Country Bank brings a localized, community-driven spirit to the lending world. As an FDIC-insured institution, they provide a level of security and personal touch that massive national banks often lack. They possess a deep understanding of land that purely digital lenders simply cannot replicate.
While a giant bank might see a lot without paved road access as a high risk, this bank sees the local potential. They understand regional zoning laws and the unique value of specific geographic areas. They look at the land through the eyes of a neighbor, not just a spreadsheet.
A standout perk of their service is the ability to lock in your rate for 60 days. This is a massive advantage when navigating a volatile market. It gives you the breathing room to hire surveyors or architects without worrying about sudden interest rate spikes.
Whether you are looking at raw land or a site ready for construction, they offer customized financing. They recognize that the risks for these two types of property are worlds apart. It is an ideal choice for someone looking to build a long-term banking relationship.
Pros:- 60-day rate lock availability
- FDIC-insured security
- Offers financing for both raw and buildable land
- Standard bank approval processes can be rigorous
5. Lendersa
Lendersa is tailor-made for the aggressive investor who refuses to slow down. By utilizing advanced AI, they match borrowers with an extensive network of private investors and hard money lenders. This technology is optimized to ensure the fastest closing times possible for their clients.
This is a high-energy option perfect for real estate pros focusing on land flipping or quick developments. While a traditional bank might spend weeks verifying a survey, the Lendersa network is built for rapid movement. They focus on getting you from “offer” to “closed” in mere days.
If you are hunting for deals at auctions or in fast-paced “fix and flip” scenarios, this is your best ally. In a market where every second counts, they help you beat the competition to the finish line. Their reach covers both commercial and residential properties alike.
It is important to note that these terms often differ significantly from a standard mortgage. While you might pay a premium for this incredible speed, professional investors find the rapid turnaround worth the cost. It is all about how quickly you can cycle your capital.
Pros:- Uses AI to match lenders and optimize rates
- Designed for fast closing and auctions
- Covers residential and commercial property types
- Hard money terms can be much more expensive than traditional loans
6. USDA
The USDA serves as a government-supported pillar of support for rural development. Their mission is to fuel the growth of the country’s countryside by providing essential loans and grants. They want to help people build, buy, or mend homes in specific rural stretches of America.
This is a beautiful opportunity for anyone dreaming of a rural lifestyle and a fresh start. These programs are specifically designed to bolster local economies. They help families establish deep roots in areas they might have otherwise been priced out of due to low down payments.
While the paperwork can be a bit more involved and location requirements are strict, the rewards are substantial. This isn’t just a profit-driven enterprise; it is a program designed to serve the people. If you qualify, it is a powerhouse for achieving homeownership.
It is a mission-driven path for homesteaders and families looking for stability. By lowering the barriers to entry in rural areas, the USDA helps keep the heart of the country thriving. If you fit the mold, this is a wonderful way to secure your future.
Pros:- Government-backed stability and support
- Focuses on rural economic development
- Offers various programs including grants and loans
- Strict geographic requirements for eligibility
Differentiating Between Real Estate and Raw Acreage
Before you dive into the paperwork, you must grasp how banks perceive the difference between a structure and a plot of dirt. Think of it like a safety net. When you secure a mortgage for a home, the physical residence serves as collateral. If you hit a rough patch and default, the bank simply sells the dwelling to get their cash back.
However, land is a different beast entirely. With a vacant lot, the only security is the soil itself. If the local real estate market takes a sudden nosedive, that dirt might end up being worth much less than the original loan amount. This creates a significant headache for lenders, as their fallback option is far less liquid and reliable.
Because the stakes are much higher, the requirements for land financing can feel like an uphill battle. You won’t find the same lenient terms used for suburban homes. Instead, you might find yourself digging deep into your savings to meet much steeper upfront requirements.
Expect to shell out a significantly larger chunk of change upfront. For raw land, down payments frequently range from 20% to 50% of the total value. Furthermore, the interest rates on these loans typically climb much higher than those of standard residential mortgages. It is a steep price to pay for the flexibility of building your own way.
Lenders will also scrutinize your property with a magnifying glass. They will demand exhaustive proof regarding utility access, legal easements, and how you plan to reach the site. If you happen to be working with a hard money lender, you might even be squeezed into a short-term repayment schedule.
Navigating the Path to Your New Acreage
Buying raw earth feels like a dream until you realize you’ve purchased a beautiful island in a sea of thicket. To avoid the heartbreak of an unusable plot, you must be a detective during your initial investigation. Don’t just fall in love with the sunset; look beneath the surface of the deal.
First, you must confirm how you will actually reach your front door. A dusty trail through a neighbor’s yard might look inviting, but without a formal legal right-of-way, that path is nothing more than a polite suggestion. Without guaranteed legal access to a public street, most banks will refuse to fund the project, leaving you stranded.
Next, consider the invisible necessities that make a site livable. If you intend to build a home, you’ll need a “perc test” to see if the earth can handle a septic system. Bad drainage can turn a dream into a money pit overnight. Also, keep a close eye on utility connections. Bringing electricity to a remote site can easily drain tens of thousands of dollars from your bank account.
Don’t assume the local laws will allow your vision to come to life just because the area feels wild. Zoning laws are the silent gatekeepers of every community. You need to scrutinize local ordinances to understand the rules regarding setbacks, the minimum amount of land required for a build, and whether you are allowed to keep livestock or specific outbuildings on the property.
Finally, never trust a boundary marked by a leaning fence or a neighbor’s casual word. Handshake agreements are worth very little when it comes to legal property lines. To ensure the acreage you are paying for matches the actual dirt on the ground, you must hire a professional to perform a formal survey.
Finding the right financier is a journey, not a race, and the “best” option depends entirely on your specific goals. If you are a fast-moving investor who needs to close a deal yesterday, a hard money lender like Lendersa might be your savior, despite the steeper interest rates. However, a permanent resident might find more peace of mind through a traditional bank or a USDA program.
A massive pitfall for many buyers is ignoring the “hidden” price tag attached to raw dirt. Unlike a finished house, a piece of land often requires an immediate infusion of cash for roads, water, and power. Make sure your loan covers these infrastructure necessities. If you spend every penny on the purchase price, you might end up owning a gorgeous view that you can never actually reach.
Keep a watchful eye on your credit score while you shop around for terms. Using services like Acorn Finance or JetzLoan can be a lifesaver because they offer rate checks that won’t dent your credit score. In the high-stakes world of land acquisition, being well-informed is your greatest asset. Do your homework thoroughly to ensure your financing aligns with your future life on the land.
