
Top Rated Loans for Uber Drivers with Bad Credit to Keep You Moving
Last updated: 2026-10-17
Navigating the gig economy often feels like walking a tightrope during a storm. You might enjoy a week of lucrative surge pricing, only to have a sudden mechanical breakdown eat your entire take-home pay. For those behind the wheel, a low credit score shouldn’t act as a roadblock to the capital required to keep your vehicle running.
The grind is inherently erratic. Between shifting app algorithms, the constant rise of fuel costs, and the inevitable high-mileage maintenance bills, your finances don’t follow a straight line. You are essentially operating a small, mobile enterprise rather than just driving a car from point A to point B.
Standard employment looks nothing like the fluctuating income of a rideshare veteran. When an emergency hits, you aren’t searching for a perfect credit history; you are hunting for rapid relief. You need a partner that recognizes your earnings come from the road, not a predictable bi-weekly deposit.
Traditional lenders often stumble when they see your ledger. They might demand two years of tax documentation or proof of a single, permanent boss. To a big-name bank, a paycheck that jumps from $2,000 down to $800 looks like a red flag. They see instability where a specialized lender sees a consistent, high-frequency earner.
Because of this, we have curated a selection focused on quick turnaround times and ease of use. We prioritized lenders that actually grasp the unique lifestyle of a gig worker. The following options are chosen specifically for their accessibility and speed in a high-stakes environment.
- JetzLoan
- Giggle Finance
- Ualett
- Credit Ninja
Our Assessment Methodology
Speed of disbursement was our primary metric. For anyone behind the wheel, a mechanical failure isn’t merely a headache; it acts as a complete roadblock to your livelihood. If your sedan is stuck at a shop for nearly a week while a lender deliberates, you are effectively hemorrhaging money through both the repair bill and lost weekly wages.
We actively hunted for providers that prevent an emergency from becoming a financial disaster. Our goal was to find services capable of closing the distance between a sudden vehicle breakdown and your next scheduled earnings deposit. We prioritized those who act as a lifeline when the engine stops running.
We also gave significant weight to companies that won’t penalize you for comparing different offers. When your credit score is already on thin ice, “browsing” for the best terms can be a dangerous game. Every time a firm initiates a “hard pull” on your history, your rating may take a hit.
For many, a minor decrease in points might be the deciding factor between securing a favorable rate or facing a flat rejection. We specifically sought out firms that offer a “soft pull” option. This allows you to investigate your options without risking your precious standing with the bureaus.
The ease of the sign-up journey was the final piece of our puzzle. Drivers simply do not have the luxury of wasting hours hunched over piles of paperwork. We looked for platforms designed for mobile use that allow for instant digital document sharing.
Ideally, you should be able to navigate your banking needs right from your smartphone. Managing your cash flow should be as simple as accepting your next trip while sitting in the driver’s seat waiting for a fare.
| Provider | Highest Principal | Payout Velocity | Score Effect |
|---|---|---|---|
| JetzLoan | $50,000 | Less than 1 day | No hard credit pull |
| Giggle Finance | $15,000 | Incredibly fast | See site |
| Ualett | See site | Rapidly | See site |
| Credit Ninja | See site | Decision within one day | No impact on score |
Leading Financing Options for Freelance Drivers
1. JetzLoan
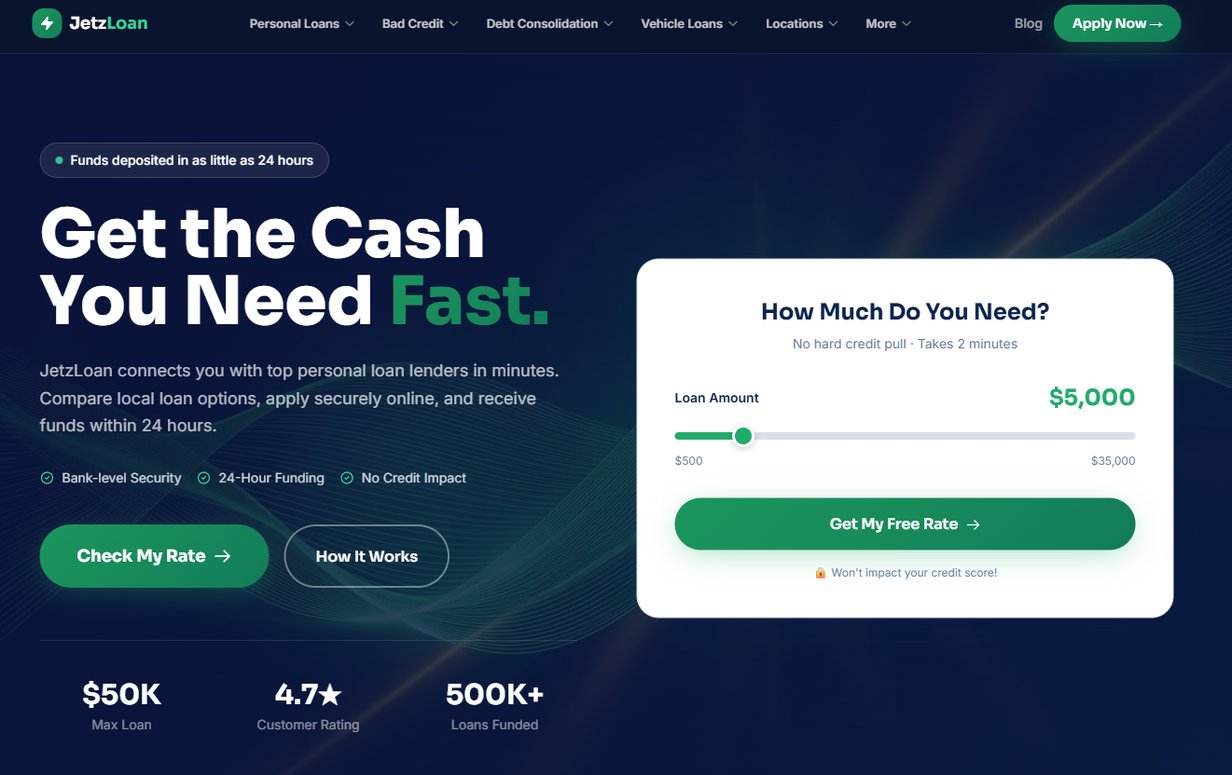
Think of JetzLoan as a financial bridge that spans the gap during emergencies. It is a total lifesaver when your car needs a massive overhaul or a sudden engine replacement. It can even help you upgrade to a newer vehicle to stay compliant with app requirements.
Rather than wasting time hitting up a dozen different banks, JetzLoan acts as your personal scout. They connect you with an expansive network of various top lenders to find the perfect match. This variety ensures you aren’t stuck with just one option.
If you are looking to consolidate high-interest debt—like a credit card used for an old repair—this is a stellar choice. You can even secure a significant vehicle loan this way. The best part? You can check potential terms without a hard credit pull.
This “soft” check means you can gauge if the monthly installments fit your weekly take-home pay without hurting your score. It is a smart way to shop for better terms while you focus on rebuilding your financial foundation.
Pros:
- Borrow as much as $50,000 through high maximum loan amounts.
- Get your money in a flash, frequently within 24 hours.
- Check rates without a hard credit pull to protect your score.
Cons:
- Because they match you with a network, your interest rates can fluctuate depending on the specific lenders available.
2. Giggle Finance
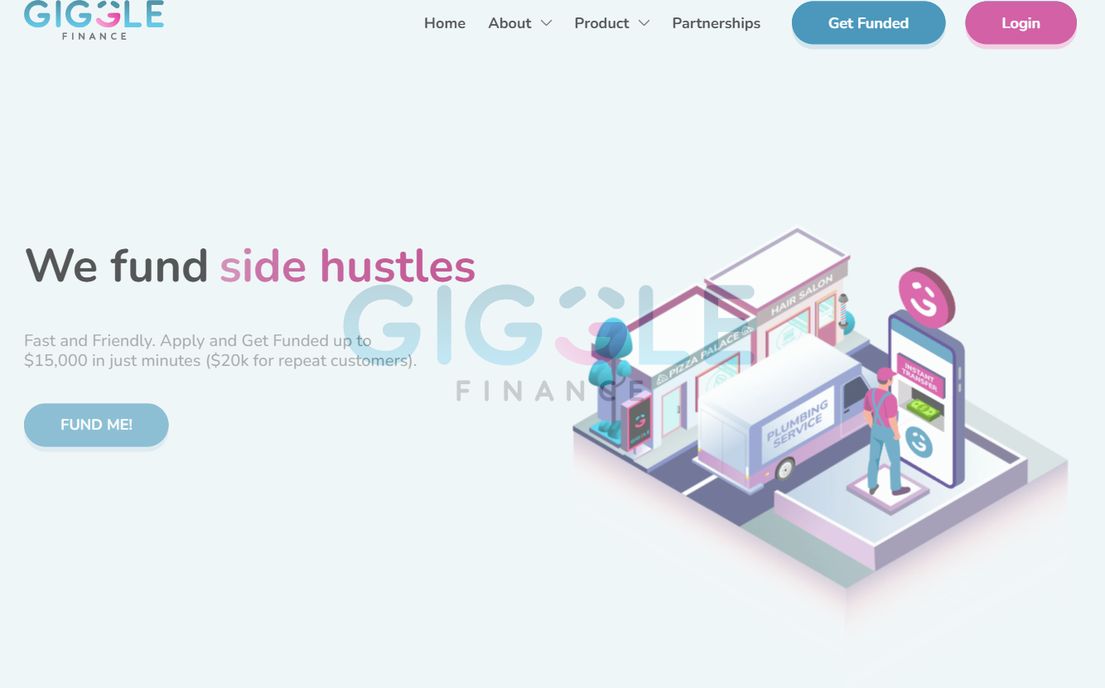
Giggle Finance was tailor-made for the 1099 worker. They look beyond just a single credit score, focusing instead on the actual reality of your side hustle. They know that your income isn’t a simple W-2 line item from one employer.
Instead, they understand that your money comes from a messy, beautiful patchwork of Uber, Lyft, Instacart, or DoorDash deposits. This perspective makes them a premier choice for drivers who need cash almost instantly to keep their wheels turning.
Speed is the name of the game here, with funds potentially hitting your account in a matter of minutes. It is a specialized tool built to navigate the irregular income patterns that often spook traditional banks. It treats your fluctuating cash flow as normal, not risky.
If a dead battery or a worn-out set of tires threatens your next shift, Giggle Finance provides that quick liquidity. They help you get back on the road before you even lose a single hour of work.
Pros:
- Lightning-fast funding that sometimes arrives within minutes.
- Built specifically for self-employed and 1099 workers.
- Loyal repeat customers can unlock higher limits up to $20,000.
Cons:
- The borrowing limits are lower than many major personal loan companies, which might not work for massive expenses.
3. Ualett
Ualett operates more like a convenient cash advance than a standard, long-term loan. This setup is a total game-changer for drivers navigating the “ups and downs” of a variable weekly paycheck. It offers a financial cushion that actually respects your workflow.
Life isn’t always a straight line, and neither is your income. If you’ve had a high-earning week but need cash right now for a utility bill or an insurance premium, Ualett fills that gap perfectly. It turns your future earnings into immediate cash in your pocket.
You won’t have to sweat over rigid repayment schedules that fall apart if you have to take a sick day. This flexibility is vital for anyone living week-to-week. It’s a digital-first solution designed to keep your cash flow moving smoothly.
It serves as a fantastic companion app for those who need to manage day-to-day expenses without the heavy weight of traditional debt structures. It is all about keeping you liquid when you need it most.
Pros:
- Custom-built for the unpredictable income of the gig economy.
- Focuses on quick cash advances rather than heavy debt.
- An easy, integrated app-based experience for modern users.
Cons:
- You likely won’t get the massive lump sums required for big investments like a second car.
4. Credit Ninja
If you want a simple, no-nonsense online loan experience, Credit Ninja is a solid bet. When traditional banks shut their doors due to your credit history or your employment type, this service steps up. They focus on finding actual solutions for people who are often overlooked.
They act like an intelligent filter, scanning various lender criteria to find the most likely “yes” for your specific profile. It is less about the nuances of the “gig” life and more about finding a path to credit when the mainstream system fails.
The application process is incredibly snappy, often handing you a decision on the very same day. This makes it a very practical tool for covering those sudden, unexpected life costs. Whether it’s a household repair or a medical bill, you won’t be waiting days for an answer.
It is an efficient way to bypass the complex, multi-day approval hurdles found elsewhere. If you need an alternative route to funding, this service is ready to help you navigate the search.
Pros:
- Rapid decisions, often provided on the same day you apply.
- A straightforward and simple online application process.
- A vital resource for drivers denied by traditional lenders.
Cons:
- Getting approved isn’t a certainty and is subject to specific qualifying criteria.
Mastering Your Cash Flow on the Road
Landing a loan is merely the beginning of your journey; how you steer that debt determines whether you hit a dead end or reach your goals. For those navigating the gig economy, you must view your car and your bank account as one unified enterprise. Think of your vehicle as your most important employee.
Managing your liquidity requires a bit of grit and a lot of planning. You shouldn’t just wing it when it comes to your weekly earnings. Instead, treat your finances with the same precision you use to navigate through heavy city traffic during a rush hour.
Keeping your finances in check prevents a minor mechanical hiccup from becoming a total catastrophe. It is all about staying ahead of the curve. If you approach your money with a strategy, you can turn those high-earning shifts into lasting stability.
- Build a Safety Net: Whenever you catch a “surge” payout, try tucking a tiny slice of that extra cash into a high-yield savings account. Do not touch this for your afternoon snacks or trivial cravings. This serves as your dedicated “transmission fund” for unexpected repairs.
- Track Your Earnings:> Even with digital apps handling the heavy lifting, maintaining a secondary ledger of your weekly net profits is vital. Should you eventually seek a major loan for a fresh ride, presenting a neat spreadsheet that proves consistent monthly income will bolster your credibility.
- Analyze the True Cost of Borrowing: Before grabbing a cash advance, weigh the fee against the principal amount. For instance, if a $50 advance carries a $5 fee, you are paying 10% for a blink-of-an-eye loan. Ask yourself if the instant speed justifies that particular price tag.
- Snowball or Avalanche Methods: When using a loan to combine your debts, pick a battle plan. You can use the Snowball method by tackling the smallest balance first to build psychological momentum. Alternatively, the Avalanche approach targets the highest interest rate to minimize your total expenses.
Staying Clear of Money Traps
It is incredibly easy to lose your footing when your wallet feels light and your engine refuses to turn over. In those frantic moments, you might find yourself running straight into the arms of predatory lenders. These sharks offer lightning-fast cash, but they hide astronomical interest rates that act like a noose around your neck. They specifically hunt for folks facing high-pressure crises.
Before you ink your signature on any contract, you must scrutinize the final sum you will eventually pay back. If the total cost of the loan dwarfs the amount you actually receive, you should run for the hills. It is vital to weigh the true price of that quick fix before committing your future income to it.
Don’t let a pretty monthly payment schedule blind you to the reality of your fluctuating earnings. While a set amount might seem manageable during a peak season, it can feel like a crushing mountain during a quiet week or if a sudden illness keeps you off the road. Life rarely moves in a straight line, and your debt shouldn’t be rigid.
You should prioritize lenders that offer a bit of breathing room when things get bumpy. Look for options that allow you to pause a payment or shift your due dates if your driving hours drop. Having that flexibility is a lifesaver when the unexpected occurs and you need to keep your head above water.
At the end of the day, your capacity to generate income is your most powerful weapon. Even if your credit score is currently in the gutter, modern lenders are starting to care more about your hustle. They see the gold in your ability to put in another 20,000 miles of work behind the wheel.
Make it a habit to keep a meticulous paper trail of every dollar you earn from your gig work. Having organized proof of steady earnings can be the magic key that unlocks better interest rates and larger loan limits. Traditional banks often miss this potential, but smart lenders will see your value through your consistent hustle.
