
Top-Rated Options for a Personal Loan After Bankruptcy in 2026
Last updated: 2026-10-16
Navigating the financial landscape following a bankruptcy discharge can feel like wandering through a dense, blinding mist. You might find yourself facing a sudden, expensive mechanic’s bill just to keep your commute steady. Perhaps a medical emergency has arrived right as your legal discharge finalized.
Sometimes, the need is simply to fill a void caused by an abrupt job loss. Ultimately, your mission is to locate a creditor who prioritizes your future prospects over your historical errors. You want someone who values your current trajectory rather than dwelling on old wounds.
The landscape of personal borrowing has undergone a massive transformation lately. While a bankruptcy filing used to function as a permanent door slam, many community banks and fintech pioneers now scrutinize your recent habits. They are more interested in your current fiscal direction than the old scars on your credit profile.
It is not about where you have been, but where you are headed. Finding a suitable partner requires looking far beyond a simple interest percentage. You must evaluate the speed of funding, minimum eligibility criteria, and the level of adaptability the provider offers.
Some companies specialize in lightning-fast emergency funds, whereas others provide structured monthly payments designed to boost your credit score. It is a delicate dance between needing immediate liquidity and seeking enduring financial stability. Choosing a provider is a high-stakes balancing act.
Accessibility is a nuanced concept that varies wildly from person to person. A company that grants instant approval might demand a much higher price for that speed. Conversely, those with more rigorous standards might provide the low interest rates essential for managing long-term debt.
You must determine if you require a temporary Band-Aid or a comprehensive, long-term strategy. Every choice you make today will ripple into your financial future. Deciding between a quick fix and a slow, steady rebuild is the first step in your recovery.
- FastLendGo
- SoFi
- Prosper
- Avant
- Allegiance Credit Union
- VivaLoan
- World Finance
Selecting the Right Financing After Bankruptcy
Our assessment centers primarily on approval accessibility and the velocity of fund distribution. Financial crises rarely pause to wait for your credit profile to look pristine again. Life tends to throw curveballs when you least expect them, often requiring immediate liquid capital to keep your household running smoothly.
We specifically searched for institutions offering transparent routes for individuals with varied scoring backgrounds. If a forty-eight-hour delay in receiving funds means losing your electricity, a slow lender is a useless lender. Speed is often the difference between a minor hiccup and a genuine disaster.
Another vital factor involves the scope of borrowing options available to you. Some lenders specialize in tiny microloans, which won’t help if you are tackling a massive home repair or consolidating old debts. On the flip side, big-name banks usually demand high-tier scores or property as collateral.
We hunted for providers that utilize “soft” inquiries to protect your rating. This allows you to browse multiple options without causing unnecessary damage to your score. It’s a safety net that lets you shop around while you figure out your next move.
| Company | Borrowing Limits | Time to Fund | Scoring Needs |
|---|---|---|---|
| FastLendGo | $500 – $5,000+ | Rapidly | Bad/Fair/Good/Great |
| SoFi | see site | see site | see site |
| Prosper | $2,000 – $50,000 | Swiftly | see site |
| Avant | see site | see site | see site |
| Allegiance Credit Union | see site | see site | see site |
| VivaLoan | $100 – $15,000 | Next day possible | All credit types welcome |
| World Finance | see site | see site | see site |
Premier Lending Options for Restoring Your Credit Profile
1. FastLendGo
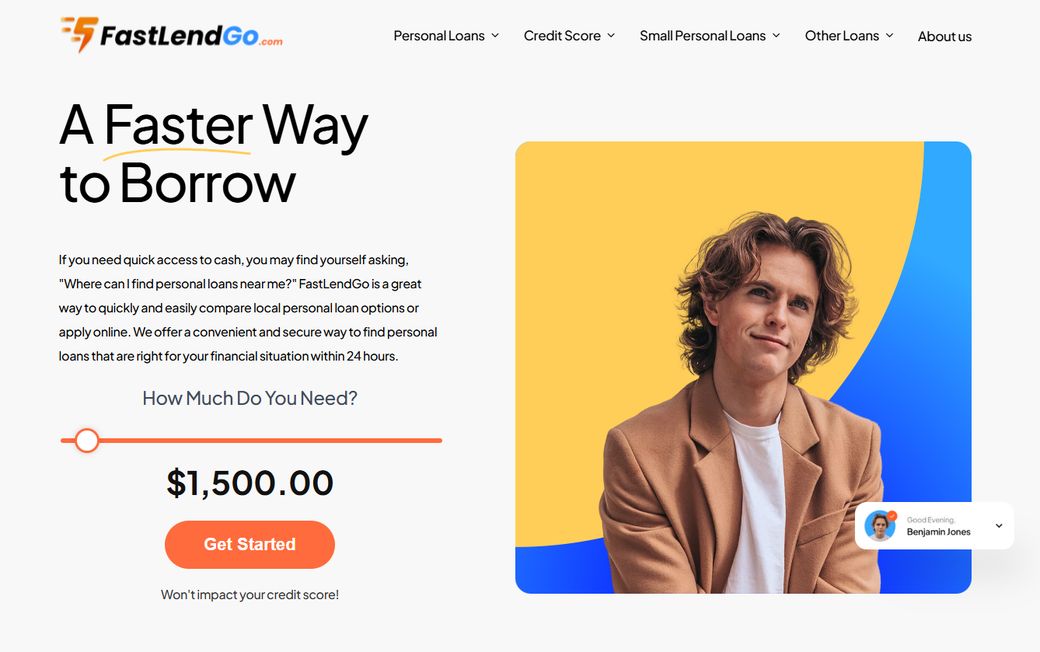
Life has a way of throwing curveballs when you least expect them. For those facing sudden fiscal hurdles, FastLendGo acts as a reliable safety net. They provide a versatile selection of funding, ranging from modest $500 increments to more substantial $5,000 packages.
This range of options is perfect for balancing various obligations. You might find yourself needing a quick fix for a car repair while simultaneously trying to settle a larger tax debt. Having that flexibility can be a total lifesaver during stressful times.
Time is of the essence when cash is tight. This platform is engineered for rapid deployment, making it an ideal choice for urgent needs like dental work, home fixes, or automotive issues. Instead of getting lost in a labyrinth of paperwork at a traditional bank, FastLendGo utilizes a streamlined digital workflow to expedite your request.
If you simply cannot afford to sit around waiting for a slow approval, this is a dependable route to get your finances back on track quickly.
Pros:- A broad spectrum of loan amounts, starting at $500 and reaching $5,000 and beyond.
- Targeted financing for specific needs, such as roofing, dental work, or vehicle repairs.
- Open to various credit profiles, from poor standing to excellent.
- Interest rates might not be the most competitive for those with top-tier credit scores.
2. SoFi
Think of SoFi as much more than just a place to borrow money; it functions as a holistic financial hub. While they are famous for their investment and banking products, their real strength lies in the sophisticated management tools they offer.
Consider their high-yield savings accounts as a sanctuary for your growing capital. As you work diligently to raise your credit score, these accounts provide a secure, productive environment to let your money work for you through interest.
By automating your monthly savings, you can construct a financial cushion that guards against the temptation of high-interest debt later on. For the individual seeking a “one-stop-shop” for everything from checking accounts to long-term mortgages, this lender is hard to beat.
While they tend to be a bit more selective than smaller micro-lenders, their suite of products is tailor-made for those who have successfully weathered their darkest economic storms. It is a premium choice for anyone prioritizing long-term wealth and stability.
Pros:- Seamlessly combines banking, insurance, and investment services.
- Competitive APY for your savings accounts.
- An intuitive and modern digital experience.
- The most favorable terms are generally reserved for those with higher credit scores.
3. Prosper
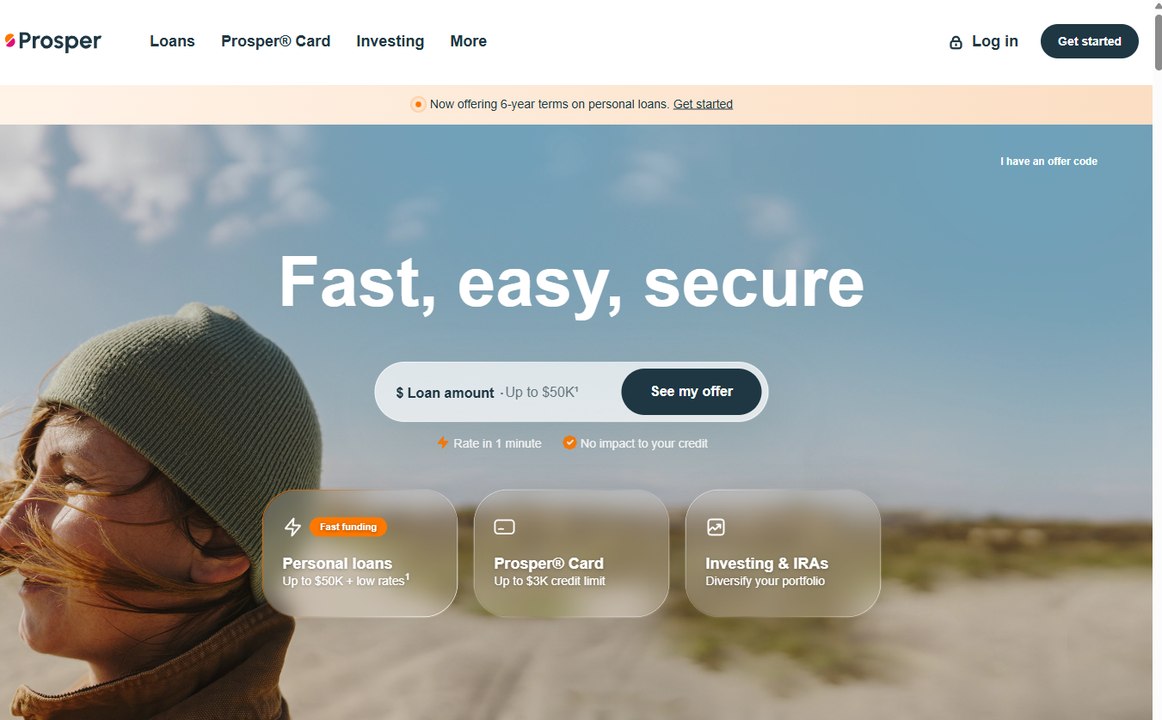
Prosper invites you to step into the world of peer-to-peer (P2P) lending. Rather than pulling from a bank’s vault, you are borrowing from individual investors. They offer significant capital, with loan amounts spanning from $2,000 all the way up to $50,000.
This makes them a powerhouse for major life milestones or heavy financial lifting. Whether you are tackling massive debt, paying for university, or starting a kitchen renovation, they provide the heavy artillery you might need. Because their funding source is unique, their requirements often differ from conventional banks.
Navigating their platform is a breeze, characterized by both security and speed. You can discover your potential rates in roughly sixty seconds through a soft credit pull. This is a game-changer if you want to shop around without the fear of dinging your credit score.
For those looking to break away from the traditional banking mold, Prosper offers a highly efficient alternative. They are a robust solution for substantial financing when a standard bank might have simply closed the door on you.
Pros:- Ample funding limits reaching up to $50,000.
- Quickly check rates with minimal impact on your credit history.
- A streamlined and safe online application journey.
- The P2P model means approval rates can fluctuate depending on investor appetite.
4. Avant
Avant is designed for people looking to turn a corner in their financial journey. By offering tools like installment loans and credit cards, they help you demonstrate your reliability through a history of consistent, timely payments.
Their philosophy feels much more like a supportive partnership than a cold transaction. They provide the necessary instruments to help you hit specific milestones, such as successfully consolidating your existing debt into a single, more manageable monthly obligation.
Whether you are facing a sudden emergency or looking to streamline your bills, Avant has a way to help. They strive to cut through the confusion and provide clear, actionable answers to complex money questions.
Their specific niche is the middle-tier borrower. These are individuals who might not boast elite credit scores but can prove their reliability through a steady stream of income and a history of responsible management.
Pros:- Specialized in handling debt consolidation and emergency fund needs.
- Offers adaptable solutions for various life transitions.
- Provides helpful tools and customer-focused support.
- The specific requirements for eligibility can sometimes be tricky to interpret.
5. Allegiance Credit Union
Established in 1963, Allegiance Credit Union is an institution deeply rooted in its community. They operate on the fundamental belief that every individual’s story matters—even those currently working to recover from a major financial setback.
This philosophy sets them apart from the massive, faceless national banks where you are often treated like just another digital entry. At a credit union, your local connection and your personal relationship with a loan officer actually carry significant weight.
They provide a diverse array of products aimed at helping you save, borrow, and ultimately build a more resilient future. If you crave a banking experience driven by a sense of mission rather than just profit, a credit union is a breath of fresh air.
You will often find much more tailored guidance during the application process here. This personal touch is invaluable when you need to explain the context of a past bankruptcy and demonstrate that your current financial footing is stable and upwardly mobile.
Pros:- Deeply embedded community ties and a long-standing history of service.
- A member-centric mission focused on individual well-being.
- A wide variety of tools for borrowing and saving.
- Membership may be limited to certain geographic areas.
6. VivaLoan
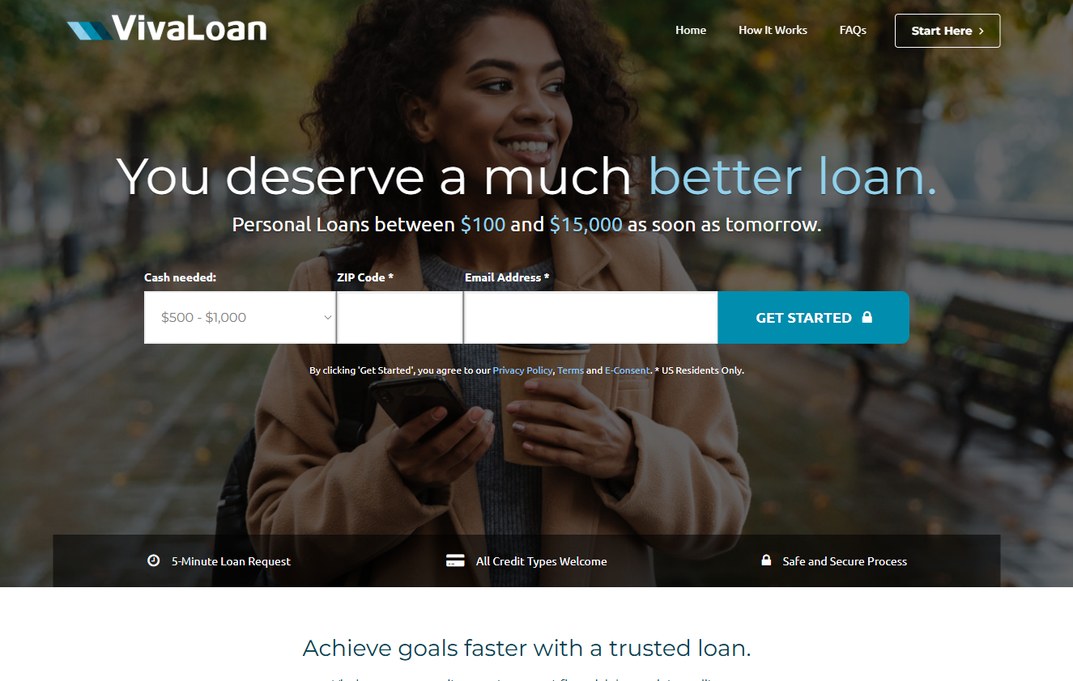
Speed is the name of the game for VivaLoan. Their funding options are incredibly flexible, starting at a tiny $100 and scaling up to $15,000. This spectrum ensures you can find a solution for anything from a small set of new tires to a larger, more significant life event.
This level of versatility is a vital asset if you are still in the early, stabilization phase of your financial recovery. You won’t have to over-borrow if you only need a small amount to bridge a gap.
The standout feature is how quickly you can access your cash. In many cases, funds can be sitting in your account as early as the very next business day. With a five-minute application and an open policy toward all credit types, they serve as a true lifeline during crises.
While the sheer ease of use is a massive advantage, it is vital to use this capital wisely. You want to ensure you don’t find yourself trapped in a cycle of high-interest debt that prevents you from moving forward.
Pros:- Rapid funding, with money often available by the next business day.
- Extremely low entry point with minimum loans of $100.
- Welcomes applicants regardless of their credit type.
- The high speed and easy access may result in more expensive borrowing costs.
7. World Finance
World Finance operates as a highly specialized entity within the financial landscape. They offer a wide variety of services that bridge the gap between retail and private banking, catering to a more complex market.
Their expertise is particularly useful for those who do not fit into a standard consumer box. This might include individuals with unconventional income streams or those who require highly customized loan structures to meet their specific needs.
They maintain a sharp focus on both local economic shifts and broader global trends. This perspective allows them to offer sophisticated insights to their clients, making them more than just a simple lender.
For borrowers navigating a multi-faceted recovery involving several different types of assets, their complex services can be indispensable. They are a partner for those seeking depth and professional expertise beyond a basic personal loan.
Pros:- A massive breadth of specialized financial services and market intelligence.
- Deep-seated expertise across various banking sectors.
- A professional focus on evolving market trends.
- The complexity of their offerings may be more than a typical consumer requires.
How to Sharpen Your Approval Profile
Navigating the lending landscape after a bankruptcy discharge is no walk in the park. To catch a creditor’s eye, you need to present a picture of financial steadiness. Think of yourself as a candidate for a high-stakes job; you need to show that you are a safe bet despite your past baggage.
Even when your credit score is still limping toward recovery, you can tilt the scales in your favor. The secret sauce lies in meticulous record-keeping regarding your earnings. Keeping a tidy folder of your latest tax filings, bank activity logs, and recent salary slips can make all the difference.
When a banker looks at your application, they aren’t just looking at numbers; they are looking for a consistent story. If you can present an uninterrupted stream of revenue through organized paperwork, they will feel much more comfortable extending you credit. It’s about building a bridge of trust through transparency.
Utilizing Assets to Lower Risk
If you find yourself hitting a brick wall with traditional unsecured lending, don’t throw in the towel just yet. There is a clever workaround that many people overlook: the secured loan. This approach essentially uses a piece of your property to act as a safety net for the bank.
By pledging an asset, such as a vehicle title or a chunk of savings, you are effectively telling the lender, “If I stumble, you have something to hold onto.” This collateral drastically lowers their potential for loss. Because the danger to them is minimized, you often find much easier approval paths.
In many cases, these secured options come with more palatable interest rates compared to the predatory offers found elsewhere. It is a strategic move designed to play the long game. You aren’t just getting cash; you are investing in your future financial reputation.
Think of this as a stepping stone rather than a final destination. As you diligently settle these smaller, backed debts, your credit profile will begin to glow with renewed strength. This rebuilding phase is the foundation for the much larger, unsecured financing you will eventually require.
Navigating the Perils of the Lending Process
Hunting for credit can feel like walking through a minefield if you aren’t careful. The most frequent blunder occurs when borrowers leap at the very first deal that crosses their desk. It is vital to weigh the entire price tag of the debt rather than focusing solely on your monthly dues.
A tiny monthly installment might look like a lifeline, but it often masks a predatory interest rate. You might find yourself stuck in a cycle where the repayment period is so extended that you pay back twice the principal. Always demand the Annual Percentage Rate (APR) to uncover the actual cost of your commitment.
Think of it as checking the weather before a long trek. If you only look at the surface, you might get caught in a storm. Understanding the APR provides the clarity needed to see through deceptive marketing tactics that favor the banks over the individual.
Mistakes often hide in your credit history, waiting to derail your application. You must scrutinize your reports for inaccuracies before hitting the “apply” button. Even with a bankruptcy officially discharged, phantom debts can still haunt your file. It is a common headache for many people trying to rebuild.
Sometimes, a debt that was legally wiped out in your bankruptcy filing shows up as “unpaid.” These clerical errors can act like an anchor, dragging down your creditworthiness. Tidying up these discrepancies is your first line of defense in securing a favorable rate.
Consider your credit report as a resume for your financial life. If that resume contains lies or errors, no lender will want to hire you. Take the time to scrub your records clean so that your path to approval remains wide open.
Watch out for the sneaky “exit fees” known as prepayment penalties. Some institutions will penalize you for being responsible and attempting to settle your debt ahead of schedule. This is the last thing you need when your primary goal is to escape the clutches of debt.
If you find a loan with these hidden costs, you might be paying a premium for your own success. It feels like running a race only to find a fence at the finish line. Always verify the terms regarding early repayment before signing any paperwork.
Approach this entire endeavor with a sense of calm and deliberate patience. Reclaiming your financial stability is a marathon, not a frantic sprint toward the horizon. Take it one step at a time, and you will eventually reach your destination.
