
Top-Rated Personal Loan with Co Signer Options for Quick Approval
Last updated: 2026-10-17
Navigating the lending landscape with a low credit score is like trying to find your way through a heavy mist in the dead of night. You might feel like you are wandering aimlessly without a map. Many individuals decide to ask a family member or a trusted companion to act as a co-signer to help them out.
By bringing someone on board with a solid credit history, you can potentially bridge that financial chasm. This small act of kindness frequently serves as the deciding factor for many applicants. It can be the bridge that turns a flat-out rejection into a successful path toward covering a sudden medical expense or a necessary auto mend.
When you start comparing different lenders, try not to get hung up solely on what you owe each month. It is vital to observe the entire landscape. You must consider how quickly the funds land in your bank account and what the cumulative cost looks like over the full life of the debt.
A small monthly installment might seem like a dream come true at first glance. However, if that repayment period drags on for 72 months, the accumulated interest can become a massive financial weight. You might find yourself paying much more than anticipated due to that extended timeline.
Speed can also be a double-edged sword in this industry. While some companies boast about instant money delivery, they might be masking hefty origination fees. These hidden costs can make an “express” loan significantly more expensive than the standard options you would find at a local, traditional banking institution.
- FastLendGo
- OneMain Financial
- Upgrade
- Together Loans
- U.S. Bank
- MoneyLion
- MedLoan Finance
Our Benchmarking Process
We poured countless hours into dissecting the current landscape of financial products, specifically hunting for those that accommodate applicants with a co-signer. Our goal was to observe the mechanics of how institutions process a file when a second party enters the fray. It is a tricky dance, after all.
We needed to ensure that the obligations placed upon the guarantor were crystal clear. No one wants to stumble upon hidden pitfalls tucked away in a labyrinth of dense, legalistic jargon. We sifted through the fine print to make sure the rules of engagement were plain as day.
The distinction between a co-applicant and a simple guarantor played a massive role in our analysis. This choice dictates the weight of the liability resting on that second person’s shoulders. We prioritized companies that simplified these pathways rather than those that buried you under a mountain of redundant paperwork.
Honesty sat at the very heart of our investigation. We hunted for providers that offered lightning-fast responses, legible interest rates, and a diverse range of borrowing options. We essentially looked for transparency in every corner of their digital storefront.
We also scrutinized the “friction” within the digital application journey. This meant evaluating the sheer volume of documents required, the ease of using electronic signatures, and the clarity with which the Annual Percentage Rate (APR) was presented. A smooth ride is worth its weight in gold.
| Financial Provider | Borrowing Limits | Rates & Conditions | Time to Fund | Credit Profile |
|---|---|---|---|---|
| FastLendGo | $500 – $5,000+ | see site | see site | Bad to Great Credit |
| OneMain Financial | $1,500 – $30,000 | Rates from 11.99% APR | As soon as 1 hour | Bad Credit Friendly |
| Upgrade | Up to $50,000 | Fixed rates available | Fast funding | Credit Health focus |
| Together Loans | Up to $10,000 | 24 – 60 months | 24-hour approval | Trust-based/Bad Credit |
| U.S. Bank | see site | see site | see site | Traditional Banking |
| MoneyLion | Up to $100,000 | see site | Fast/Expedited available | Credit Building focus |
| MedLoan Finance | $500 – $100,000 | 12-18 Months Interest Free | see site | Medical Specific |
Leading Co-signer Lending Alternatives for 2026
1. FastLendGo
FastLendGo is a go-to option for those needing a quick cash infusion without navigating a mountain of paperwork. Their flexibility is a breath of fresh air, catering to everyone from someone facing a $500 emergency to those planning a massive life transition.
Unlike the rigid gatekeepers at a traditional mortgage department, these lenders understand life’s unpredictability. This makes them a perfect match for gig economy workers or individuals whose income might fluctuate from month to month. (fastlendgo.com)
If your credit history is a bit thin, this lender might be your best friend. Standard computer algorithms often trip up when they can’t find a long history of debt, but FastLendGo offers tailored paths for high earners and those with less-than-stellar credit.
By bringing a co-signer into the mix, you can effectively demonstrate a level of financial stability that your own recent records might not yet reflect. It’s like having a sturdy anchor when you are still finding your sea legs.
Pros:
- Starting amounts of $500 make them ideal for minor urgent needs.
- Funding can cover car repairs or dental work, preventing the need for multiple loans.
- A wide range of loan options accommodates various credit profiles.
Cons:
- Their niche focus means they might not be the ideal fit for consolidating general debt.
2. OneMain Financial
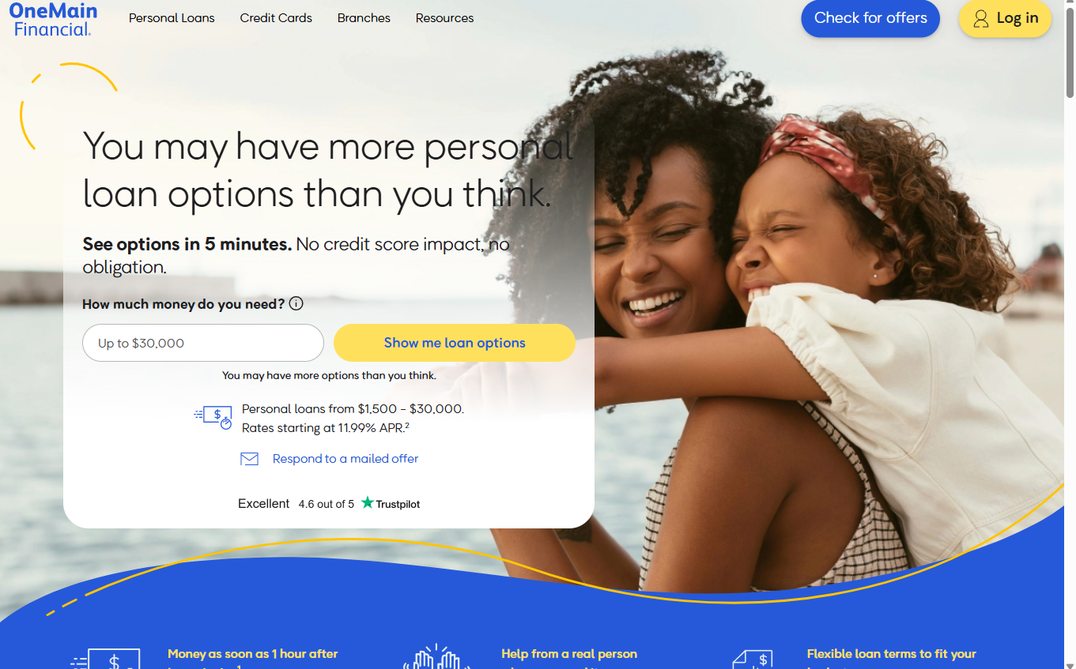
For those who prefer a handshake over a smartphone screen, OneMain Financial is a fantastic choice. They boast over 1,300 physical branches, providing a tangible presence that many strictly digital lenders simply cannot replicate in the current market.
Sometimes, explaining your financial situation to a human being provides a sense of peace that an app simply cannot offer. Sitting down in a physical office with a professional can make the whole borrowing process feel much more secure and transparent.
Speed is clearly in their DNA. In certain scenarios, you could see your funds land in your account a mere hour after signing your documents. Their joint loan structures are also incredibly user-friendly, simplifying the process for family members or partners.
This setup makes the co-signer’s role feel seamless rather than complicated. It effectively removes the guesswork from the collaborative responsibility of a joint loan.
Pros:
- Rapid funding is possible, occasionally within sixty minutes.
- An extensive network of branches ensures in-person support is always accessible.
- Joint loans ranging from $1,500 to $30,000 offer a streamlined co-signer experience.
Cons:
- Subpar credit scores can lead to significantly higher interest rates over the life of the loan.
3. Upgrade
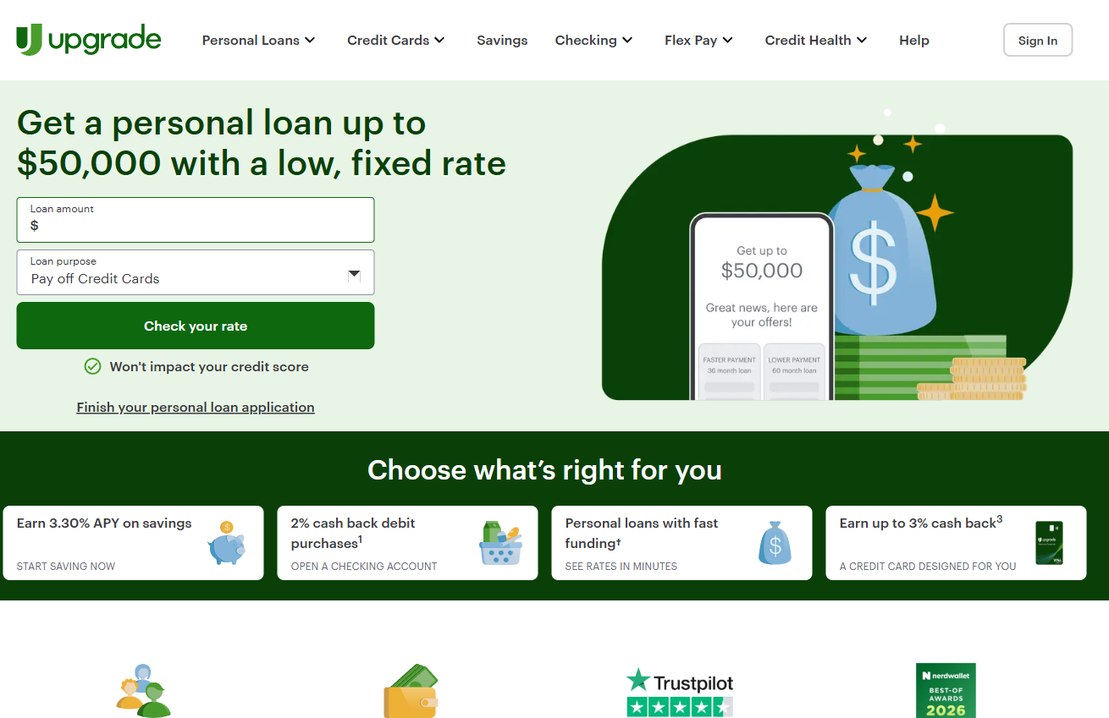
Upgrade operates with a modern mindset, prioritizing your long-term financial wellness. They act as a comprehensive financial hub, offering everything from savings accounts to credit cards to help you manage your entire economic life in one place.
Navigating their website is a breeze, and they allow you to simulate different repayment scenarios before you ever sign a contract. This “try before you buy” approach helps you avoid any nasty surprises down the road.
Whether you are looking to tackle existing debt or fund a major purchase, the application process is remarkably smooth. A standout feature is their “soft pull” credit check, which allows for quick comparisons without any damage to your score.
This makes shopping around for the best deal an easy, stress-free task. You can see your estimated APR and monthly costs without the fear of a sudden drop in your credit standing.
Pros:
- Checking your potential rate does not impact your credit score.
- Funds are highly versatile, useful for anything from debt to home improvements.
- Select products feature rewards in the form of cash back.
Cons:
- The sheer breadth of their product line might feel overwhelming if you want something simple.
4. Together Loans
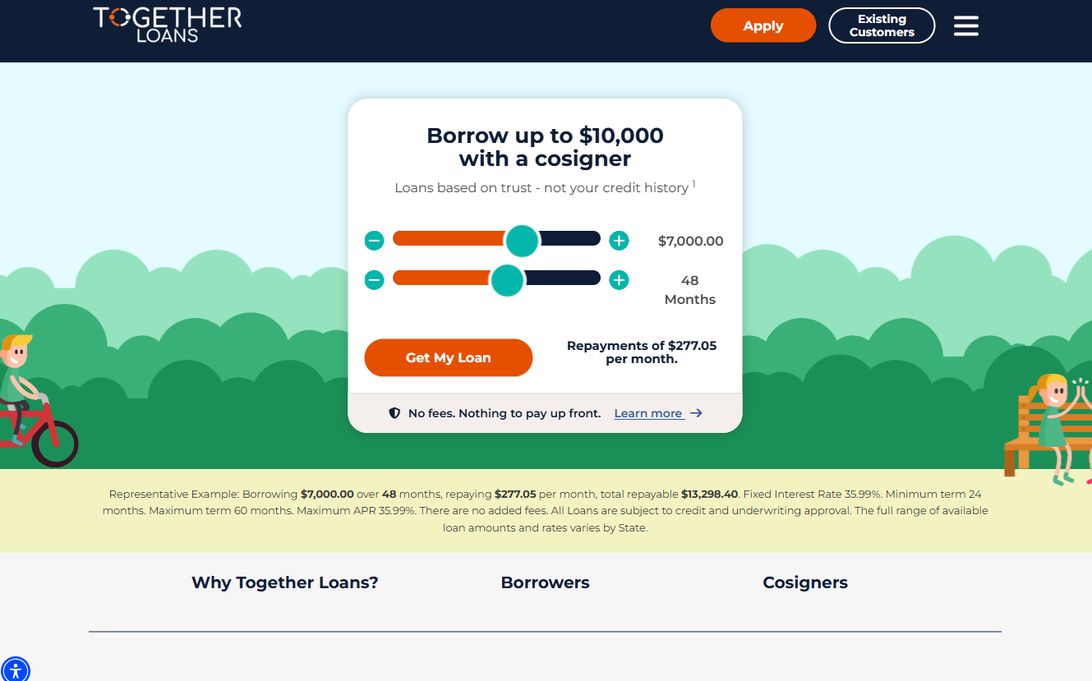
Together Loans takes a refreshing approach by valuing trust just as much as a digital score. This is a massive win for individuals who have a reliable co-signer but a credit history that has seen some rough patches.
Life can be unpredictable, and a single medical emergency or a stint of unemployment can leave your credit score in the gutter. These lenders look beyond the numbers to understand the actual human story behind the data.
Specializing in loans that reach up to $10,000, they operate with impressive speed, frequently issuing approvals in under 24 hours. If you are facing an urgent bill, this quick turnaround could be a total lifesaver.
Adding a co-signer here can be a game-changer for your terms. It can unlock much more favorable rates and conditions than you might be able to secure on your own.
Pros:
- They weigh personal circumstances and trust more heavily than rigid algorithms.
- The 24-hour approval window is ideal for high-urgency financial needs.
- Zero upfront fees ensure you receive the exact amount you requested.
Cons:
- Interest rates can lean toward the higher side, so read the fine print carefully.
5. U.S. Bank
If you find comfort in the presence of a massive, established institution, U.S. Bank is a very reliable choice. It is particularly advantageous if you are already a customer of theirs, as your existing history can speed things up.
Since they already have a clear picture of your cash flow, the verification steps often move much faster. It’s like having a head start in a race because they already know your financial habits well.
While they might not move with the lightning speed of a fintech startup, their massive infrastructure provides a level of stability that is hard to beat. They offer a full suite of services, from basic checking to sophisticated wealth management.
If you are preparing for a milestone like a wedding, the sheer scale and security of a major bank can provide much-needed peace of mind. You know they aren’t going anywhere.
Pros:
- They provide high levels of stability and consumer protection.
- Almost any financial service you might need is available in one place.
- Integration is seamless for those who already bank with them.
Cons:
- Requirements for personal loans can be more stringent compared to smaller, niche lenders.
6. MoneyLion
MoneyLion is designed for the mobile-first generation who does everything through a smartphone. Their app acts more like a digital financial assistant than a simple lending tool, helping you manage daily spending while building your credit.
They provide substantial loan amounts, reaching up to $100,000, which is ample for major life shifts like starting college. This level of funding provides significant breathing room for your long-term plans.
Because credit building is a core focus of their platform, they are an excellent partner for those looking to eventually graduate away from needing a co-signer. Their ultimate goal is to help you stand on your own two feet.
The mobile interface is incredibly intuitive and easy to navigate, making financial management feel less like a chore and more like a streamlined process.
Pros:
- Extremely high loan limits are available for significant projects.
- Built-in tools within the app help users educate themselves on credit.
- The mobile experience is very smooth and user-friendly.
Cons:
- Certain accelerated cash features may carry additional fees.
7. MedLoan Finance
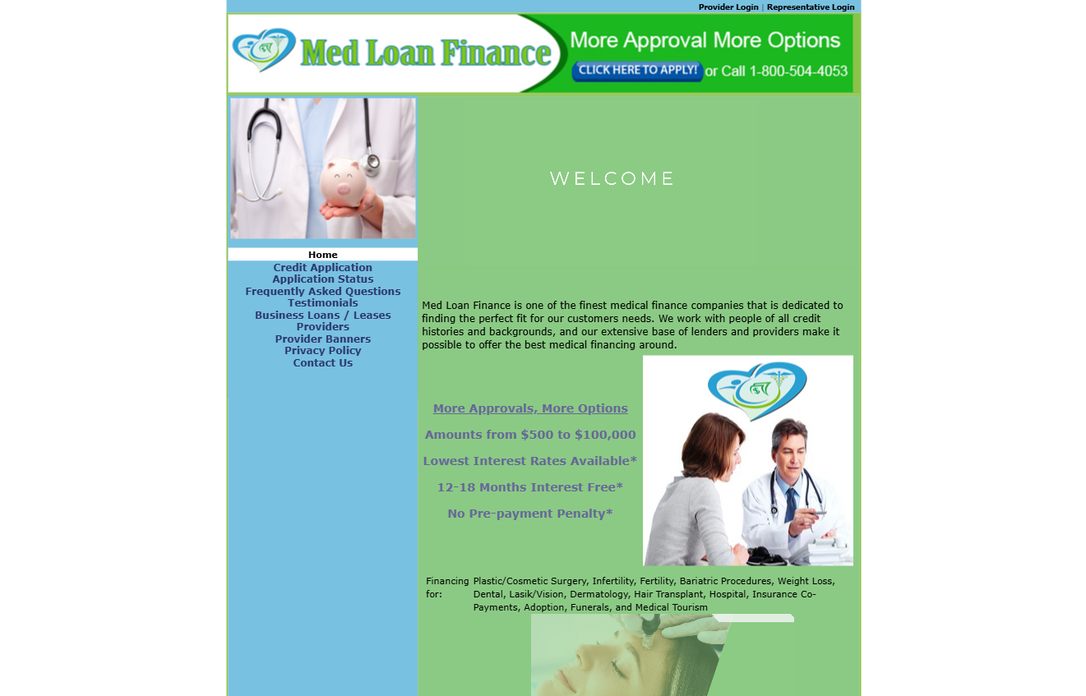
MedLoan Finance has a very specific mission: tackling medical debt. Whether it is for dental work, a surgical procedure, or LASIK, they offer funding tailored specifically to the nuances of the healthcare industry.
Standard personal loans often fail to account for the unique timing and requirements of medical costs. These specialists, however, understand exactly how medical billing works and provide solutions that fit that mold.
They provide a variety of loan amounts and even offer interest-free periods under certain conditions. If a surgery is on your horizon, this specialized route might be much more affordable than a high-interest general loan.
Using a specialist like this can save you a significant amount of money compared to traditional lenders. It’s about using a tool designed for the job rather than a hammer for a screw.
- They are experts in dental and elective medical procedure lending.
- Interest-free options for 12 to 18 months can lead to massive savings.
- They accommodate large medical expenses reaching up to $100,000.
- These funds are strictly limited to medical-related expenditures.
The Heavy Weight of Co-signing Responsibility
Stepping up as a co-signer is much more than a simple gesture of support between loved ones. When a relative or buddy puts their name on a loan document, they are making a binding legal commitment to cover the entire debt. It is not a mere formality; it is a serious financial vow.
Should a borrower fall behind on their scheduled payments, the responsibility shifts directly to the co-signer. The lender has the legal right to demand the total sum from that person, which includes any accrued interest and penalties for late payments. It is like being caught in a storm you didn’t start.
If the debt remains unpaid, the consequences can escalate quickly into legal battles or the garnishment of wages. Such financial turbulence can absolutely wreck a person’s credit score in a heartbeat. One missed payment can trigger a domino effect that haunts their financial future for years to come.
Furthermore, the loan’s total balance will appear prominently on their personal credit report. Even in a scenario where every installment is paid perfectly, the massive amount of debt can still act as a shadow. It can make obtaining a car loan or a mortgage a much steeper uphill battle.
Financial institutions view these obligations as potential threats to a person’s ability to manage their own monthly bills. They see the risk lurking behind that massive number on the report. Ultimately, placing such a heavy burden on someone you care about is a gamble with high stakes.
Setting the Stage for a Successful Application
Landing an approval is not a matter of luck; it is about being battle-ready. Simply having your driver’s license in hand is a drop in the bucket compared to what you truly need. You must construct a bulletproof strategy for repayment before you ever walk into the bank or click “submit” online.
Think of it like preparing for a long trek through the wilderness. You wouldn’t head out without a map and extra rations, so why approach a loan without a roadmap? We recommend following these specific guidelines to ensure you don’t hit a brick wall during the process:
- Draft a Repayment Roadmap: Detail every single installment, including the precise timing and the method of delivery. It is wise to build a safety net within your monthly spending to accommodate those unexpected rainy days when money might be tight.
- Verify Your Partner’s Credit History: Most financial institutions look for a credit score in the 670 to 700 range for anyone acting as a co-signer. If their score is dragging, you might find yourself chasing a ghost.
- Assemble Your Documentation: Financial officers will demand evidence of your income and residency, such as W-2 forms and recent pay stubs. Keeping these files organized in one place can prevent your application from stalling in limbo.
- Review the Fine Print Together: Avoid the temptation to rush the signing. Sit down with your co-signer to dissect the clauses regarding missed payments so there are no surprises down the road.
Managing Your Co-signer Agreement
Sit down with your potential partner and lay all the cards on the table before signing a single document. It is vital that they grasp the weight of the legal obligation they are undertaking. If things go sideways or you face sudden unemployment, their financial reputation is on the line right alongside yours.
Tension often arises when finances enter the family circle. You shouldn’t treat this person as a mere checkbox on an application form. To a bank, that individual functions as a main guarantor for the debt. They are essentially standing in the gap to ensure the lender gets paid back.
If your co-signer’s credit profile mirrors your own struggles, don’t expect a miracle. Lenders might still reject the application or hit you with a punishingly high interest rate. In such scenarios, bringing someone on board fails to deliver any real financial advantage to your bottom line.
Avoid the temptation to grab a larger loan amount just because you have the extra capacity. Interest accumulates like a rolling snowball, turning a modest debt into a mountain of payments over time. Only leverage this option to secure more favorable terms, not to increase your overall debt load.
