
Top-Rated Options for a Personal Loan With Collateral This Year
Last updated: 2026-10-17
Entering a conversation regarding secured financing can feel like wandering blindly through a heavy mist. When you pledge an asset, such as a vehicle or a bank account, to guarantee your debt, you are making a heavy commitment. This strategy works wonders for those hunting for reduced interest costs or seeking approval after being turned away by big banks.
Offering collateral essentially signals to the lender that their exposure is significantly minimized. Consequently, this often results in superior loan conditions and much larger borrowing capacities than unsecured options provide. It is a calculated trade, swapping a portion of your personal belongings for much more advantageous financial terms.
Selecting the right firm means seeing through the flashy advertisements. You must balance your immediate need for liquid cash against the potential danger of forfeiting your property. A sudden mechanical breakdown in a car used as security or a sharp drop in market values can completely flip your financial projections overnight.
The following selection identifies the leading institutions currently dominating the 2026 landscape. We prioritized organizations that provide both reliability and rapid processing for a wide array of monetary requirements.
- JetzLoan
- Best Egg
- OneMain Financial
- Freedom First Credit Union
- Balance Credit
- Synchrony
Our Methodology for Selecting Lenders
Our goal was to pinpoint financing options where using assets can truly bolster an individual’s borrowing potential. Our investigators scrutinized how various banks manage diverse financial backgrounds. We looked at everyone from those with spotless payment records to individuals currently navigating a tight spot.
Money in your pocket is vital, but it isn’t the only thing that counts when life throws a curveball. The velocity of the payout is equally critical. If a company leaves you hanging for weeks while shuffling paperwork, they aren’t much help when an urgent payment deadline looms.
We prioritized how quickly funds arrive, the peak borrowing ceilings, and the simplicity of the signup process. It is like comparing apples to oranges, but these metrics gave us a clear picture. We also investigated whether an initial check would leave a mark on your file.
Having the ability to browse potential interest rates without hurting your rating is a huge win. We hunted for providers that utilize “soft pulls” to generate your preliminary offers. This way, you can window shop for better deals without cluttering your report with numerous inquiries.
| Provider | Upper Limit | Payout Timing | Inquiry Effect |
|---|---|---|---|
| JetzLoan | $35,000 | 24 hours or less | No hard pull required |
| Best Egg | $50,000 | Check their website | Check their website |
| OneMain Financial | $30,000 | Within 1 hour | No score damage |
| Freedom First Credit Union | Check their website | Check their website | Check their website |
| Balance Credit | $4,000 | Following business day | No impact on score |
| Synchrony | Check their website | Check their website | Check their website |
Top-Tier Lenders for Collateral-Based Loans
1. JetzLoan
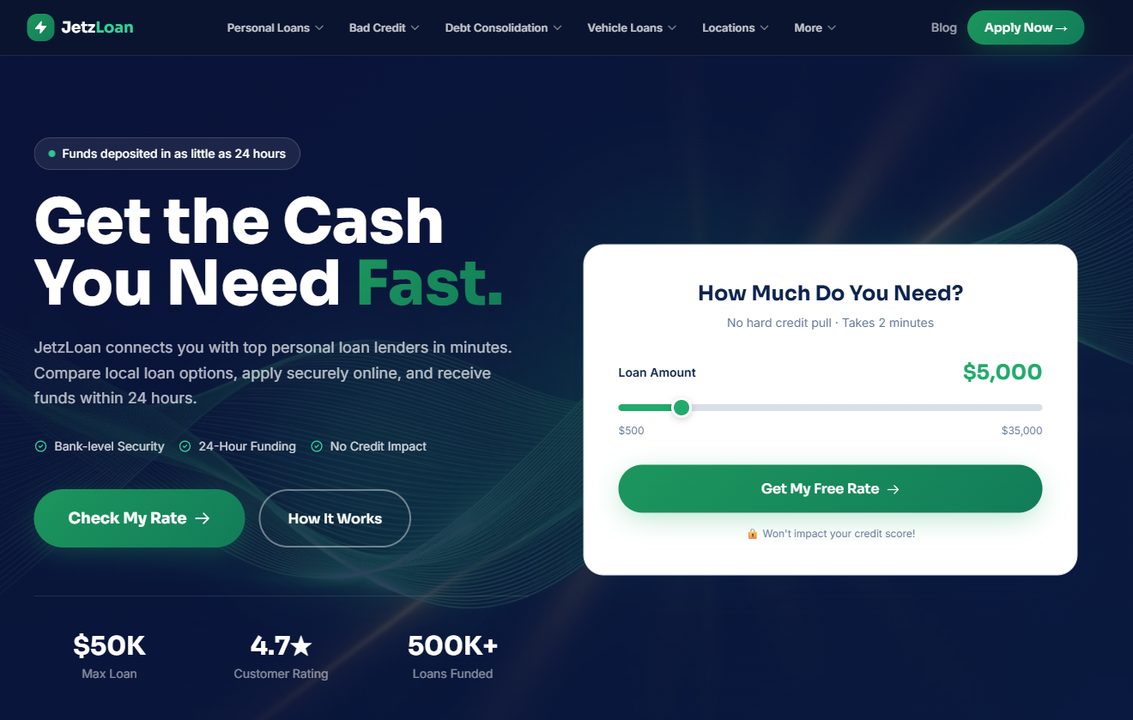
Think of JetzLoan as a rapid transit system for your finances. If you find yourself in a tight spot and need liquidity fast, they act as a bridge to premier lenders in mere moments. It is a lifeline for those facing sudden financial hurdles.
When a medical emergency strikes or a pipe bursts in your kitchen, you shouldn’t have to wait for a miracle. Their ability to get money into your hands within 24 hours is truly impressive. (jetzloan.com)
Are you terrified of the dreaded “credit score dance”? This lender lets you shop around without the sting of a hard credit inquiry. You can scout different rates while keeping your credit profile perfectly intact.
This peace of mind is gold if you are currently shopping for a mortgage or a new car. You simply cannot afford any sudden drops in your score right now. Their digital-first, transparent method makes the whole process feel seamless.
Pros:
- Cash can arrive in as little as 24 hours.
- Initial rate checks won’t hurt your credit score.
- Maximum borrowing capacity reaches $35,000.
Cons:
- They function as a matchmaker rather than the direct lender.
2. Best Egg
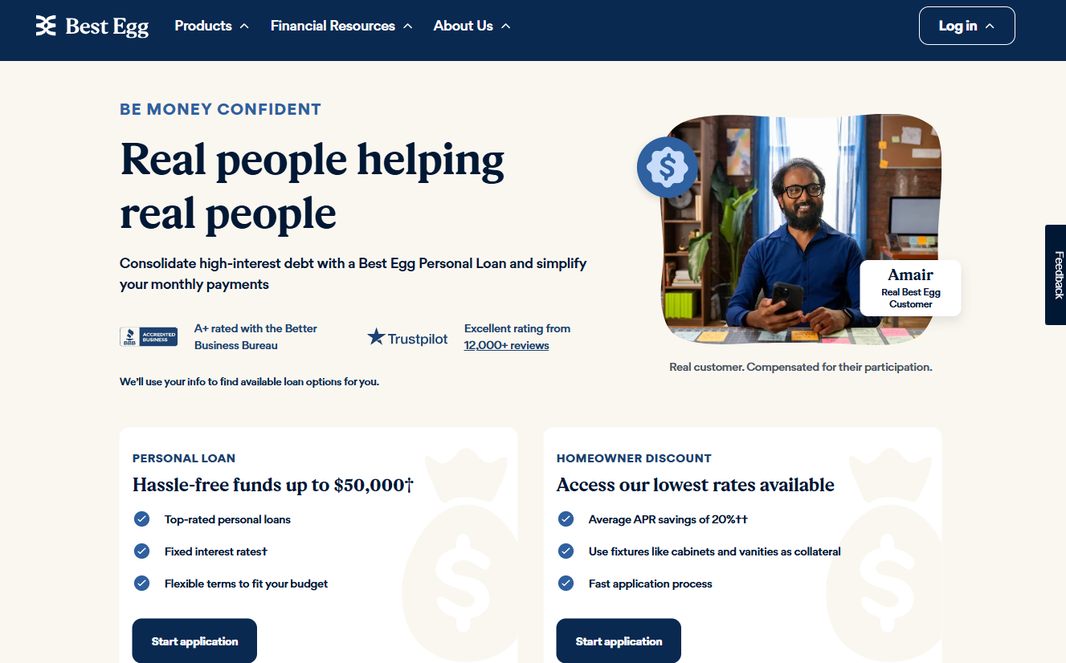
In the crowded world of personal lending, Best Egg is a certified heavyweight. They don’t play games; they provide a straightforward, no-nonsense approach to borrowing. Their main mission is helping folks tidy up their financial lives.
If you are drowning in various high-interest credit card balances, a single Best Egg loan can act as a life raft. By merging those debts into one monthly payment, you can often see your APR drop significantly.
They have a rather clever trick up their sleeve: using household fixtures as security. Imagine using your cabinets or vanities to back a loan. This unconventional path is a game-changer for homeowners needing a boost.
It is a unique niche within secured lending. By treating home improvements as tangible assets, they offer a way to tap into equity without the massive headache of a formal home equity loan.
Pros:
- High loan ceilings up to $50,000.
- Possible to save 20% on APR.
- Special discounts for homeowners.
Cons:
- Specific eligibility requirements for certain rates and terms.
3. OneMain Financial
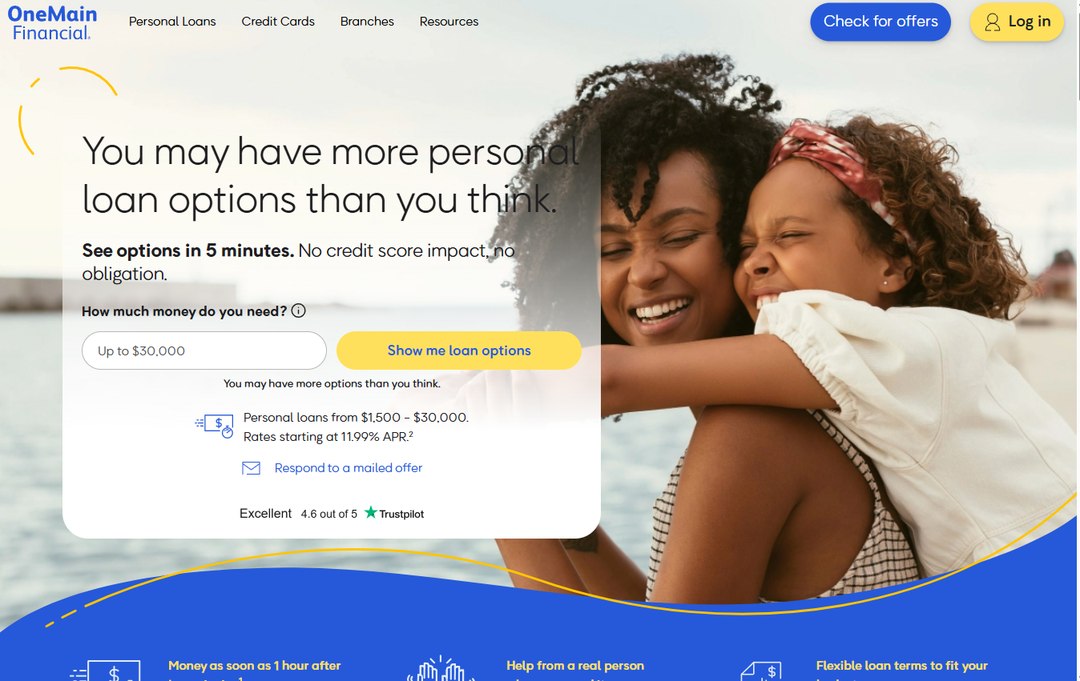
OneMain Financial offers the best of both worlds: digital speed and old-fashioned human connection. With a massive network of over 1,300 branches, they aren’t just a ghost in a machine. They offer a tangible presence that many online lenders simply lack.
If you ever find yourself trapped in a digital loop or struggling with a confusing upload, you can just walk through their door. Meeting a real person face-to-face provides a sense of security that purely fintech apps can’t replicate.
For those whose credit history isn’t quite perfect, they are a bright spot. You can gauge your potential options in a mere five minutes without any impact on your score.
Life happens fast, like a car repair that threatens your ability to commute. In those critical “make or break” moments, they can deposit funds just one hour after you sign the paperwork. That kind of speed is vital.
Pros:
- Lightning-fast funding, often 1 hour after signing.
- Large branch network for personal, in-person assistance.
- Flexible repayment timelines from 24 to 60 months.
Cons:
- Total loan amount is capped at $30,000.
4. Freedom First Credit Union
Freedom First Credit Union is built on a foundation of community spirit. Unlike the cold, distant big-box banks, they operate with a local mindset. They provide secured loans that allow you to use your share accounts or certificates as collateral.
It is a rock-solid way to expand your credit while accessing the cash you need. Since you are essentially borrowing against your own savings, the interest rates tend to stay much lower. The risk to the institution is minimal, making approval much easier.
They also throw in some lovely perks, such as the ability to access your paychecks up to two days early via direct deposit. This extra bit of flexibility can make managing your monthly cash flow much smoother.
If you believe in giving back, their “Play for Purpose” initiatives show they care about local causes. It creates a beautiful cycle of mutual benefit between the credit union and the people it serves.
Pros:
- Service model rooted in the community.
- Can utilize share accounts as collateral.
- Get paid up to 2 days early via direct deposit.
Cons:
- Membership likely requires meeting specific local criteria.
5. Balance Credit
Balance Credit is a specialist for those who need a quick shot of cash without a massive debt load. They focus on smaller, more manageable loans that cap at $4,000. In a sea of financial giants, they serve a specific niche.
Inclusivity is their bread and butter. They are willing to look at applications from people with less-than-ideal credit histories. This makes them a lifesaver when you need short-term liquidity but don’t need a mountain of debt.
The speed here is nothing short of impressive. Your funds can arrive in your bank account by the very next business day. Plus, they don’t believe in punishing you for being responsible and paying the loan off early.
This can save you a mountain of interest over the long haul. If a bonus or a tax refund rolls in, you can wipe that debt out instantly without facing any “prepayment penalties” from the bank.
Pros:
- No extra costs for early loan repayment.
- Welcomes applicants with various credit backgrounds.
- The application process is incredibly rapid.
Cons:
- Maximum borrowing is limited to $4,000.
6. Synchrony
Synchrony tends to live within the marketplace and specialized financing models. They often work hand-in-hand with specific retail brands, making them more of a targeted tool than a general-purpose loan provider.
If you are looking to upgrade your lifestyle through specific retail purchases, they are your best friend. For instance, when buying high-end appliances, you might find 0% interest promotions that make big purchases much easier to stomach.
Their toolkit includes everything from credit cards to various marketplace financing options. While they might not be your first call for a utility bill, their specialized options are top-tier for large, specific retail needs.
They have mastered the art of the seamless checkout experience. The transition from browsing a store to securing financing is nearly instantaneous, making the whole shopping journey incredibly smooth for the consumer.
Pros:
- Excellent financing tailored to retail partners.
- A diverse array of credit-related products.
- Integrated into a massive, established financial system.
Cons:
- Less effective for general, non-retail personal loans.
Navigating Asset Classes and Financial Hazards
Before you sign on the dotted line for a secured loan, you need to grasp the weight of your pledge. Typically, the things you put up as security fall into three distinct buckets: cash-like assets, tangible possessions, or investment vehicles. Every single one carries a different set of potential pitfalls.
Cash equivalents, such as certificates of deposit or standard savings, are a lender’s dream because they are easy to access. For the borrower, these often represent the most economical path. For instance, pledging $5,000 from your savings usually results in incredibly favorable, low interest rates.
The catch is that this capital becomes essentially untouchable. You won’t be able to dip into that $5,000 for emergencies or unexpected bills as long as the debt remains outstanding. This can leave your wallet feeling surprisingly light during a sudden financial crunch.
Tangible items, particularly your car, are frequently used to back these loans. While a vehicle can help you qualify for much larger sums of money, it introduces the headache of “depreciation risk.” Your car’s market value is in a constant state of decline.
Imagine borrowing $15,000 against a vehicle that, because of its high mileage, is only worth $12,000. You are now “underwater,” meaning your debt outweighs the asset’s value. This puts you in a tight spot if you ever need to sell the car or miss a payment.
Investing in stocks or bonds allows for substantial borrowing power, but these come with a wild ride. The market is notoriously fickle, and sudden shifts can trigger a “margin call” from your bank. This is a high-stakes game that demands a deep understanding of finance.
Should the market crater, your lender might demand an immediate cash infusion to cover the gap. If you can’t cough up the funds, they have the right to liquidate your portfolio at a loss. Managing these types of assets requires a steady hand and sharp expertise.
Navigating the Loan Approval Path
Getting approved for financing isn’t a game of luck; it is more like following a map through a dense forest. If you rush without a plan, you might find yourself lost in a thicket of high fees and unexpected costs. You must tread carefully to protect your fiscal well-being while hunting for the most favorable terms.
Think of this process as a series of checkpoints. By hitting each one in order, you ensure that you aren’t blindsided by fine print later on. Use this roadmap to navigate your way from initial planning to final signature with confidence and clarity.
Stage 1: Inventory Your Collateral. Start by conducting a thorough audit of anything you might pledge to secure the funds. It is a common mistake to look at what you originally paid for an item, but you must focus on its current market worth instead.
For instance, if you are using a car, consult Kelly Blue Book to find its actual present-day value. If you are leveraging home fixtures, estimate what it would cost to replace them today. Make sure you have all your relevant bank statements and ownership titles sitting on the desk ready to go.
Stage 2: Verify Your Credit Standing via Soft Inquiry. Before you dive in, you need to know where you stand in the eyes of creditors. Utilize the “no credit impact” tools offered by companies like OneMain Financial or JetzLoan to get a quick snapshot of your score without hurting your rating.
This baseline is your compass. It determines whether you will be welcomed with “prime” interest rates or if you will be forced to settle for much costlier “subprime” lending products. Knowing this number early saves you from a lot of heartache during the actual application phase.
Stage 3: Prioritize the APR Over the Interest Rate. Don’t let a low interest rate dazzle you into a bad decision. While the interest rate tells you the cost of the principal, the Annual Percentage Rate (APR) tells the whole story by folding in all the extra fees and points.
Consider this scenario: a 5% interest rate coupled with $500 in various fees might actually end up costing you more than a 6% rate that has no extra charges. To make a fair, apples-to-apples comparison between different lenders, the APR is the only number that truly matters.
Stage 4: Weigh Your Repayment Duration. You must decide how long you want to be in debt. Choosing a longer window, such as a 60 months term, will keep your monthly obligations low and give your cash flow some breathing room. However, there is a catch.
The downside is that a longer timeline means you will be paying a much higher amount of total interest over the life of the debt. Always run the numbers to find the “total cost of the loan” to understand the true price tag you are signing up for.
Stage 5: Scrutinize the Default Clauses. Never skip the fine print regarding what happens if you hit a rough patch. You need to find the specific “remedies upon default” section to understand exactly how many missed payments would trigger a formal default status.
Furthermore, investigate the specific notice requirements. How much warning must the lender provide before they are allowed to seize your assets? Identifying this “grace period” is absolutely vital for protecting your property and your peace of mind during difficult times.
Avoiding Common Pitfalls in Secured Lending
The biggest mistake is underestimating the weight of collateral. When you put your car or savings on the line, you are telling the lender, “If I fail, you take this.” It is a high-stakes game.
You need a clear-eyed view of your budget. A common psychological trap is thinking, “I can always pay it back later.” The legal reality of a secured loan is rarely that flexible.
Always read the fine print regarding defaults. Some lenders are much more aggressive than others. Some might repossess a vehicle after a single missed payment. Others might offer a structured workout plan.
Keep a close eye on the total cost of borrowing. A lower interest rate might look enticing, but high fees can change everything. Watch out for “origination fees” taken from your loan amount upfront. You might receive $9,500 even though you signed for $10,000.
Finally, do not rush the process just because you are in a pinch. Speed is important, but taking an extra hour to compare terms can save you thousands. Use “no credit impact” checks to do your homework without consequence.
