
Top-Rated Personal Loans in Illinois for Quick Cash in 2026
Last updated: 2026-10-17
Navigating your finances in Illinois can often feel like steering through a Chicago whiteout with nothing but a dim headlight. You might know exactly where you want to go, but the path ahead is cluttered with unexpected bumps and poor visibility. Simply typing a query into a search engine isn’t enough to find a reliable lender.
Instead, you must take a hard, honest look at your immediate financial requirements. This state is a massive tapestry, stretching from the bustling metropolitan hubs of Cook County all the way to the quiet, sprawling agricultural stretches of the southern regions. Because of this diversity, your available financial products are not one-size-fits-all.
Your specific zip code and your current credit standing act as the compass for your options. What works for someone navigating the urban jungle of Chicago might not be the right fit for someone living in a rural township. Your physical location plays a massive role in determining which doors will actually open for you.
Whether you are tackling an urgent home repair in Springfield or attempting to break free from the crushing weight of expensive credit card interest, the lender you choose will dictate how bumpy your journey feels. This guide is designed to provide a sense of direction when the market becomes overwhelming. Selecting an unsuitable provider can bring your financial recovery to a grinding halt before it even begins.
Consider your financial needs like a toolbox. Using a sledgehammer to hang a picture frame is a recipe for disaster, just as a high-cost payday loan is often overkill for a small, manageable debt. Conversely, a traditional personal loan might lack the flexibility required if you are working specifically to mend a bruised credit history. You must ensure the instrument fits the task at hand.
- Tower Loan
- IllinoisLoansToday
- OppLoans
- SAIL Loans
- MaxCash
Comparing Local Lending Services
Our team curated this selection by observing how these financial institutions serve the residents of the Prairie State. While getting cash quickly is a major plus, speed is only one piece of the puzzle. The sweet spot is finding a provider that offers manageable loan limits and approachable terms for various credit backgrounds.
We carefully analyzed how each firm navigates the unique landscape of the Illinois economy. This involved digging into specific state-level mandates and the financial hurdles our neighbors face daily. A loan can be a total godsend during a sudden engine failure, but it can quickly turn into a millstone around your neck if the contract is confusing.
This breakdown highlights the genuine opportunities currently available to those living in Illinois. We scrutinized their credit check processes, the actual velocity of fund transfers, and whether their maximum borrowing limits serve practical needs. We essentially wanted to see how these digital applications perform when faced with real human situations.
| Provider | Borrowing Limits | Eligibility Criteria | Time to Funds |
|---|---|---|---|
| Tower Loan | $2,500 – $20,000 | see site | see site |
| IllinoisLoansToday | $500 – $50,000 | No credit score impact to check | Results in minutes |
| OppLoans | $500 – $5,000 | Considers more than just FICO | Same-day funding available |
| SAIL Loans | Up to $4,000 | No, bad, or good credit | Quick Approval |
| MaxCash | $250 – $10,000+ | Bad Credit Loans available | Minutes |
Crunching the Numbers: Deciphering APR and Interest Totals
Before signing on the dotted line, you must get a grip on the underlying arithmetic. It is incredibly easy to get blinded by a low monthly installment. A fifty-dollar bill each month might feel like a walk in the park, but if that cycle drags on for 36 months due to steep rates, you could end up paying back twice your original principal. That is exactly how people fall into the teeth of a debt trap.
When you weigh your options across different providers, focus your eyes on the Annual Percentage Rate (APR). This specific figure offers much more transparency than a basic interest rate. It bundles the interest charges along with any compulsory fees required to secure your funds. A company might tempt you with a bottom-tier rate, only to ambush you with a massive origination fee right at the start.
Imagine you are pulling a $2,000 loan to settle a sudden medical crisis. If there is a $200 fee tucked away in the fine print, your actual cost of capital shifts drastically. It spikes your real debt burden from day one. Always pose this question to yourself: “How much cash will have left my pocket by the time this debt is fully extinguished?” That specific number reveals the unfiltered reality.
Priming Your Loan Request for a Quick Decision
Think of your loan application like a chef preparing for a busy dinner rush; if the ingredients aren’t prepped, everything falls apart. Today’s lenders rely heavily on high-speed algorithms to vet your identity and salary. If your files look like a tangled mess of old receipts, you risk hitting a brick wall or facing annoying delays.
Getting your ducks in a row is essential. You want the machine to see a clear, professional profile rather than a puzzle with missing pieces. To keep the gears turning without a hitch, pay close attention to these specific requirements:
- Validate Your Revenue Streams: Creditors are looking for a consistent heartbeat of income. You should have your most recent two to four pay slips sitting right at your fingertips. For those navigating the Illinois gig economy or running a solo business, ensure your 1099 forms or the past two years of tax filings are ready to go.
- Prove You Live in the Prairie State: Because these specific providers concentrate on Illinois, your paperwork must reflect your local residency. Use utility invoices or monthly bank records to confirm your current street address. If the data on your form clashes with your official papers, automated systems will likely raise a red flag.
- Double-Check Your Banking Info: Companies that specialize in rapid funding, such as MaxCash or OppLoans, utilize ACH transfers to move money. It is vital that your chosen account is active, contains enough capital to cover that initial installment, and bears a name that is an exact match to your application.
- Evaluate Your Debt-to-Income (DTI) Balance: Even a lender like OppLoans needs to be certain you won’t sink under the weight of new payments. Figure out your total monthly obligations and weigh them against your gross earnings. The leaner that ratio looks, the more likely lenders are to give you the green light.
Leading Personal Loan Options Across Illinois
1. Tower Loan
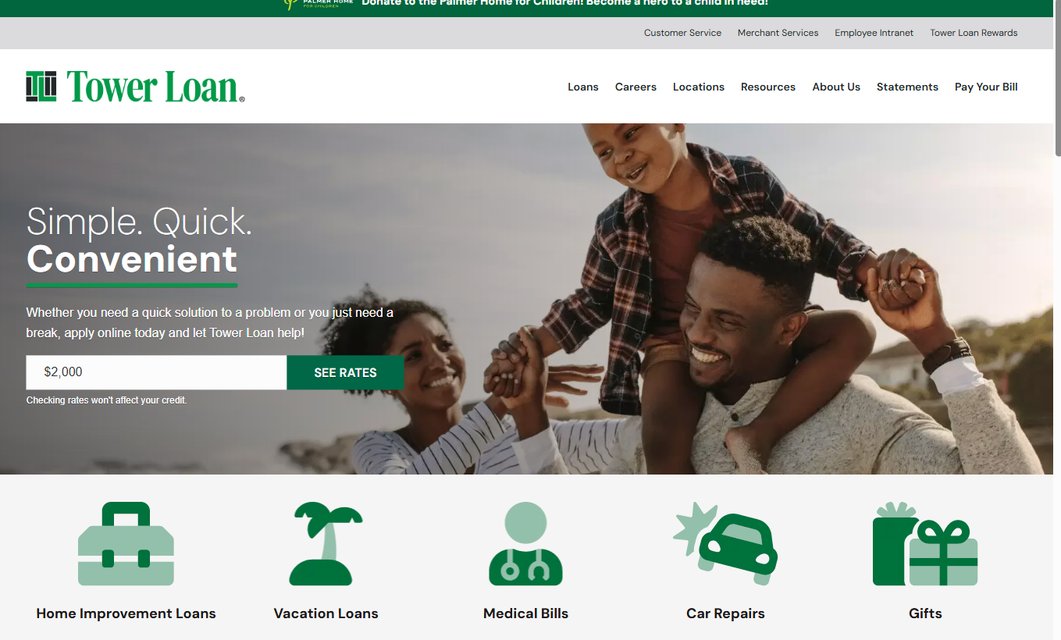
Think of Tower Loan as a hybrid service that meets you exactly where you are. If you prefer the digital route, you can grab a mid-sized loan for something like a new washing machine or a set of tires via your smartphone. These online options generally provide between $2,500 and $6,000.
Sometimes, life’s financial puzzles are too messy for a computer to solve alone. If your situation is a bit tangled, you can walk into a physical branch to speak with a real person. This face-to-face interaction opens doors to much larger sums, allowing for borrowing limits as high as $20,000.
Whether you are looking to renovate your kitchen or consolidate a mountain of small, high-interest debts into one manageable payment, they have you covered. It is a versatile way to bridge the gap between lightning-fast internet applications and the comfort of traditional customer service.
Pros:
- Branch visits unlock higher borrowing limits.
- Choose between digital or in-person assistance.
- Broad range of uses, from vacations to home projects.
Cons:
- Digital loan caps are much smaller than branch offerings.
2. IllinoisLoansToday
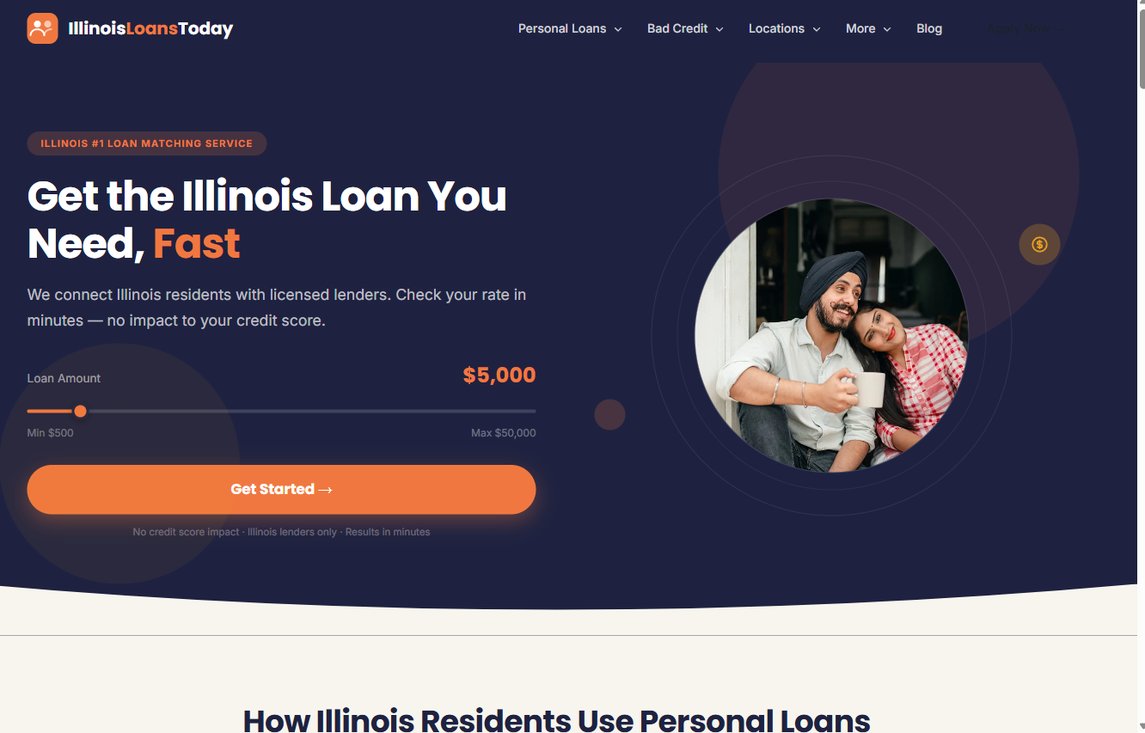
IllinoisLoansToday acts like a high-speed matchmaking service designed specifically for our state. Instead of you hunting down every lender, they connect Illinois residents with licensed professionals. It is a wonderful way to scout your options without the gut-punch of a credit score drop.
Because they use a “soft pull” method, checking your rates won’t hurt your credit standing at all. This makes it easy to shop around. From fixing a leaky roof to settling a sudden medical bill, their range is quite broad, spanning from $500 all the way up to $50,000.
The scale of their limits reflects the diverse needs of our local community. A resident in Peoria might only need a quick $1,200 for a sudden repair, while a neighbor in Naperville might seek $40,000 to consolidate significant debt.
Pros:
- Checking rates won’t ding your credit score.
- Impressive maximum limit of $50,000.
- Exclusively serves the Illinois lending market.
Cons:
- You are being referred to third-party lenders.
3. OppLoans
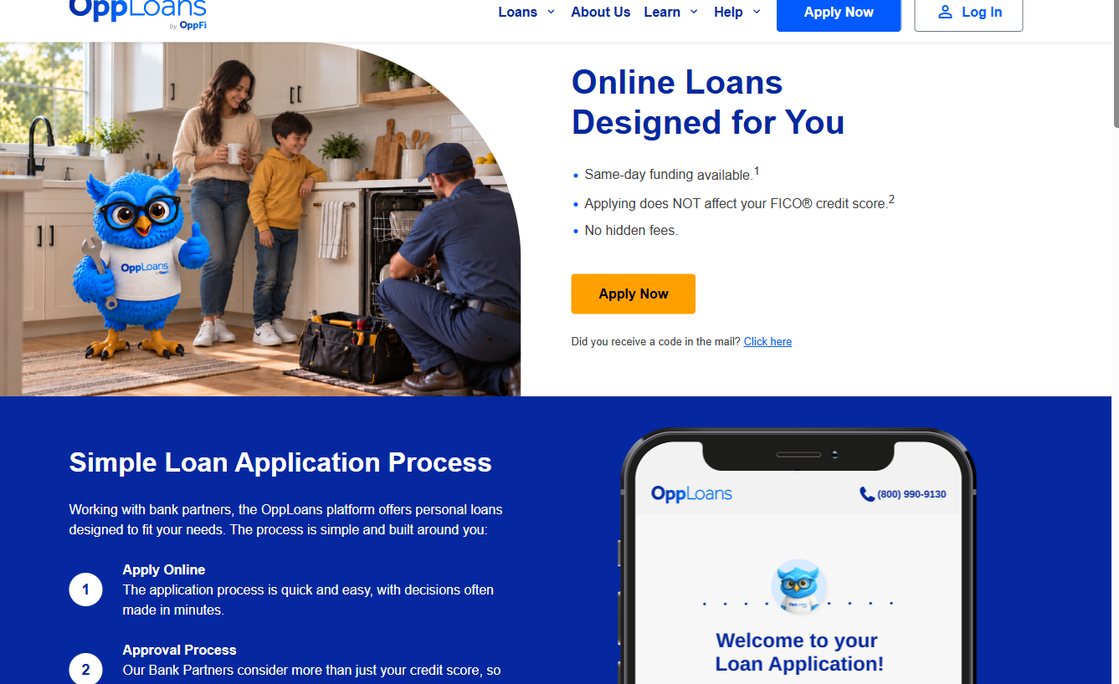
If the big banks have turned you away, OppLoans might be the lifeline you need. Their platform recognizes that real life is rarely perfect and credit histories are often messy. They look beyond just a FICO score, considering your employment stability and how you handle your existing bank accounts.
Speed is their specialty, which is vital when an unexpected car repair threatens your ability to get to work. You can often receive a decision in just a few minutes, and same-day funding is available for those in immediate need of cash.
This is especially helpful when a looming utility bill is threatening your household stability. They aim to help you keep moving forward, even when your credit isn’t exactly where you’d like it to be.
Pros:
- Applying doesn’t impact your FICO score.
- Fast funding may occur on the same day.
- Flexible standards for those with imperfect credit.
Cons:
- Maximum loan amounts are restricted to $5,000.
4. SAIL Loans
SAIL Loans plays the long game by focusing on your future financial health. Their installment loans are built to help you cultivate savings while simultaneously boosting your credit profile. It is a clever, strategic move for anyone wanting to master their money over time.
You don’t need to be a computer whiz to get started, as the application involves only three simple steps. While the $4,000 cap might seem small compared to other lenders, the real value lies in credit building.
If you are planning to apply for a mortgage in a year or two, this is a smart way to strengthen your score now. It is about laying a solid foundation for your next big financial milestone.
Pros:
- Assists with credit building and saving money.
- The three-step application is incredibly simple.
- Welcomes those with good, bad, or no credit.
Cons:
- Maximum loan amounts are lower than most competitors.
5. MaxCash
MaxCash functions as a versatile toolbox for quick liquidity. They don’t just stick to one thing; they offer everything from standard personal loans to cash advances and title loans. It is a powerhouse option if you need a very specific financial tool right away.
If you have equity in your vehicle and need money fast, a title loan might get you through the door quicker than a traditional bank loan. Their amounts are incredibly flexible, starting as low as $250 and climbing to over $10,000.
They strive to get you connected to your funds within minutes. This makes them a highly adaptable resource for plugging urgent holes in your monthly budget when you just need a quick fix.
Pros:
- Extensive range of funding ($250 to $10,000+).
- Rapid processing, often within minutes.
- Includes diverse products like title loans.
Cons:
- The variety of options might feel overwhelming.
Making the Right Choice for Your Debt
Selecting a financial partner is much like picking out a sturdy pair of hiking boots; your specific destination dictates the perfect fit. If your upcoming kitchen remodel demands a heavy-duty $15,000, you should look toward robust options such as the branch services offered by Tower Loan. Conversely, a quick fix for a dented fender might only necessitate the lightning-fast delivery of MaxCash.
It is vital not to dive headlong into a predatory interest rate simply to patch up a momentary crisis. You must scrutinize the complete price tag rather than focusing solely on what leaves your wallet each month. While a low monthly installment might seem tempting, stretching out the repayment timeline can significantly inflate the ultimate cost of your debt.
Consider a scenario where you borrow $1,000. If the terms span 24 months at a steep interest rate, that initial loan could balloon into a $1,500 total obligation by the time you finish. Always keep your eyes on the finish line to avoid being blindsided by long-term expenses.
Lastly, clearly define your objective before you click that “Apply Now” button. Are you aiming to repair your credit score via SAIL Loans, or do you need liquid cash by tomorrow using OppLoans? Perhaps you require a massive lump sum through IllinoisLoansToday or Tower Loan.
Walking into a lending scenario with a clear roadmap ensures that the funds you secure today won’t transform into a heavy anchor of anxiety tomorrow. Being prepared is your best defense against financial turbulence.
