Notice: Function _load_textdomain_just_in_time was called incorrectly. Translation loading for the wpforms-lite domain was triggered too early. This is usually an indicator for some code in the plugin or theme running too early. Translations should be loaded at the init action or later. Please see Debugging in WordPress for more information. (This message was added in version 6.7.0.) in /home/howhumansthink/public_html/wp-includes/functions.php on line 6131

Notice: Function _load_textdomain_just_in_time was called incorrectly. Translation loading for the salient domain was triggered too early. This is usually an indicator for some code in the plugin or theme running too early. Translations should be loaded at the init action or later. Please see Debugging in WordPress for more information. (This message was added in version 6.7.0.) in /home/howhumansthink/public_html/wp-includes/functions.php on line 6131

Notice: Function _load_textdomain_just_in_time was called incorrectly. Translation loading for the salient domain was triggered too early. This is usually an indicator for some code in the plugin or theme running too early. Translations should be loaded at the init action or later. Please see Debugging in WordPress for more information. (This message was added in version 6.7.0.) in /home/howhumansthink/public_html/wp-includes/functions.php on line 6131

Notice: Function _load_textdomain_just_in_time was called incorrectly. Translation loading for the salient domain was triggered too early. This is usually an indicator for some code in the plugin or theme running too early. Translations should be loaded at the init action or later. Please see Debugging in WordPress for more information. (This message was added in version 6.7.0.) in /home/howhumansthink/public_html/wp-includes/functions.php on line 6131
October 2026 – Page 401 – Will Steinberg, MD MSPH Skip to main content
Monthly Archives

October 2026

Top-Rated Providers for Bad Credit Loans Louisiana to Secure Fast Cash

By Uncategorized
Bad credit loans louisiana

Top-Rated Providers for Bad Credit Loans Louisiana to Secure Fast Cash

Last updated: 2026-10-16

Navigating your personal finances in Louisiana often feels as murky as a swamp during a heavy downpour. Many residents find that their credit ratings fail to reflect their true character or their genuine capacity for repayment. When a sudden engine failure or an unforeseen hospital invoice pops up, you crave clarity rather than more chaos.

From the bustling sidewalks of New Orleans to the tranquil parishes deeper in the state, financial stress is a common thread for many industrious Louisianans. Identifying a creditor that recognizes the nuances of a low credit score is your first step toward stability. This compilation examines various options, ranging from neighborhood credit unions to modern online platforms.

Every financial provider offers a distinct path forward. You might be hunting for a quick bridge to cover monthly expenses, or perhaps you want to merge various debts into one manageable payment. Making the smartest decision involves looking much deeper than the surface-level interest rate. You must scrutinize the specific contract details, the rules, and the various installment timelines.

  1. FastLendGo
  2. Coastline Credit Union
  3. LightStream
  4. United Finance
  5. Addition Fi
  6. GadCapital

The Criteria for Loan Approval in Louisiana

Hunting for a loan in the Pelican State is more like navigating a maze than a simple sprint. You shouldn’t just pick the first person to shout “yes.” Instead, many local institutions dig into the meat of your finances, specifically checking if your paycheck is reliable and how your monthly debts compare to what you earn.

While your credit score is definitely a piece of the puzzle, it isn’t the whole picture. Many providers focus on your employment history to ensure you can actually settle the debt. They want to see that you have the muscle to pay them back over time.

Think of it like a teacher looking at a student’s entire year rather than one bad test grade. For example, presenting bank records from the previous ninety days can prove your income is stable. This often outweighs a temporary FICO score drop caused by an unexpected hospital visit.

Timing is everything when life throws a curveball. If your vehicle’s transmission gives out on a Friday afternoon, waiting two weeks for an answer feels like an eternity. When you need to be back on the road by Monday morning, speed becomes your most important metric.

We evaluated these different services by looking at how easy they are for folks with bruised credit to access. We also weighed their maximum loan limits against the velocity of their payout process. It is vital to scrutinize the “Total Cost of Borrowing” before signing any paperwork.

Don’t let sneaky numbers catch you off guard. You need to account for the APR along with any hidden administrative charges or origination fees. Everything adds up when the final settlement comes due, so look at the full price tag, not just the monthly payment.

Company Borrowing Range APR % Payout Timing Eligibility
FastLendGo $500 – $5,000+ see site see site Bad/Fair Credit
Coastline Credit Union see site see site see site see site
LightStream see site 9.99% – 24.94% APR Next day Excellent Credit
United Finance Up to $20,000 see site see site see site
Addition Fi see site see site see site see site
GadCapital $100 – $5,000+ see site Instant No Credit Check

Premier Lending Solutions Across Louisiana

1. FastLendGo
FastLendGo – fastlendgo.com

Sometimes, the big-name banks can feel like a brick wall when your credit score isn’t quite where you want it to be. FastLendGo acts as a bridge for those navigating similar hurdles. They focus heavily on personal financing options tailored specifically for individuals with less-than-perfect credit history.

Instead of making you hop through hoops or drive across several different parishes, this platform brings the market to your screen. You can weigh your different choices without ever leaving your sofa. It is a digital-first way to shop for cash through fastlendgo.com.

Whether you are staring down an unexpected dental bill or a sudden leak in your roof, their specialized loan types can help. They cater to various needs, covering anything from a quick $500 fix to larger requests reaching $5,000. It is a lifesaver for those caught in the pinch between a sudden crisis and a future paycheck.

Pros:
  • Expertise in managing fair and poor credit scenarios.
  • Provides specific funding for medical or car repairs.
  • Streamlined comparison tool for web users.
Cons:
  • Does not offer the cozy, small-town feeling of a local credit union.

2. Coastline Credit Union
Coastline Credit Union – coastlinecu.com

In the vast ocean of finance, credit unions are the quiet, reliable anchors. Coastline Credit Union provides a banking atmosphere that feels much more like a handshake from a neighbor. If you find the massive, faceless corporations a bit cold, this organization might be your perfect match.

Because they operate as member-owned cooperatives, their primary mission isn’t about padding the pockets of distant shareholders. Instead, they prioritize serving the people who use their services. This unique structure frequently results in more accommodating and flexible terms for the members who call them home.

They offer a robust menu of products, ranging from standard loans to modern digital banking. While their entry requirements might be slightly more rigorous than a quick-cash lender, the long-term payoff is significant. Building a history with them can pave a smooth road toward securing a mortgage or an auto loan down the line.

Pros:
  • A business model built around member welfare.
  • Convenient tools via mobile and web banking.
  • Potential for superior long-term interest rates.
Cons:
  • Eligibility for membership is typically required.

3. LightStream
LightStream – lightstream.com

If your credit score is currently in the top tier, LightStream is a heavy hitter. They aren’t exactly the safety net you’d look for if you are currently sinking in debt. However, for those with a pristine financial reputation, they offer something quite special.

Their application journey is remarkably swift, ensuring they don’t waste a moment of your day. This makes them an excellent companion for major life milestones. When you’re planning something big, saving a chunk of change on interest can mean a massive difference in your overall budget.

The versatility of their platform is impressive, whether you’re remodeling your kitchen or celebrating a wedding. The speed of their funding is a standout feature, with many people seeing the cash in their accounts by the very next day. They are also a top choice for anyone looking to roll high-interest credit card debt into one manageable payment.

Pros:
  • Lightning-fast funding, often arriving within 24 hours.
  • Competitive fixed rates with added discounts for AutoPay.
  • Wide variety of approved uses for the funds.
Cons:
  • Only accessible to those with top-tier credit scores.
  • Not a viable option for borrowers with poor credit.

4. United Finance
United Finance – unitedfinance.com

United Finance is a true veteran of the lending industry, boasting a history that dates back to 1922. In an era of fleeting fintech apps, they offer a sense of permanence and stability. They provide both auto and personal loans that are designed to play well with a realistic monthly budget.

Having weathered everything from the Great Depression to the rise of the internet, their longevity speaks volumes. They have mastered the art of staying steady through every economic storm. Their approach is centered on making the borrowing process straightforward and highly accessible for everyone.

When you work with them, you aren’t just a number; you get a dedicated team of friendly lenders to guide your way. This human touch is a godsend if you find online forms overwhelming. It is particularly beneficial for self-employed individuals or those with complex income streams that might get lost in an automated system.

Pros:
  • Massive institutional experience and proven stability.
  • Personal loan amounts can reach up to $20,000.
  • Provides both refinancing and auto loan options.
Cons:
  • A more traditional workflow might be slower than digital-only apps.

5. Addition Fi
Addition Fi – additionfi.com

Addition Financial focuses on empowering its members to expand their personal wealth while managing daily life. Rather than being just another place to borrow, they function as a holistic financial partner. They aim to be your one-stop shop for all things monetary.

From the day-to-day utility of checking accounts to the complexities of investment options, they cover it all. Having your entire financial ecosystem in one single place makes tracking your savings and spending habits much simpler. It takes the guesswork out of your monthly financial overview.

They offer very competitive rates and champion a community-centric way of banking. If you are looking to step away from the big national banks toward something more personal, Addition Fi provides the necessary toolkit. They support you through every season, from your very first car loan to your eventual retirement planning.

Pros:
  • An all-in-one suite of investment and banking tools.
  • Community-focused referral incentives.
  • Strongly competitive rates across many products.
Cons:
  • Full access to benefits requires membership.

6. GadCapital
GadCapital – gadcapital.com

When you find yourself in a tight spot and the clock is ticking, GadCapital acts as that “break glass in case of emergency” tool. They specialize in quick-turnaround installment and payday loans for people facing credit challenges. They are designed for rapid deployment when traditional banks simply say “no.”

This is a highly specialized service for moments of extreme urgency. If a standard three-day waiting period for approval feels like an eternity, GadCapital is built for this specific pressure. They handle the high-stress moments when you just need immediate relief.

Their platform allows for very small, rapid loans, starting at the $100 mark. If you are facing a utility shut-off or an urgent medical co-pay, they are built to assist without a long-winded credit check. However, you must be incredibly disciplined with your repayments to avoid getting trapped in a high-interest cycle.

Pros:
  • Certain loan types require no credit checks.
  • Provides nearly instant access to cash.
  • Loan amounts range from $100 to over $5,000.
Cons:
  • Payday-style structures often carry very high costs.
  • Potential to enter a debt cycle without careful management.

Calculating Your Actual Debt Expense

It is incredibly easy to get blinded by a low monthly installment figure when you are in a pinch. You might see a $500 loan and a $50 monthly bill and think you have struck gold. However, math has a way of biting back when you aren’t looking.

If those $50 payments stretch across a full year, you end up shelling out $600 total. That extra $100 represents a 20% markup on the original amount you borrowed. It is like buying a steak but finding out you have to pay for the plate, the silverware, and the waiter’s tip too.

Before you put pen to paper, demand to see the “Total Repayment Amount” from your lender. This specific number acts as your financial North Star. It reveals the exact amount of hard-earned cash that will have vanished from your bank account by the time you are officially debt-free.

Don’t let the “nominal interest rate” fool you into a false sense of security. This number is often a sleight of hand used by lenders to make deals look sweeter than they actually are. It ignores the hidden sting in the tail of the contract.

You need to focus your attention on the Annual Percentage Rate, commonly known as the APR. This figure is much more honest because it wraps the interest rate and various administrative costs into one single number. It accounts for those pesky processing or origination fees that sneak in during the application phase.

When you are shopping around between different lenders, let the APR be your ultimate guide. A provider might promise a lower interest rate but bury you in upfront service charges. Always choose the option with the lowest APR, as it represents the most truthful cost of your borrowed capital.

How to Get Ready for Your Loan Request

Navigating the path to approval doesn’t have to be a headache if you play your cards right. Think of it as setting the stage before the curtain rises on your application.

By taking a few proactive steps, you can significantly boost your odds of landing a favorable rate. It is much better to walk in prepared than to stumble through the process blindfolded.

Follow these three essential habits to ensure your submission is as strong as possible:

  1. Review Your Paperwork: Start by rounding up your latest W-2 forms, pay stubs, and even basic utility statements. Lenders need solid evidence regarding your living situation and steady earnings to feel confident in your profile.
  2. Having these items organized and ready for a quick upload can turn a multi-day waiting period into a mere matter of minutes.

  3. Scrutinize Your Credit Profile: Utilize complimentary resources like AnnualCreditReport.com to peek inside your file. If you spot a mistake—like an old, settled debt still appearing as unpaid—don’t just sit there; dispute it right away.
  4. A tiny inaccuracy can be the bridge between a 650 score and a 620 score, so precision is your best friend here.

  5. Determine Your DTI Percentage: Sum up every monthly debt you owe, including car loans, rent, and minimum credit card payments. Then, divide that total by your overall gross monthly income to find your Debt-to-Income (DTI) ratio.
  6. Keep in mind that most lenders prefer to see a DTI falling somewhere between 36-43%. Knowing this specific figure helps you gauge exactly how much extra borrowing you can actually handle without drowning in interest.

Steering Through the Lending Landscape

Before putting pen to paper, pause and scrutinize the small text. It is incredibly tempting to dive headfirst into an immediate approval, yet the real story lies in the cumulative expense of the debt. Do not merely focus on what you owe each month; instead, dissect the APR to grasp the actual price of your borrowed funds.

Mistakenly disregarding the fallout from tardy installments is a frequent stumble. Even when a company accepts your poor credit score, missing a deadline is like a pebble in your boot, creating discomfort for a long duration. You must guarantee that every installment fits snugly into your current financial plan, allowing enough leftover cash for basic necessities like food and housing.

Maintaining a “safety net” within your monthly spending is your primary shield against unexpected life events. Without this cushion, you might find yourself back in the deep end when a car repair or medical bill arrives. Financial stability requires a bit of breathing room to avoid a downward spiral.

Beware the siren song of the “instant solution.” While rapid options, such as payday loans provided by GadCapital, can pull you from a sudden crisis, they often snowball into a massive debt mountain if handled recklessly. Treat these funds as a last resort, reserved only for genuine emergencies that cannot wait.

Whenever possible, aim for more permanent financial structures like credit unions or personal loans from reputable organizations. Relying on short-term fixes is a band-aid on a much larger wound. Instead, focus on the long game by consistently meeting your deadlines to repair your standing.

Cultivating a track record of punctual repayments remains your most powerful tool for escaping a credit deficit. It is the most reliable ladder to reach a state of enduring fiscal independence. Patience and discipline are your best allies in this marathon.
Apply for Fast Bad Credit Loans Arizona Today

By Uncategorized
Bad credit loans arizona

Apply for Fast Bad Credit Loans Arizona Today

Last updated: 2026-10-17

Weathering the blistering Arizona sun is a feat in itself, but a sudden financial blow can feel like a sudden sandstorm hitting you off guard. Sometimes, a sudden hospital bill or a mechanical failure in your vehicle arrives right when your credit score is at its absolute lowest.

You deserve a financial partner that prioritizes your personal circumstances over a mere numerical rating. When a Phoenix July brings a broken air conditioner or a Tucson legal emergency strikes, liquidity becomes a matter of survival rather than a luxury.

Navigating these crises requires a roadmap that avoids the pitfalls of predatory lending practices. It is incredibly important to weigh your various alternatives before the ticking clock of a looming deadline pushes you toward a questionable agreement.

Our curated selection features lenders who truly grasp the lifestyle and struggles of Valley of the Sun residents. We prioritized lightning-fast processing times and transparent contract language above everything else during our research process.

Securing a quick $500 for an auto repair might appear trivial, yet poor calculations can easily escalate that into a $1,500 nightmare. We judged these companies by their operational speed and their transparency regarding the final price tag.

You should never be left in the dark about what a loan actually costs you in the long run. It is about getting the funds you need today without being tethered to debt for the next ten years.

  1. NBA Arizona
  2. Arizona Zip Loan
  3. Sun West
  4. Arizona Financial
  5. Cash Time

Our Review Process for Desert State Lenders

Our team scoured the landscape from Phoenix to Sedona to see how accessible financial aid truly is. We specifically focused on the speed of fund distribution and the variety of options tailored for those with bruised credit scores. You shouldn’t need a mountain of gold to secure a fair deal when life hits a rough patch.

It is vital to distinguish between a massive banking institution and a niche lending specialist. While traditional banks typically demand stellar FICO scores and a long history of steady employment, they can be quite stubborn. On the other hand, specialized lenders often weigh collateral or alternative repayment proof, which can open doors much quicker.

We took a deep dive into the current inventory offered by these firms. This investigation included reviewing maximum loan amounts, specific product categories—such as personal or title loans—and the overall user experience during the signup process. We searched for those annoying “friction points” that trip people up, such as endless piles of paperwork or being left on hold for days.

Our ultimate aim is to provide a reliable compass so you don’t lose your way when cash is tight. We want to save you from the migraine of convoluted documentation and the agony of waiting forever for a response.

Company Borrowing Limits Time to Funds Eligibility Criteria
NBA Arizona See site See site See site
Arizona Zip Loan Up to $25,000 24hrs Average See site
Sun West See site See site See site
Arizona Financial See site See site See site
Cash Time $100 – $100,000 As fast as 15 Minutes No Problem

Premier Arizona Lending Institutions for Credit Struggles

1. NBA Arizona

NBA Arizona – nbarizona.com

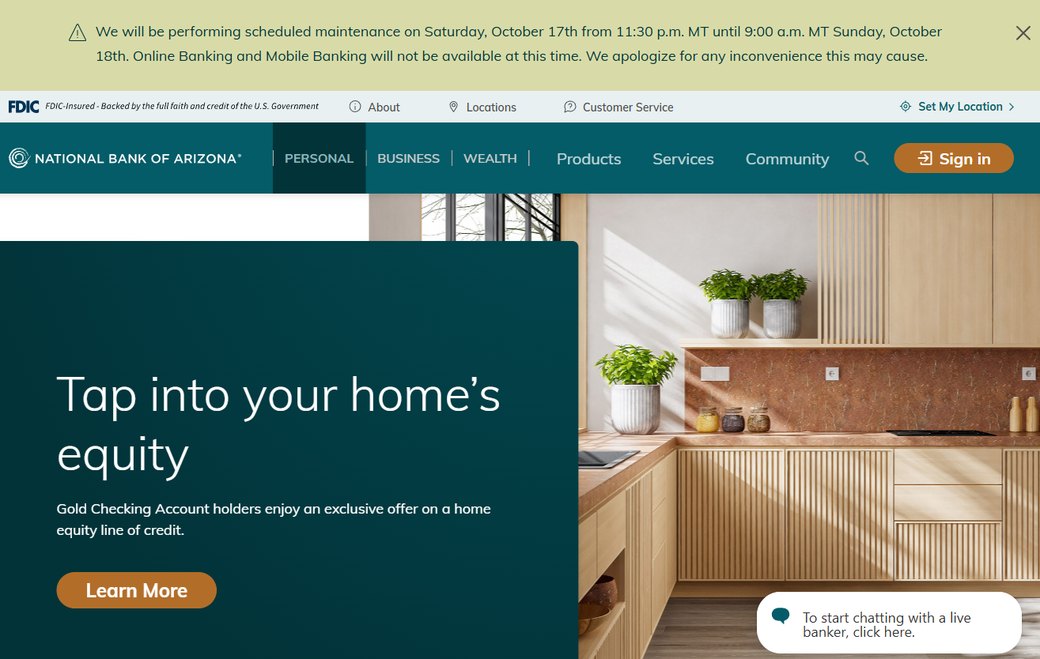
If you want a financial foundation rather than a temporary band-aid, NBA Arizona is a powerhouse. This FDIC-insured entity provides much more than just quick cash. They offer a vast spectrum of banking services designed for long-term stability and growth.

From basic everyday checking accounts to sophisticated retirement strategies and wealth management, they have it all. Because they are backed by the U.S. Government, your deposits remain safe up to the maximum legal limit. It is peace of mind you won’t find at a fly-by-night lender.

For those sitting on home equity in Mesa or Scottsdale, this institution is a goldmine. Gold Checking Account members can tap into special HELOC opportunities. Turning your living space into a financial asset can help you renovate or wipe out old debts through lower interest rates.

Pros:

  • Protected by FDIC insurance and federal backing.
  • Exclusive benefits for Gold Account holders.
  • Extensive services for retirement and wealth building.

Cons:

  • Premium products often demand superior credit scores.
  • Not the ideal choice for immediate, small-dollar emergency cash.

2. Arizona Zip Loan

Life in the Grand Canyon State moves fast, and Arizona Zip Loan keeps pace. Whether you are navigating the bustle of Phoenix or enjoying the Sedona views, they bridge the gap between slow traditional banks and your urgent needs.

They are the perfect ally for sudden medical bills, urgent home repairs, or unexpected crises. Their streamlined digital and telephone application process ensures you aren’t stuck waiting weeks for a human to glance at your paperwork. It is built for pure efficiency.

Local families have given them a glowing 4.9-star rating, which speaks volumes. People turn to them during their most stressful moments because they need a hand that moves quickly and reliably.

Pros:

  • Approvals often arrive within a 24-hour window.
  • An impressive 4.9-star rating from local customers.
  • Funding ranges from $1,000 up to $25,000.

Cons:

  • Final approval depends on their internal credit standards.
  • Monthly payments are fixed and may be tight for some.

3. Sun West

Sun West – mysunwest.com

Sun West Credit Union operates on a different philosophy. Since they are owned by their members, they possess a deep-rooted commitment to the local community. They view your personal success as a win for the entire group.

Their menu of options is massive, featuring high-yield savings, money market accounts, and intricate mortgage products. They aim to be the only financial partner you ever need, from your first car purchase to your final forever home.

If you are currently battling a low credit score, their secured credit builder tools are a total game-changer. By providing a small cash deposit as collateral, you create a safety net for the lender while proving your reliability to credit bureaus.

This method allows you to climb out of a credit hole without the heavy risks of unsecured borrowing. It is a steady, disciplined way to boost your score over time.

Pros:

  • A wide array of products from savings to mortgages.
  • Specialized tools designed to repair and build credit.
  • Convenient options for both digital and in-person banking.

Cons:

  • You might need to meet specific membership requirements.
  • Interest rates depend on your unique credit history.

4. Arizona Financial

Arizona Financial – arizonafinancial.org

Arizona Financial is geared toward life’s major milestones. They realize that every financial journey is unique, which is why they provide flexible paths for debt consolidation, vehicle purchases, or buying a home. Their mortgage experts specialize in navigating the complex parts of the process.

They take the mystery out of confusing terms like closing costs, points, or escrow accounts. For a first-time buyer in a growing suburb, having an expert to translate these details can prevent a total financial disaster.

Whether you are looking to refinance for a better rate or buy your first house, they offer the guidance necessary to succeed. They know the local landscape intimately, from the stability of older neighborhoods to the surging prices in Tempe.

Pros:

  • Deep expertise in refinancing and home ownership.
  • Tailored options for various stages of life.
  • Professional mortgage officers to guide your way.

Cons:

  • The heavy mortgage focus might not suit quick cash needs.
  • Home loans likely require a more established credit profile.

5. Cash Time

Cash Time – cashtime.com

When you are in a real bind and the clock is ticking, Cash Time is a heavy hitter. They specialize in registration and title loans, which is perfect for those who cannot wait days for a bank’s decision. You get cash in hand almost instantly, but there is a catch.
Because a title loan uses your vehicle as collateral, your ride is at stake if you miss a payment. It is a lightning-fast solution, but you must tread carefully to protect your transportation.
They offer massive loan amounts, anywhere from a small $100 up to a whopping $100,000. Their “no problem” stance on bad credit makes them highly accessible for people who have been rejected everywhere else.
Just keep in mind that this level of accessibility usually comes with a higher interest rate. Always weigh that cost carefully before signing the dotted line.

Pros:

  • Lightning-fast approvals, sometimes in just 15 minutes.
  • Extremely high limits, reaching up to $100,000.
  • Specifically designed for those with poor credit.

Cons:

  • Your vehicle must be used as collateral for the loan.
  • Rapid-funding options often carry very high interest rates.

The Real Price of Your Loan

It is easy to get caught up in the excitement of a low monthly bill. At first blush, a $50 installment seems like a dream compared to a $200 commitment. However, those numbers are often a double-edged sword that can cut your budget deep.

A smaller payment often means you are dancing with debt for a much longer period. While that $200 chunk might vanish in just 6 months, the $50 option could linger on your bank statement for 5 long years. This delay turns a quick fix into a long-term anchor.

When you stretch out the timeline, you end up footing the bill for a much larger sum than you originally borrowed. This figure represents the “total cost of credit.” It is the only metric that truly reflects how much money is leaving your pocket in the long run.

Don’t let the monthly figure blindside you; always keep your eyes on the horizon of the entire loan term.

To uncover the truth, you must demand the Annual Percentage Rate (APR). Think of the interest rate as the tip of the iceberg, while the APR reveals the massive weight lurking beneath the surface. It accounts for both interest and any mandatory service fees.

Imagine a lender promises a 10% interest rate but adds a sneaky $500 fee to the contract. In reality, your APR will skyrocket far beyond that initial 10%. The math changes once those extra costs are baked into the total percentage.

When shopping around for the best terms, use the APR as your primary yardstick. Comparing different offers based on this number is the smartest way to ensure you aren’t getting the short end of the stick.

Steps to Ready Your Loan Request

If an urgent need for cash is looming on the horizon, taking proactive measures today can significantly boost your success rate. Think of this preparation as a roadmap through a financial storm. By getting your ducks in a row now, you prevent future headaches and pave a smoother path toward your fiscal goals.

Start by organizing your essential documentation. Most creditors in the Grand Canyon State will require specific evidence to verify your background. You should gather your paperwork well in advance to avoid any sudden delays during the approval process.

Typically, you will need to present several key items to prove who you are and what you earn:

  • A current Arizona driver’s license or a state-issued ID to prove your identity.
  • Evidence of your earnings, such as your two most recent W-2 forms, pay stubs, or bank records.
  • A recent bill for water or electricity to verify where you currently live.
  • Records of any existing liabilities if you intend to consolidate those specific debts.

Next, pull your own credit profile to see what the banks see. You can secure a no-cost report from the primary bureaus to review your standing. If any inaccuracies pop up—such as a collection that doesn’t belong to you—get those errors fixed right away.

Even a single tiny blunder can slash your score by as many as 50 points. This sudden dip could be the difference between getting a great deal at Arizona Zip Loan and facing rejection or higher costs from Sun West. Stay vigilant about your data.

Lastly, pin down the exact amount of funding you truly require. It is incredibly tempting to pad the request with extra cash “just in case,” but this choice only serves to drive up your total interest payments. Don’t let a small loan turn into a massive burden.

Suppose your car needs a new transmission that will run you $1,200. In that scenario, you shouldn’t request $2,000 from a lender. Asking for more than the actual cost is like jumping into a whirlpool; it creates a cycle of debt that is notoriously difficult to escape.

Do not let the sudden sight of a massive windfall blind you to the fine print. It is incredibly easy to get swept up in the excitement of a quick cash injection, but the true narrative lies in what that capital actually costs you in the long run. Before you put pen to paper, scrutinize every detail carefully.

You should actively inquire about the cumulative expense of the debt and any sneaky charges lurking in the shadows. Specifically, keep a sharp eye out for “prepayment penalties.” Some creditors will actually slap a fee on your head if you attempt to settle the balance ahead of schedule, effectively penalizing your financial discipline.

It sounds like a bitter pill to swallow, but being a diligent borrower shouldn’t come with a surcharge. You want a lender that cheers your progress rather than one that profits when you try to get out of debt faster. Always demand transparency regarding the total amount you will have paid by the time the final installment is made.

Avoid the trap of juggling several different lines of credit simultaneously. This habit often triggers a “debt spiral” that can feel like an inescapable whirlpool. If you find yourself grabbing a title loan to wipe out a credit card, only to take a personal loan to cover that title loan, you are merely spinning your wheels.

In that scenario, you are essentially paying interest on top of interest, which is a recipe for disaster. Instead, aim for a singular, streamlined solution that aligns with your monthly cash flow. A predictable, manageable payment schedule is the cornerstone of maintaining your sanity and your bank account balance.

If you look ahead and can’t visualize yourself meeting the monthly obligations for a full twelve months without sweating, the loan is likely too heavy. Don’t take on more than your shoulders can bear. It is better to seek a smaller amount now than to drown in a sea of mounting interest payments later.

Best HVAC AC Financing Plans to Purchase Your New System Today

By Uncategorized
Hvac ac financing

Best HVAC AC Financing Plans to Purchase Your New System Today

Last updated: 2026-10-16

When a scorching heatwave arrives or freezing drafts start dancing through your floorboards, a failing climate control system feels like a bolt from the blue. It is a stressful situation that catches most families off guard. Rarely do people keep thousands of dollars tucked away in a savings jar specifically for a new condenser or furnace.

This is where tailored financing serves as a vital lifeline. It bridges the gap between a malfunctioning unit and a cozy, climate-controlled living space. Instead of sweating through a summer or shivering in the winter, these loans allow you to tackle repairs without breaking the bank all at once.

Selecting the best method to fund these critical home updates involves more than just glancing at a monthly bill. You must balance how quickly you can access cash against the total interest you will pay over time. It is a delicate dance of managing your immediate cash flow and protecting your credit rating.

We have carefully reviewed several different lenders to simplify your decision-making process. Our goal is to help you navigate the landscape of 2026’s financial options. This comparison highlights the best paths to keep your home comfortable while staying on track with your overall fiscal goals.

  1. Hearth
  2. JetzLoan
  3. Flexxbuy
  4. AmeriCash Loans
  5. Roadrunner Financial
  6. NetCredit

How to Select the Right Financing for Your HVAC Needs

Securing funds for home climate systems is a different beast than car shopping or grabbing a small personal loan. When your AC breaks down, it isn’t just an inconvenience; it is a crisis. You can’t afford to sit around for a fortnight while a bank scrutinizes your tax returns and income proofs.

This comparison breaks down how fast you can get cash in hand and the level of credit history you’ll need to cross the finish line. Some lenders live for large installment loans. Other specialists focus on lightning-fast, short-term advances or lease-to-own setups for folks with thin credit files. Finding the right match for your specific repair emergency is key.

Lender Maximum Loan Speed of Funds Credit Profile
Hearth see site see site see site
JetzLoan $35,000 As little as 24 hours No hard credit pull
Flexxbuy $100,000 Next business day Credit Select (35+ lenders)
AmeriCash Loans see site Instant decision Good credit not needed
Roadrunner Financial see site Two minutes All credit welcome
NetCredit $10,000 Same-day funding available Flexible terms

1. Hearth

Hearth – hearth.com

Hearth acts as a dedicated hub for homeowners aiming to boost their home’s energy efficiency. Instead of focusing solely on the transaction, this platform provides a mountain of data regarding pellet stoves, wood stoves, and various eco-friendly heating tools. It is a gathering place for people making smart, safe, and clean fuel decisions.

If you are the type of homeowner who likes to study the details before signing a contract, this is for you. Rather than just grabbing a loan, you can explore deep discussions and community forums to weigh the long-term value of your hardware. It is essentially a research-first method to upgrading your home.

Pros:

  • In-depth community forums for technical expertise.
  • Emphasis on sustainable and energy-saving gear.
  • Helpful historical insights on different heating fuels.

Cons:

  • Functions more as an advisory tool than a primary lender.

2. JetzLoan

JetzLoan – jetzloan.com

When your living room starts feeling like a furnace, every second counts. JetzLoan is tailor-made for the person who needs their bank balance to reflect the necessary funds yesterday. They prioritize rapid service and simplicity, linking you with premier lenders in moments without a stressful hard credit inquiry during the start.

They have trimmed the fat to ensure you aren’t buried under a mountain of paperwork. With the possibility of seeing your money in as little as 24 hours, they act as a high-speed lifeline during unexpected furnace or AC failures. It is a no-nonsense path for those who value quick results over complex math.

Pros:

  • Initial rate checks won’t trigger a hard credit pull.
  • Incredible speed, with funding potentially within 24 hours.
  • Large borrowing capacity of up to $35,000.

Cons:

  • The actual timing of funds depends on your specific matched lender.

3. Flexxbuy

Flexxbuy – flexxbuy.com

For contractors and businesses installing premium, high-ticket HVAC units, Flexxbuy provides a polished way to secure the sale. They function as a massive multi-lender network, allowing buyers to view numerous different options via one single application. This transforms an intimidating, massive invoice into small, monthly payments that are much easier to manage.

This is a game-changer for growing a business by helping customers say “yes” to top-tier equipment. With limits reaching up to $100,000, they handle the heavy lifting for massive residential or commercial projects. The rapid decision-making process ensures that construction or installation projects stay on schedule.

Pros:

  • Extensive loan ceilings of up to $100,000.
  • Instantaneous decision-making.
  • Connection to a broad network featuring over 35 lenders.

Cons:

  • The platform is primarily built for businesses to offer to their clients.

4. AmeriCash Loans

AmeriCash Loans – americash.com

Sometimes, walking into a standard bank feels like hitting a brick wall. AmeriCash Loans is built for those who need to keep moving immediately but might not meet strict bank criteria. They specialize in marketplace lending and quick cash advances, helping people find a lender that actually fits their unique financial profile.

The application is built to be both secure and incredibly simple, navigating through a marketplace to find your match. It serves as a vital fallback for those needing to act now despite having less-than-perfect credit. While they act as a marketplace rather than a single bank, they provide a direct route to quick decisions.

Pros:

  • Possibility of receiving an instant approval.
  • You don’t need a perfect credit score to apply.
  • The application is easy and user-friendly.

Cons:

  • Specific requirements and terms are set by the individual marketplace lenders.

5. Roadrunner Financial

Roadrunner Financial – roadrunnerfinancial.com

Roadrunner Financial takes a very specific approach to lending, often focusing on recreational equipment or various vehicle types. Regardless, their “all credit welcome” mindset makes them a flexible option for people hunting for fast, customized loan offers. They aim to strip away the annoying haggling often found at the checkout counter.

The process for checking your prequalification is incredibly brisk, often taking just two minutes. This allows you to see your potential options without any commitment or a dent in your credit score. It is a low-stakes way to weigh your financial choices before you dive into a major repair or purchase.

Pros:

  • Checking your prequalification won’t hurt your credit score.
  • The process is lightning-fast at roughly two minutes.
  • They are open to all types of credit scores.

Cons:

  • Much of their service is specifically focused on recreational or vehicle categories.

6. NetCredit

NetCredit – netcredit.com

NetCredit views itself as a modern departure from old-school banking, operating on the belief that you are much more than just a number on a screen. They provide lines of credit and personal loans with a level of flexibility that rigid, traditional banks struggle to offer. It is a more human-centered way to handle digital lending.

If you need up to $10,000 to get your cooling system back online, NetCredit offers a path that could result in same-day funding. Their use of sophisticated algorithms allows for a much more detailed look at your ability to pay back the loan, which can be a lifesaver for those who fall just outside the typical FICO boxes.

Pros:

  • Offers the possibility of receiving funds the same day.
  • Provides flexible loan amounts and terms up to $10,000.
  • Uses a more detailed method for assessing credit.

Cons:

  • Loan availability depends on your specific state’s laws and local partnerships.

Choosing the Right Payment Plan

When the scorching summer sun beats down and your cooling system finally gives up the ghost, panic often sets in. It is incredibly easy to jump the gun on a deal when you are sweating through your shirt. You might find yourself tempted by quick lease-to-own arrangements just to get immediate relief.

However, don’t let desperation lead you down a rocky path. While getting approved for a lease-to-own scheme might feel like a walk in the park, the long-term price tag can be a real gut punch. You might find that a standard loan is actually the much smarter, more economical way to go in the long run.

Always demand a transparent breakdown of what the entire project will actually cost you. A tiny monthly bill might seem like a dream at first glance, but there is a catch. If the repayment period stretches to 96 months, you could end up paying triple the value of the machine.

Take the time to shop around and weigh the interest rates from various lenders. It is vital to hunt for any sneaky, undisclosed charges that might pop up in the fine print. Never let a “low cost” monthly payment blind you to the total financial weight of the debt.

Another trap many homeowners fall into involves neglecting to vet the service provider. A stellar interest rate means nothing if the person coming to your house isn’t properly certified. You don’t want a “cheap” fix that turns into a legal nightmare because the technician lacks insurance.

Make sure your funding is linked to an established, trustworthy professional. Before you ink any official paperwork, insist on a written, detailed estimate from your contractor. This ensures that what you sign for matches exactly what shows up on your doorstep during installation.

Top-Rated Bad Credit Loans Pennsylvania: Fast Cash Approval Today

By Uncategorized
Bad credit loans pennsylvania

Top-Rated Bad Credit Loans Pennsylvania: Fast Cash Approval Today

Last updated: 2026-10-16

Financial emergencies rarely knock before they enter. You could be cruising through Allentown on a stormy Tuesday when your transmission suddenly decides to quit on you. Suddenly, you are staring down an astronomical medical bill from a surprise ER trip. Or perhaps a brutal Pennsylvania winter arrives, driving your utility bills into the stratosphere. These unexpected bumps in the road are stressful enough on their own. However, things turn truly dire when a lackluster credit score blocks your access to the funds required to keep your home running.

If high balances or missed payments have taken a toll on your FICO score, big banks will likely slam their doors. They tend to function as gatekeepers rather than partners during a crisis. This forces many local residents to scan the horizon for alternative lifelines. Subprime lending is the logical next step, but it is a double-edged sword that requires a vigilant approach. You must tread carefully to ensure that the loan you select doesn’t trigger a fresh wave of financial turmoil next month.

When the need for immediate cash hits, your perspective changes overnight. You might stop hunting for the lowest possible APR and focus solely on finding a lender who accepts your specific credit history. It is a classic survival move, but it requires a clever strategy to stay in the driver’s seat. You need to navigate these options with a clear head to avoid falling into a trap.

  1. GadCapital
  2. FastLendGo
  3. Credit Human
  4. GreendayOnline
  5. Loanz
  6. OppLoans

Comparing Lending Solutions Throughout Pennsylvania

Scouring the Keystone State for a reliable lender requires looking well beyond the flashy digital ads or the neon lights of city centers. You must investigate their specific credit evaluation methods, the actual speed of fund transfers, and the total borrowing capacity available when life hits the fan. A family in Erie will likely have vastly different requirements than a resident in Philadelphia.

A daily commuter might simply need a quick infusion of cash for a sudden car repair to keep their job. Conversely, a local entrepreneur might require a bridge loan to cover staff wages until a pending contract finally settles. This list evaluates the unique needs of Pennsylvanians facing these urgent hurdles. We prioritized rapid fund delivery and the availability of installment-style repayment models.

Avoiding the endless cycle of debt remains the primary objective for savvy borrowers. A standard payday loan requiring total repayment in just fourteen days can quickly devolve into a permanent trap of constant renewals. Installment loans often represent a wiser path forward because they provide a predictable monthly schedule that aligns with a standard salary. It is the vital difference between a momentary patch and a lifetime of financial struggle.

Provider Borrowing Limits Credit Standards Payout Timing
GadCapital $100 – $5000+ No Credit Check Instant/Same Day
FastLendGo $500 – $5000+ Bad Credit Welcome Quick Access
Credit Human From $500 No Credit Review See Site
GreendayOnline $100 – $5000 No Hard Credit Check Same Day
Loanz $100 – $10000 See Site Quick/Convenient
OppLoans See Site Does not affect FICO Same-Day Funding

1. GadCapital

GadCapital – gadcapital.com

GadCapital functions as an immediate financial lifeline for those navigating sudden crises. They provide alternatives that bypass traditional credit inquiries, making them an ideal choice for a Pittsburgh resident facing an overdue rent notice or an unexpected utility spike. Their operational model moves significantly faster than the sluggish, red-tape-heavy verification typical of large national banks.

The platform accommodates everything from tiny $100 advances to substantial sums exceeding $5000. This versatility is crucial. A $100 loan might just cover fuel and a few groceries, whereas a $5000 loan could tackle a major emergency. It is a specialized option for anyone needing to skip the intense scrutiny of conventional lenders for a fast digital payout.

Pros:
  • Many options require no credit checks
  • Substantial maximums reaching $5000+
  • Rapid, immediate online application workflow
Cons:
  • Extreme urgency can result in costly terms

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo serves as a flexible partner for a wide range of personal finance scenarios. They do not limit their scope to just one type of borrower. Instead, they offer solutions for dental work, vehicle repairs, and even fixing a leaking roof. This breadth of service makes them a helpful starting point for anyone uncertain which specific product suits their unique needs. (fastlendgo.com)

Whether you are seeking a $500 bridge to your next payday or a $5000 personal loan for debt consolidation, they work to make local comparisons effortless. This is a fantastic fit for homeowners facing unexpected household emergencies, such as a broken HVAC unit during a sweltering Pennsylvania summer.

Pros:
  • Broad array of loan purposes
  • Accommodates various credit tiers from fair to bad
  • Easy-to-use online comparison system
Cons:
  • Functions as a comparison engine rather than a lender

3. Credit Human

Credit Human – credithuman.com

If your priority is the reliability of a member-driven institution, Credit Human offers a distinct alternative. They provide both secured and unsecured paths, enabling members to borrow at least $500 through more conventional repayment models. Because they function as a credit union, they generally prioritize your actual ability to pay back the money over a simple credit score.

This makes them an excellent pick for long-term financial planners aiming to improve their stability while resolving current debt. With terms reaching up to 72 months, monthly obligations become much more manageable for tight budgets. Rather than facing a massive single payment in a fortnight, you can pay small, steady amounts to protect your cash flow.

Pros:
  • Member-owned model reinforces community-centric values
  • Adaptable repayment cycles up to 72 months
  • Certain products require no credit review
Cons:
  • Most perks require official membership

4. GreendayOnline

GreendayOnline – greendayonline.com

GreendayOnline is engineered for sheer velocity. If you are staring down a mountain of mounting bills and demand answers quickly, this site moves through the workflow in mere minutes. Their mobile-optimized interface is particularly helpful, as many people in a crisis might be applying for these services on their smartphones while on the move.

Their installment loans range from $100 to $5000. By utilizing a “soft pull” method that avoids hard credit inquiries, you can assess your eligibility without further damaging your credit score. This cautious approach is vital for anyone who is protective of their long-term financial standing and wants to see their options before committing.

Pros:
  • Quick decisions on approvals
  • Hard credit checks are not required
  • Funds can be sent the same day
Cons:
  • Fully digital model may feel impersonal

5. Loanz

Loanz – loanz.com

Loanz specializes in the art of debt consolidation. If your financial stress stems from managing too many different monthly obligations—such as several credit cards paired with a medical bill—this lender helps you merge them into one singular, digestible payment. Through consolidation, you swap out chaotic, multiple due dates for a single, organized schedule.

Offering borrowing limits as high as $10,000, they provide a way for borrowers to reclaim control. This is a strategic move for those looking to reorganize their financial future instead of merely applying a temporary bandage. You aren’t just trying to survive the month; you are building a more structured life.

Pros:
  • Strong emphasis on consolidating debt
  • High borrowing limits up to $10,000
  • Useful for travel, weddings, or home projects
Cons:
  • Larger amounts might necessitate more paperwork

6. OppLoans

OppLoans – opploans.com

OppLoans operates through an established network of banking partners. One of their standout features is the option to apply without impacting your FICO rating. This is a massive weight off the shoulders of anyone monitoring their credit closely. While many lenders use hard inquiries that can dent your score, OppLoans bypasses that step during the initial phase.

They offer same-day funding for individuals in urgent need. It is a practical solution for consumers who need a short-term bridge to reach their next paycheck without the fear of a score drop. This makes them a powerful choice for filling temporary gaps that only require a few hundred or a few thousand dollars.

Pros:
  • Application process does not hit FICO scores
  • Available same-day funding
  • Transparent and simple application steps
Cons:
  • Approval hinges on specific bank partner criteria

Calculating the Real Financial Burden

Before you ink your name on a contract, do the heavy lifting with some quick arithmetic. Borrowing with less-than-perfect credit often means facing much steeper Annual Percentage Rates (APRs) compared to standard banking products. While a person with stellar credit might settle for a 10% APR, those in the subprime category often face significantly higher numbers.

It is not necessarily a predatory trick. Rather, these elevated rates act as a direct mirror of the increased danger a bank faces when lending to someone who has struggled with past payment deadlines. Lenders aren’t just being difficult; they are simply pricing in the likelihood that they might not see their money back on time.

It is a bitter pill to swallow, but it is the reality of the market. You must look past the surface level of the deal. Many people get caught in a trap by focusing solely on what they owe each month. It is easy to feel comfortable when a loan looks manageable on a weekly or monthly basis.

For example, imagine you take out a $1,000 loan with a monthly requirement of $150. That seems like a breeze, right? However, if that obligation lasts for 12 months, you will have handed over $1,800 in total. That extra $800 is the steep fee you are essentially paying for the speed and ease of the transaction.

To avoid a massive case of sticker shock when the final bill arrives, do not fly blind. Always sit down with an APR calculator to map out the entire life of the debt. Seeing the grand total helps ensure you aren’t paying a king’s ransom just to solve a temporary cash crunch.

Navigating the Application Process Securely

Walking into a loan application can feel like stepping into a minefield if you aren’t prepared. To keep your financial situation from spiraling, you should follow a strategic roadmap during the process.

First, pinpoint your specific funding requirement with absolute precision. Taking out a $2,000 loan when a $1,200 sum would suffice is a costly slip-up that will only inflate your interest obligations over time.

It is vital to know exactly where you stand before you start knocking on doors. Use a complimentary service to review your personal credit rating. This insight helps you determine whether to pursue “no credit check” alternatives or seek more affordable, standard lending options.

Don’t let a small monthly figure trick you into a bad deal. Instead of focusing solely on the monthly payment, scrutinize the “Total Repayment Amount” to grasp the true weight the debt will place on your budget.

Timing is everything when managing your cash flow. Carefully examine your repayment schedule to ensure that installment due dates sync up with your paychecks. If your income arrives on the 1st and 15th, a deadline on the 22nd might leave you in a tight spot.

Lastly, always verify that your lender is the real deal. Before you hand over any private banking information, ensure the website is encrypted with an “https” prefix and displays the secure padlock icon in your browser.

Navigating the Keystone State’s Credit Landscape

Selecting a financial partner shouldn’t be a roll of the dice. While the allure of immediate funds is powerful, you must scrutinize the hidden clauses carefully. A quick fix for a $500 emergency might snowball into a $5,000 nightmare by next year if the contract terms remain a mystery to you.

There is a massive gulf between an installment loan and a payday loan. Think of it as the difference between a steady, manageable climb up a mountain and a terrifying, uncontrolled freefall into a canyon. Navigating these choices requires a keen eye and a bit of foresight.

Do not let the speed of the bank transfer cloud your judgment. It is vital to investigate whether a lender performs a hard or a soft credit pull. If your finances are already on shaky ground, an extra hard inquiry is the last thing your credit profile needs.

When you hammer your credit report with too many inquiries in quick succession, you might send a red flag to traditional banks. They might interpret this pattern as a sign of desperation. Consequently, your credit score could take a significant hit exactly when you need it most.

Take a moment to reflect on the actual purpose of your borrowing. If your goal involves consolidating existing debt, a structured, long-term option like those offered by Loanz is often a far more intelligent move than a high-interest payday advance. You must always match the specific tool to the job at hand.

Think of it like a carpenter choosing between a hammer and a saw. Short-term instruments are perfectly suited for filling minor gaps in your monthly budget. However, for major, structural shifts in your financial life, you really need those long-term tools to keep things stable.

The 4 Best Lenders for Manufactured Home Financing in 2026

By Uncategorized
Manufactured home financing

The 4 Best Lenders for Manufactured Home Financing in 2026

Last updated: 2026-10-17

Finding a place to call home often feels like running a marathon through a thunderstorm. For many, that dream home is a manufactured residence, but walking into a traditional bank can feel like hitting a brick wall. If you have encountered a “no” from standard lenders, you are certainly not alone in this struggle.

The complexity of the manufactured housing sector means that the financing process is rarely a straight line. It is a labyrinth of varying regulations, property classifications, and lender appetites. You have to know exactly what you are looking at before you sign anything.

Selecting the right lender depends entirely on your unique financial footprint. Some buyers need high-speed cash for quick repairs, while others require specialized programs designed specifically for mobile homes. Navigating these waters requires knowing which institutions specialize in your specific credit profile and housing type.

For instance, if you are purchasing a home on leased land, your financing needs will differ vastly from someone who owns the land beneath a manufactured home. Understanding this distinction is the first step toward successful homeownership.

  1. FastLendGo
  2. Triad Financial Services
  3. Sound Community Bank
  4. Fannie Mae

Evaluating the 2026 Manufactured Home Lending Landscape

The criteria for this evaluation focus on specialized product availability and accessibility. A lender’s ability to look beyond a simple credit score is paramount in this niche market. We looked at how these providers handle various credit tiers, from high-income professionals to those rebuilding their financial lives.

In 2026, the landscape has shifted toward more data-driven underwriting. This means that a single mistake in your digital financial footprint can impact your eligibility across multiple platforms. It is no longer just about what a human loan officer thinks of your history.

We also weighed the importance of loan structure and speed. In a fast-moving real estate market, waiting weeks for an answer can kill a deal. Therefore, we prioritized lenders that offer clear paths for different borrower needs, whether that involves traditional mortgage backing or specialized chattel financing.

We specifically looked at the distinction between “chattel loans”—which treat the home as personal property—and “real property” loans, where the home and land are bundled together. The latter often offers lower interest rates but requires much stricter documentation and a higher credit threshold.

Lender Name Loan Types Max Loan Amount Min Credit Score Key Feature
FastLendGo Personal Loans See site See site Quick access to cash
Triad Financial Services Manufactured/Mobile See site See site Specialized financing
Sound Community Bank Manufactured Home $350,000 640 FDIC-Insured
Fannie Mae Single-Family See site See site Desktop Underwriter

Understanding the Critical Distinction: Chattel vs. Real Property Loans

Before you begin your applications, you must understand the two primary ways manufactured homes are financed. This is the most frequent source of confusion for first-time buyers. If you don’t get this right, you might face significant delays in the closing process.

It is better to sort this out now rather than discovering a problem when you are ready to move in. The difference between these two loan types changes everything from your interest rate to how you pay the loan back.

What is a Chattel Loan?

A chattel loan is essentially a personal property loan. It is used when the manufactured home is considered a piece of personal property rather than real estate. This is most common when the home is located in a mobile home park where you lease the land from a park owner.

Because the home is not tied to land you own, the lender views the loan more like an auto loan or a high-end personal loan. These loans are often easier to qualify for if your credit is less than perfect. However, they typically carry higher interest rates and shorter repayment terms, such as 10 to 15 years rather than 30.

What is a Real Property Loan?

A real property loan is a traditional mortgage. This is only an option if the home is permanently affixed to land that you (or a co-borrower) own. In this scenario, the home and the land are combined into a single piece of real estate.

This is the “gold standard” for financing because it offers the lowest interest rates and the longest terms. However, the requirements are much more stringent. You will likely need a formal appraisal that accounts for both the structure and the land, and your credit score will need to meet the higher thresholds set by institutions like Sound Community Bank.

Top Ranked Lenders for Manufactured Home Financing

1. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo operates as a versatile partner for those needing quick access to cash. Instead of getting bogged down in the complexities of a mortgage, this provider focuses on personal loans that can be used for various needs. It is an ideal choice for those needing to bridge a financial gap quickly.

You might use this to cover the security deposit on a new property or to fund urgent structural repairs on a home you have just acquired. (fastlendgo.com)

This lender caters to a massive spectrum of borrowers. You might find yourself looking for a small $500 loan for an emergency or a larger $5,000 sum for a specific project. They offer tailored solutions for high-income individuals as well as those with less-than-perfect credit histories.

This flexibility makes them a valuable tool in a borrower’s “financial toolkit,” even if they aren’t your primary long-term mortgage provider.

Pros:

  • Extremely fast access to cash for emergencies.
  • Flexible loan amounts ranging from $500 to $5,000.
  • Options available for various credit tiers.

Cons:

  • Personal loan structures may differ from traditional home mortgages.

2. Triad Financial Services

Triad Financial Services – triadfs.com

If you have been told “no” by traditional banks, Triad Financial Services might be the breath of fresh air you need. They specialize in what other lenders won’t touch, specifically manufactured and mobile homes. They have been in the game for over 65 years, providing stability in a volatile market.

Their longevity is a sign of their ability to handle the specific risks associated with manufactured housing. Many other lenders retreat when they see these specific property types, but Triad stays in the fight.

This lender is a specialist in the field of chattel loans. They understand the nuances of manufactured property better than a generalist bank. They know how to evaluate the depreciation of the structure and the specific ways that manufactured homes hold value differently than site-built homes.

If your goal is to secure a home despite a complicated financial past, their experience becomes an invaluable asset during the application process.

Pros:

  • Decades of experience in specialized home financing.
  • Focuses on manufactured homes where others hesitate.
  • Designed for those facing financial hardships.

Cons:

  • Specialized lending may come with different terms than standard mortgages.

3. Sound Community Bank

Sound Community Bank – soundcb.com

Sound Community Bank offers a more traditional banking experience for those purchasing manufactured homes. They provide structured loans with a clear set of requirements. This is a solid option for a buyer who has established their credit and wants the security of an FDIC-insured institution.

Working with a bank like this provides a sense of stability. Your funds are protected under the full faith and credit of the U.S. Government, which offers peace of mind during a major life transition.

The program includes specific parameters, such as a 10% minimum down payment and a minimum FICO score of 640. With loan amounts reaching up to $350,000, they provide a significant amount of breathing room for those looking to make a substantial investment in their property.

Because this is a “real property” style approach, it is highly recommended for those who intend to stay in their home for the long term and want to build equity through traditional means.

Pros:

  • FDIC-insured with the full faith of the U.S. Government.
  • Substantial loan amounts up to $350,000.
  • Clear, predictable lending criteria.

Cons:

  • Requires a minimum credit score of 640.

4. Fannie Mae

Fannie Mae – singlefamily.fanniemae.com

Fannie Mae acts as a massive engine behind the scenes of the American housing market. While they are not a direct lender you walk into on a street corner, their technology and standards drive how many loans are actually made. They provide the framework that many professional lenders use to approve you.

When you hear a lender say they “follow Fannie Mae guidelines,” it means they are using a standardized, highly regulated process. This approach minimizes risk for both the lender and the borrower, making the whole system more predictable.

Their Desktop Underwriter system is a cornerstone of modern mortgage processing. By using advanced data and insights, they help lenders make faster, more accurate underwriting recommendations. This is the gold standard for those looking for highly regulated and standardized single-family financing options.

It reduces the “human error” element of mortgage approval. The result is a more clinical and predictable outcome for the borrower, which can take some of the anxiety out of the process.

Pros:

  • Utilizes advanced Desktop Underwriter technology.
  • Provides massive scale and stability to the market.
  • Offers streamlined pricing through modern credit models.

Cons:

  • Not a direct lender; you must work through a partner.

Preparing Your Financial Portfolio for Approval

Securing a loan for a manufactured home requires more than just a decent credit score; it requires a meticulous level of documentation. Because manufactured homes are often categorized differently than stick-built homes, lenders will be particularly eagle-eyed regarding your ability to repay and the collateral value of the home.

Start by gathering your “Big Three” documents: proof of income, tax returns, and asset statements. For manufactured home buyers, lenders often want to see at least two years of consistent employment history. This consistency proves you can handle the monthly payments over the long haul.

If you are self-employed, prepare for a much deeper dive into your cash flow. You may need to provide several months of bank statements to prove that your income is stable and not just a seasonal spike. Additionally, ensure your debt-to-income (DTI) ratio is as low as possible. Most lenders want to see that your total monthly debt obligations do not exceed 43% of your gross monthly income.

Navigating Your Path to Homeownership

The most common mistake people make is applying for the wrong type of loan for their specific property. A manufactured home is often treated differently than a site-built house. If you apply for a traditional mortgage for a mobile home, you might run into a wall of confusion and delays.

Always ask your potential lender, “Will this be a real property mortgage or a chattel loan?” before you submit a formal application. Knowing this early saves you weeks of frustration and wasted paperwork.

Another pitfall is ignoring the fine print regarding credit scores. Some lenders, like Sound Community Bank, have a specific floor for credit scores. If you fall even a few points below that mark, you might be wasting your time with that particular institution.

It is worth noting that while a score of 640 might get you through the door at one bank, a score of 680 or higher might unlock much more favorable interest rates at another. Always verify your score and the specific models lenders use before you start the paperwork.

Finally, do not wait until the last minute to check your credit. A sudden dip in your score can turn a “yes” into a “no” overnight. This can happen due to a high credit card balance, a small unpaid medical bill, or even a recent inquiry for a new line of credit.

Take the time to clean up your profile, resolve any discrepancies in your credit report, and understand exactly what you bring to the table before you start knocking on doors. A clean, organized profile is your greatest leverage in a negotiation.

Top-Rated Options for a Personal Loan With Collateral This Year

By Uncategorized
Personal loan with collateral

Top-Rated Options for a Personal Loan With Collateral This Year

Last updated: 2026-10-17

Entering a conversation regarding secured financing can feel like wandering blindly through a heavy mist. When you pledge an asset, such as a vehicle or a bank account, to guarantee your debt, you are making a heavy commitment. This strategy works wonders for those hunting for reduced interest costs or seeking approval after being turned away by big banks.

Offering collateral essentially signals to the lender that their exposure is significantly minimized. Consequently, this often results in superior loan conditions and much larger borrowing capacities than unsecured options provide. It is a calculated trade, swapping a portion of your personal belongings for much more advantageous financial terms.

Selecting the right firm means seeing through the flashy advertisements. You must balance your immediate need for liquid cash against the potential danger of forfeiting your property. A sudden mechanical breakdown in a car used as security or a sharp drop in market values can completely flip your financial projections overnight.

The following selection identifies the leading institutions currently dominating the 2026 landscape. We prioritized organizations that provide both reliability and rapid processing for a wide array of monetary requirements.

  1. JetzLoan
  2. Best Egg
  3. OneMain Financial
  4. Freedom First Credit Union
  5. Balance Credit
  6. Synchrony

Our Methodology for Selecting Lenders

Our goal was to pinpoint financing options where using assets can truly bolster an individual’s borrowing potential. Our investigators scrutinized how various banks manage diverse financial backgrounds. We looked at everyone from those with spotless payment records to individuals currently navigating a tight spot.

Money in your pocket is vital, but it isn’t the only thing that counts when life throws a curveball. The velocity of the payout is equally critical. If a company leaves you hanging for weeks while shuffling paperwork, they aren’t much help when an urgent payment deadline looms.

We prioritized how quickly funds arrive, the peak borrowing ceilings, and the simplicity of the signup process. It is like comparing apples to oranges, but these metrics gave us a clear picture. We also investigated whether an initial check would leave a mark on your file.

Having the ability to browse potential interest rates without hurting your rating is a huge win. We hunted for providers that utilize “soft pulls” to generate your preliminary offers. This way, you can window shop for better deals without cluttering your report with numerous inquiries.

Provider Upper Limit Payout Timing Inquiry Effect
JetzLoan $35,000 24 hours or less No hard pull required
Best Egg $50,000 Check their website Check their website
OneMain Financial $30,000 Within 1 hour No score damage
Freedom First Credit Union Check their website Check their website Check their website
Balance Credit $4,000 Following business day No impact on score
Synchrony Check their website Check their website Check their website

Top-Tier Lenders for Collateral-Based Loans

1. JetzLoan

JetzLoan – jetzloan.com

Think of JetzLoan as a rapid transit system for your finances. If you find yourself in a tight spot and need liquidity fast, they act as a bridge to premier lenders in mere moments. It is a lifeline for those facing sudden financial hurdles.

When a medical emergency strikes or a pipe bursts in your kitchen, you shouldn’t have to wait for a miracle. Their ability to get money into your hands within 24 hours is truly impressive. (jetzloan.com)

Are you terrified of the dreaded “credit score dance”? This lender lets you shop around without the sting of a hard credit inquiry. You can scout different rates while keeping your credit profile perfectly intact.

This peace of mind is gold if you are currently shopping for a mortgage or a new car. You simply cannot afford any sudden drops in your score right now. Their digital-first, transparent method makes the whole process feel seamless.

Pros:

  • Cash can arrive in as little as 24 hours.
  • Initial rate checks won’t hurt your credit score.
  • Maximum borrowing capacity reaches $35,000.

Cons:

  • They function as a matchmaker rather than the direct lender.

2. Best Egg

Best Egg – bestegg.com

In the crowded world of personal lending, Best Egg is a certified heavyweight. They don’t play games; they provide a straightforward, no-nonsense approach to borrowing. Their main mission is helping folks tidy up their financial lives.

If you are drowning in various high-interest credit card balances, a single Best Egg loan can act as a life raft. By merging those debts into one monthly payment, you can often see your APR drop significantly.

They have a rather clever trick up their sleeve: using household fixtures as security. Imagine using your cabinets or vanities to back a loan. This unconventional path is a game-changer for homeowners needing a boost.

It is a unique niche within secured lending. By treating home improvements as tangible assets, they offer a way to tap into equity without the massive headache of a formal home equity loan.

Pros:

  • High loan ceilings up to $50,000.
  • Possible to save 20% on APR.
  • Special discounts for homeowners.

Cons:

  • Specific eligibility requirements for certain rates and terms.

3. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial offers the best of both worlds: digital speed and old-fashioned human connection. With a massive network of over 1,300 branches, they aren’t just a ghost in a machine. They offer a tangible presence that many online lenders simply lack.

If you ever find yourself trapped in a digital loop or struggling with a confusing upload, you can just walk through their door. Meeting a real person face-to-face provides a sense of security that purely fintech apps can’t replicate.

For those whose credit history isn’t quite perfect, they are a bright spot. You can gauge your potential options in a mere five minutes without any impact on your score.

Life happens fast, like a car repair that threatens your ability to commute. In those critical “make or break” moments, they can deposit funds just one hour after you sign the paperwork. That kind of speed is vital.

Pros:

  • Lightning-fast funding, often 1 hour after signing.
  • Large branch network for personal, in-person assistance.
  • Flexible repayment timelines from 24 to 60 months.

Cons:

  • Total loan amount is capped at $30,000.

4. Freedom First Credit Union

Freedom First Credit Union – freedomfirst.com

Freedom First Credit Union is built on a foundation of community spirit. Unlike the cold, distant big-box banks, they operate with a local mindset. They provide secured loans that allow you to use your share accounts or certificates as collateral.

It is a rock-solid way to expand your credit while accessing the cash you need. Since you are essentially borrowing against your own savings, the interest rates tend to stay much lower. The risk to the institution is minimal, making approval much easier.

They also throw in some lovely perks, such as the ability to access your paychecks up to two days early via direct deposit. This extra bit of flexibility can make managing your monthly cash flow much smoother.

If you believe in giving back, their “Play for Purpose” initiatives show they care about local causes. It creates a beautiful cycle of mutual benefit between the credit union and the people it serves.

Pros:

  • Service model rooted in the community.
  • Can utilize share accounts as collateral.
  • Get paid up to 2 days early via direct deposit.

Cons:

  • Membership likely requires meeting specific local criteria.

5. Balance Credit

Balance Credit – balancecredit.com

Balance Credit is a specialist for those who need a quick shot of cash without a massive debt load. They focus on smaller, more manageable loans that cap at $4,000. In a sea of financial giants, they serve a specific niche.

Inclusivity is their bread and butter. They are willing to look at applications from people with less-than-ideal credit histories. This makes them a lifesaver when you need short-term liquidity but don’t need a mountain of debt.

The speed here is nothing short of impressive. Your funds can arrive in your bank account by the very next business day. Plus, they don’t believe in punishing you for being responsible and paying the loan off early.

This can save you a mountain of interest over the long haul. If a bonus or a tax refund rolls in, you can wipe that debt out instantly without facing any “prepayment penalties” from the bank.

Pros:

  • No extra costs for early loan repayment.
  • Welcomes applicants with various credit backgrounds.
  • The application process is incredibly rapid.

Cons:

  • Maximum borrowing is limited to $4,000.

6. Synchrony

Synchrony – synchrony.com

Synchrony tends to live within the marketplace and specialized financing models. They often work hand-in-hand with specific retail brands, making them more of a targeted tool than a general-purpose loan provider.

If you are looking to upgrade your lifestyle through specific retail purchases, they are your best friend. For instance, when buying high-end appliances, you might find 0% interest promotions that make big purchases much easier to stomach.

Their toolkit includes everything from credit cards to various marketplace financing options. While they might not be your first call for a utility bill, their specialized options are top-tier for large, specific retail needs.

They have mastered the art of the seamless checkout experience. The transition from browsing a store to securing financing is nearly instantaneous, making the whole shopping journey incredibly smooth for the consumer.

Pros:

  • Excellent financing tailored to retail partners.
  • A diverse array of credit-related products.
  • Integrated into a massive, established financial system.

Cons:

  • Less effective for general, non-retail personal loans.

Navigating Asset Classes and Financial Hazards

Before you sign on the dotted line for a secured loan, you need to grasp the weight of your pledge. Typically, the things you put up as security fall into three distinct buckets: cash-like assets, tangible possessions, or investment vehicles. Every single one carries a different set of potential pitfalls.

Cash equivalents, such as certificates of deposit or standard savings, are a lender’s dream because they are easy to access. For the borrower, these often represent the most economical path. For instance, pledging $5,000 from your savings usually results in incredibly favorable, low interest rates.

The catch is that this capital becomes essentially untouchable. You won’t be able to dip into that $5,000 for emergencies or unexpected bills as long as the debt remains outstanding. This can leave your wallet feeling surprisingly light during a sudden financial crunch.

Tangible items, particularly your car, are frequently used to back these loans. While a vehicle can help you qualify for much larger sums of money, it introduces the headache of “depreciation risk.” Your car’s market value is in a constant state of decline.

Imagine borrowing $15,000 against a vehicle that, because of its high mileage, is only worth $12,000. You are now “underwater,” meaning your debt outweighs the asset’s value. This puts you in a tight spot if you ever need to sell the car or miss a payment.

Investing in stocks or bonds allows for substantial borrowing power, but these come with a wild ride. The market is notoriously fickle, and sudden shifts can trigger a “margin call” from your bank. This is a high-stakes game that demands a deep understanding of finance.

Should the market crater, your lender might demand an immediate cash infusion to cover the gap. If you can’t cough up the funds, they have the right to liquidate your portfolio at a loss. Managing these types of assets requires a steady hand and sharp expertise.

Navigating the Loan Approval Path

Getting approved for financing isn’t a game of luck; it is more like following a map through a dense forest. If you rush without a plan, you might find yourself lost in a thicket of high fees and unexpected costs. You must tread carefully to protect your fiscal well-being while hunting for the most favorable terms.

Think of this process as a series of checkpoints. By hitting each one in order, you ensure that you aren’t blindsided by fine print later on. Use this roadmap to navigate your way from initial planning to final signature with confidence and clarity.

  • Stage 1: Inventory Your Collateral. Start by conducting a thorough audit of anything you might pledge to secure the funds. It is a common mistake to look at what you originally paid for an item, but you must focus on its current market worth instead.

  • For instance, if you are using a car, consult Kelly Blue Book to find its actual present-day value. If you are leveraging home fixtures, estimate what it would cost to replace them today. Make sure you have all your relevant bank statements and ownership titles sitting on the desk ready to go.

  • Stage 2: Verify Your Credit Standing via Soft Inquiry. Before you dive in, you need to know where you stand in the eyes of creditors. Utilize the “no credit impact” tools offered by companies like OneMain Financial or JetzLoan to get a quick snapshot of your score without hurting your rating.

  • This baseline is your compass. It determines whether you will be welcomed with “prime” interest rates or if you will be forced to settle for much costlier “subprime” lending products. Knowing this number early saves you from a lot of heartache during the actual application phase.

  • Stage 3: Prioritize the APR Over the Interest Rate. Don’t let a low interest rate dazzle you into a bad decision. While the interest rate tells you the cost of the principal, the Annual Percentage Rate (APR) tells the whole story by folding in all the extra fees and points.

  • Consider this scenario: a 5% interest rate coupled with $500 in various fees might actually end up costing you more than a 6% rate that has no extra charges. To make a fair, apples-to-apples comparison between different lenders, the APR is the only number that truly matters.

  • Stage 4: Weigh Your Repayment Duration. You must decide how long you want to be in debt. Choosing a longer window, such as a 60 months term, will keep your monthly obligations low and give your cash flow some breathing room. However, there is a catch.

  • The downside is that a longer timeline means you will be paying a much higher amount of total interest over the life of the debt. Always run the numbers to find the “total cost of the loan” to understand the true price tag you are signing up for.

  • Stage 5: Scrutinize the Default Clauses. Never skip the fine print regarding what happens if you hit a rough patch. You need to find the specific “remedies upon default” section to understand exactly how many missed payments would trigger a formal default status.

  • Furthermore, investigate the specific notice requirements. How much warning must the lender provide before they are allowed to seize your assets? Identifying this “grace period” is absolutely vital for protecting your property and your peace of mind during difficult times.

Avoiding Common Pitfalls in Secured Lending

The biggest mistake is underestimating the weight of collateral. When you put your car or savings on the line, you are telling the lender, “If I fail, you take this.” It is a high-stakes game.

You need a clear-eyed view of your budget. A common psychological trap is thinking, “I can always pay it back later.” The legal reality of a secured loan is rarely that flexible.

Always read the fine print regarding defaults. Some lenders are much more aggressive than others. Some might repossess a vehicle after a single missed payment. Others might offer a structured workout plan.

Keep a close eye on the total cost of borrowing. A lower interest rate might look enticing, but high fees can change everything. Watch out for “origination fees” taken from your loan amount upfront. You might receive $9,500 even though you signed for $10,000.

Finally, do not rush the process just because you are in a pinch. Speed is important, but taking an extra hour to compare terms can save you thousands. Use “no credit impact” checks to do your homework without consequence.

Top-Rated Bad Credit Loans Illinois: Compare Fast Cash Options Now

By Uncategorized
Bad credit loans illinois

Top-Rated Bad Credit Loans Illinois: Compare Fast Cash Options Now

Last updated: 2026-10-16

Navigating a sudden money shortage while battling a low credit score often feels like hitting a dead end. Throughout Illinois, these financial hurdles frequently demand immediate attention. Life doesn’t wait for your credit report to improve before throwing a curveball.

A sudden trip to the ER or a smoking engine under the hood can create an instant crisis. Whether you are navigating the bustling Chicago skyline or living in the peaceful Cook County suburbs, these hiccups strike hard. Downstate residents face the same sudden pressure to find quick cash.

Mainstream lenders are rarely your best friends when life gets messy. If your history is littered with late payments or heavy debt loads, most big banks will likely shut their doors. This creates a massive gap in the safety net for many hardworking people.

When you are searching for a way to cover an unexpected expense, you need more than a simple “yes.” You must find a provider that evaluates the whole person rather than just a single digits score. It is about finding a partner, not just a transaction.

Don’t get blinded by a quick approval when selecting a company. You should investigate exactly how fast the funds arrive in your personal account. Speed is vital when your bills are piling up on the kitchen table.

Also, keep a sharp eye on the total price of your borrowing. A small monthly installment might seem like a dream, but extended timelines can make you pay twice what you took out. This guide highlights the most dependable Illinois options for those seeking a helping hand.

  1. IllinoisLoansToday
  2. Tower Loan
  3. OppLoans
  4. SAIL Loans
  5. AmeriCash Loans
  6. Reprise
  7. OneMain Financial

Comparing Borrowing Choices Across Illinois

Our research prioritized two major pillars: ease of access and honest communication. We specifically hunted for lenders that permit a soft credit inquiry during the initial sign-up phase. A hard pull can act like a heavy weight on your score, which is the last thing you need while you’re digging yourself out of a financial pit.

Identifying services that won’t cause “no impact” to your standing is absolutely essential for long-term stability. Every little digit on that three-digit number carries weight in your wallet. Applying for a loan you ultimately reject might actually hamper your chances of securing an auto loan or a mortgage down the line.

It’s a minor nuance that often leads to massive migraines if you aren’t mindful of where you cast your net. We also scrutinized the speed of fund distribution and the variety of available loan limits. Some companies specialize in tiny, rapid cash infusions to bridge a gap in your monthly budget.

Meanwhile, other providers target much larger milestones, such as fixing up a kitchen or settling high-interest debt. Our mission was to pinpoint services providing maximum versatility for residents throughout the Land of Lincoln. Whether you require $500 for a grocery run or $15,000 for a roof repair, a route exists.

We wanted to distinguish which providers cater to those facing genuine, everyday hardships. This side-by-side look eliminates the guesswork, helping you identify which lender aligns with your unique circumstances. Using these metrics ensures you make an informed decision rather than a desperate one.

Provider Available Funding Credit Criteria Time to Funds
IllinoisLoansToday $500 – $50,000 No credit score impact Minutes
Tower Loan See site Established credit required See site
OppLoans $500 – $5,000 Does not affect FICO score Same-day funding
SAIL Loans Up to $4,000 Builds credit history Quick approval
AmeriCash Loans See site No credit check Same day
Reprise See site See site See site
OneMain Financial $1,500 – $30,000 See site As soon as 1 hour

Premier Lending Options for Illinois Residents

1. IllinoisLoansToday

IllinoisLoansToday – illinoisloanstoday.com

Think of this service as a high-speed digital matchmaker for borrowers throughout the state. Rather than wasting hours hitting up dozens of different banks, this platform connects you directly with licensed providers that cater to diverse financial histories. It is a massive time-saver when you are racing against the clock. It’s a bit like a mechanic spotting a critical engine flaw that requires immediate attention to get you on the road by Monday morning. illinoisloanstoday.com

If you are staring down a mountain of sudden costs, such as an emergency furnace fix or a hospital bill, this platform is a lifesaver. Because it links you to a wide array of institutions, you aren’t tethered to the specific rules of a single firm. You get to survey the entire landscape of available options. Fortunately, checking your rates here won’t dent your credit score, allowing you to window-shop for deals without any anxiety.

Pros:

  • Funding amounts ranging from $500 to $50,000
  • Rate inquiries will not impact your credit standing
  • Covers various needs including moving costs or debt consolidation

Cons:

  • Results depend on the current inventory of third-party lenders

2. Tower Loan

Tower Loan – towerloan.com

A household name in the lending space, Tower Loan provides several variations of personal and installment loans. Whether you are dreaming of a long-awaited vacation, planning home renovations, or seeking a loan secured by your vehicle, they have a path forward. Opting for an auto-secured loan can often lower your interest rates. This occurs because the car serves as collateral, which offers the lender a safety net for the borrowed capital.

You should keep in mind that they look for a proven track record of managing credit to grant approval. Consequently, they are a great choice for someone with a shaky credit score who still maintains a consistent history of making payments. If life threw you a curveball and caused a single late payment, but your income remains steady, Tower Loan might be a solid bridge to get you through.

Pros:

  • Various loan structures including auto-collateralized options
  • Numerous physical locations throughout Illinois
  • A highly established brand with deep roots in the industry

Cons:

  • An established credit history is necessary to qualify

3. OppLoans

OppLoans – opploans.com

OppLoans operates on a philosophy that looks far beyond the surface-level numbers of a traditional credit report. By partnering with various banking institutions, they offer a lifeline to individuals who might get the cold shoulder from bigger banks. Instead of relying solely on a FICO number, they employ an intelligent algorithm to weigh your income stability and your overall capacity to repay the debt.

The application process is incredibly streamlined and efficient. You can often see a decision in just a few short minutes. When you are caught in a financial pinch, receiving funds within the same business day can be a total game-changer. This rapid turnaround helps you stay ahead of rent increases or utility late fees, which ultimately prevents even deeper layers of financial stress from piling up.

Pros:

  • Users who are approved can access same-day funding
  • The application process has zero impact on your FICO score
  • Transparent terms with no hidden fees during the process

Cons:

  • Maximum loan amounts are limited to $5,000

4. SAIL Loans

SAIL Loans – sailloans.com

SAIL Loans takes a refreshingly unique approach by prioritizing the growth of your credit profile. Their installment-based loans are engineered to provide immediate cash while simultaneously working to polish your financial reputation for the future. It is essentially a dual-purpose tool for those living on a tight monthly budget. It works to bridge that difficult gap between high-interest debt cycles and long-term fiscal health.

They provide rapid approvals for those who require up to $4,000 to handle their immediate needs. By leveraging their specific tools, borrowers can tackle pressing expenses while actively improving their financial wellness. This is an excellent option if you just need a little extra cushion to navigate through the end of the month while making your future major purchases much easier to finance.

Pros:

  • Supports the building of credit history and savings
  • Provides a fast and secure digital application experience
  • Installment loans are available for up to $4,000

Cons:

  • The specific focus on credit repair may not be ideal for those seeking massive lump sums

5. AmeriCash Loans

AmeriCash Loans – americash.com

When you need cash fast, AmeriCash Loans serves as a rapid-response option for your short-term requirements. They live by the mantra of “money today, momentum tomorrow.” Using a marketplace model, they allow you to broadcast your information to various lenders to see which ones are willing to extend credit. This approach maximizes your odds of finding a provider that aligns perfectly with your specific credit profile.

Speed is baked into every part of their process, allowing for often-instant approval decisions. Because they offer installment loans that do not always demand a rigid credit check, they are a frequent destination for people facing high-pressure financial moments. You won’t find yourself stuck waiting for a bank’s three-to-five-day deliberation when you have a cash emergency that needs solving right now.

Pros:

  • Swift application process paired with instant decisions
  • Many loan options do not require a formal credit check
  • Access to cash on the same day

Cons:

  • The marketplace structure means you will be redirected to different lenders

6. Reprise

Reprise – reprise.com

Reprise is a specialized platform that carves out its niche in high-level demo creation and artificial intelligence tools. While it is a highly sophisticated piece of technology, it appears on this list because its precision is unmatched. It represents the cutting edge of SaaS evolution, helping modern businesses communicate their most complex technical concepts to potential clients with clarity.

Their suite of tools allows users to construct high-fidelity product tours and demos injected with real-time data. This is a completely different beast than the world of personal lending. This platform caters to the professional enterprise sector rather than the average individual consumer. For a tech-forward professional, this is an investment in productivity rather than a way to manage personal household debt.

Pros:

  • Advanced AI-powered toolset for professional demo creation
  • Excellent at handling complex and heavy data payloads
  • Facilitates the seamless sharing of high-quality product tours

Cons:

  • This is not a provider for personal loans or individual debt management

7. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial stands as a heavy hitter in the personal lending industry. They are equipped to handle substantial sums for people facing major financial hurdles. You can access funding ranging from $1,500 all the way up to $30,000. This makes them a top choice for heavy-duty expenses like debt consolidation, medical bills, or significant vehicle repairs that require a large upfront sum.

They provide a perfect blend of digital convenience and the comfort of human interaction. With a massive network of over 1,300 branches across the country, their physical presence is a major asset. If you would rather sit down with a real person to discuss your budget or work out a specific repayment plan, you can walk into an office and get that personal help.

Pros:

  • Significant loan capacities reaching up to $30,000
  • Fixed monthly payments that make budgeting much simpler
  • Physical branch access for those who want face-to-face support

Cons:

  • The approval criteria are more stringent than those of payday lenders

Evaluating Your Actual Debt Obligations

In the heat of a financial storm, the immediate craving for liquidity often acts like a fog, obscuring your ability to think clearly. It is easy to lose sight of the big picture when you just need money now. Consequently, you must learn to distinguish between a basic interest rate and the Annual Percentage Rate (APR).

Think of the APR as the honest truth-teller of the lending world. While interest rates only tell part of the story, the APR provides a comprehensive overview of your total liability. It combines the interest percentage with every mandatory charge, such as processing or origination fees, into one single figure.

Consider a scenario where a lender quotes a 15% interest rate. Once those pesky administrative costs are factored in, that loan might actually carry an APR of 19%. Always keep your eyes glued to that APR value. It serves as the genuine price tag for every dollar you pull from a lender’s pocket.

The duration of your repayment schedule is another heavyweight contender in the cost equation. Suppose you borrow $1,000; paying that back over three months results in much less total interest than stretching the debt over twelve months. The math doesn’t lie, even when the numbers seem small.

While a longer term makes monthly installments feel like a walk in the park, the cumulative interest will eventually hit you like a ton of bricks. It is vital to simulate a “what-if” scenario. Ask yourself: “Could my budget survive if my paycheck takes a sudden dip next month?”

If that question makes you sweat, you are likely biting off more than you can chew. You might find better success by requesting a smaller sum or seeking more adaptable repayment terms. Preparing for a rainy day is the best way to prevent a complete financial shipwreck down the road.

Navigating Your Way Out of Financial Crises

When life throws a curveball and you find yourself needing an immediate loan, remember that the goal is to find stability. This money should be a lifeline to steady your ship, rather than an anchor pulling you down. Using these funds wisely is the difference between getting ahead and falling into a hole.

First, tackle those expensive debts that are eating your budget alive. If your plan involves debt consolidation, verify that the new interest rate is much lower than your current ones. Beware the temptation to use a new loan to clear a credit card, only to start spending on that card again. If you fall into that trap, you’ll find yourself facing double the trouble.

Another smart move is to let technology handle your bills through automated payments. Missing a deadline can lead to heavy penalties that sting when your finances are already stretched thin. It is often worth the effort because many lenders actually reward you with a slight discount for setting up auto-pay.

If your sudden expense stems from a hospital visit, don’t assume the bill is set in stone. Reach out to the billing office of your Illinois medical provider to discuss your situation. Many of these facilities provide interest-free payment structures or even direct discounts for patients undergoing genuine financial hardship.

Once the storm has passed, start building a modest safety net for the future. Even tucking away a mere $25 every month can eventually cover a quick fix for a broken car. Creating this little buffer ensures you won’t have to hunt for high-interest loans the next time an unexpected bill arrives.

Walking through the loan application process requires a careful dance between speed and prudence. While the rush of an instant approval feels great, you must scrutinize the fine print before signing your name. The real cost of your borrowing is found in the total repayment amount and the APR, not just the speed of the cash.

Don’t fall for the siren song of easy credit. Using a loan to settle another debt only works if the new interest rate is genuinely lower. If you are simply borrowing more to pay more, you are entering a downward spiral. Treat credit like a precise surgical tool for stability rather than a temporary bandage for a deep wound.

A frequent error many people make is failing to shop around for the best terms. A rejection from one lender does not mean you are out of luck everywhere. Utilize the “no impact” inquiry features provided by many modern lenders to compare rates without hurting your score. This extra effort can save you thousands of dollars over the lifetime of your debt.

Find Fast Bad Credit Loans Georgia Residents Can Secure Online Today

By Uncategorized
Bad credit loans georgia

Find Fast Bad Credit Loans Georgia Residents Can Secure Online Today

Last updated: 2026-10-16

Navigating the financial landscape in Georgia becomes a real headache when your credit score is trailing behind. It feels like trying to find your way through a heavy mist without a compass or a map.

Suddenly, an unplanned trip to the mechanic or an emergency doctor visit can throw your entire budget into chaos. You find yourself scrambling for a way to bridge the gap between your paycheck and your expenses.

Sadly, the big-name banks often turn up their noses when they glance at a damaged credit profile. They tend to slam the door on anyone who doesn’t have a pristine financial track record to show for it.

This constant struggle can quickly become a downward spiral. If you don’t approach this search with a clear strategy, you might stumble right into a predatory debt pitfall while chasing a quick fix.

You really have to watch your step when the money starts getting tight. It is vital to vet your options thoroughly before signing anything that promises an immediate windfall of cash.

Locating a trustworthy source of funding requires more than just trusting a flashy “guaranteed” sticker on a storefront. You have to dig into the details of the agreement to see how the repayment works.

It is also crucial to verify that any lender you choose operates strictly within the legal frameworks set by Georgia. Skipping this step could cost you much more than just interest rates in the long run.

The following breakdown evaluates the most sensible avenues for Georgians who are currently facing a cash crunch. These selections are tailored for those who may be working with less-than-ideal credit standing.

  1. SkyOne
  2. Wells Fargo
  3. FastLendGo
  4. Coastline Credit Union
  5. United Bank
  6. GreendayOnline
  7. Max Cash

Our Methodology for Assessing Georgia Financing Providers

When we sat down to sort through these Georgia lenders, we kept a close eye on their attitude toward borrowers with imperfect credit histories. It is easy to get lost in the fine print, but we prioritized the actual usability of the application process. We also scrutinized the total liquidity available to someone facing an urgent financial crisis.

Throwing money at a problem is a double-edged sword if the interest rates are a mountain too steep to climb. We believe that providing capital is only half the battle; the real test is whether the repayment schedule is actually manageable for a real person. We refused to recommend predatory setups that leave borrowers in a deeper hole.

Another major factor in our research involved balancing the need for haste against long-term stability. It is a classic dilemma: do you want an answer right now or a sustainable path forward? Some providers offer lightning-fast decisions but demand a much higher price for that convenience. It’s a trade-off that every borrower must weigh carefully.

On the other hand, a slower approval process might lead to much more predictable and stable terms. You essentially have to choose between a temporary band-aid for a sudden emergency and a strategic tool designed to help reconstruct your financial reputation over the long haul. We looked at both ends of this spectrum to give you a clear picture.

Provider Borrowing Limits Qualification Criteria Transfer Speed Primary Advantage
SkyOne $500 – $50,000 Credit Building Focus see site Non-Variable Rates
Wells Fargo $3,000 – $100,000 No impact to score see site Emergency Loans
FastLendGo $500 – $5,000 Bad Credit Options see site Various Loan Types
Coastline Credit Union Up to $2,500 Limited/No History see site Starter Loans
United Bank $200 – $500 No Credit Check see site 90-Day Terms
GreendayOnline $100 – $5,000 Bad Credit Welcome Same Day Quick Approvals
Max Cash $250 – $10,000+ Bad Credit Loans Minutes Title Loan Options

Top-Rated Lending Solutions for Georgia Borrowers

1. SkyOne

SkyOne – skyone.org

If you view debt as a stepping stone rather than a heavy anchor, SkyOne might be your best ally. Their personal loan products are crafted to boost your credit standing while providing the liquid capital you currently require. It is a clever strategy for repairing your fiscal reputation through disciplined, intentional borrowing.

In a market characterized by constant volatility, their non-variable interest rates offer a breath of fresh air. Finding such stability is like finding a needle in a haystack within the high-interest lending landscape. For those seeking to tackle larger obligations, such as $50,000, this remains a highly reliable path to explore.

Many people find that using structured borrowing can act as a bridge to financial stability. Rather than just patching a hole, you are actively building a foundation for the future. It is about playing the long game with your money.

Pros:
  • Fixed interest rates provide much-needed stability.
  • Designed to strengthen your credit profile through personal loans.
  • Can provide substantial capital up to $50,000.
Cons:
  • Demands a highly disciplined approach to repayment.

2. Wells Fargo

Wells Fargo – wellsfargo.com

When a sudden crisis strikes and you need a massive injection of capital, Wells Fargo is prepared to step up. Their emergency lending options can reach as high as $100,000, making them ideal for significant, unexpected life upheavals. This isn’t exactly a service for someone needing pocket change for a quick grocery run.

This is truly for individuals facing a genuine financial catastrophe that requires substantial funding. One significant advantage is that performing a preliminary check on your eligibility won’t ding your credit score. You can survey your options without the fear of making your situation any worse.

It acts as a high-ceiling safety net for anyone trying to sail through a sudden economic storm. When the waves get rough, having a large reserve can make all the difference between sinking and staying afloat. It is a heavyweight contender for serious needs.

Pros:
  • Extensive borrowing limits reaching $100,000.
  • Inquiry process does not impact your credit score.
  • Tailored specifically for urgent emergency situations.
Cons:
  • Strict requirements for standard loan approval.

3. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo serves as a versatile “Swiss Army knife” for those caught in a sudden financial pinch. They provide a wide array of solutions, ranging from $500 personal loans to dedicated funds for fixing a car or a tooth. You can find various specific solutions at fastlendgo.com.

Their digital platform is engineered for maximum velocity. Whether you possess a stellar credit history or are currently struggling with bad credit, they provide multiple avenues to secure cash. It is a fantastic option if you want to weigh different paths quickly without endless clicking.

The interface allows you to pivot between different needs with ease. Instead of getting lost in a labyrinth of different banking websites, you find everything in one place. It is a streamlined approach to modern borrowing needs.

Pros:
  • Targeted funds for auto, roofing, or dental needs.
  • Accommodates a broad spectrum of credit scores.
  • Intuitive online tools for comparing different options.
Cons:
  • Interest rates and terms fluctuate based on credit.

4. Coastline Credit Union

Coastline Credit Union – coastlinecu.com

National banks can often feel like cold, faceless machines, but credit unions like Coastline tend to feel much more human. Their starter loans act as a vital lifeline for individuals with little to no established credit history. These are modest, manageable amounts intended to help you enter the financial system.

By providing loans in amounts up to $2,500, they focus heavily on the foundational elements of credit building. It is a gentle, low-stakes way to demonstrate that you are a reliable borrower. For a Georgian just beginning their economic journey, this can be a meaningful first step.

Think of it as a training wheels phase for your finances. Once you prove you can handle these smaller amounts, the door to larger credit becomes much easier to open. It is about building trust with your lenders through small, successful steps.

Pros:
  • Ideal for those starting with zero credit history.
  • Easier entry requirements for financial beginners.
  • Employs a member-centric service philosophy.
Cons:
  • Borrowing caps are relatively low for new users.

5. United Bank

United Bank – accessunited.com

United Bank offers a highly specialized product known as the Cash Please Loan. This is a quick, 90-day solution designed for people who need a small sum—between $200 and $500—without the usual hassle of a credit check. It is a rapid remedy for minor, immediate needs.

This option is perfect if you are just a few weeks away from your next paycheck but find yourself short on cash for an urgent bill. It is a precision tool meant to bridge a very specific type of financial gap. It helps pull you out of a temporary bind.

Because the timeframe is so short, it is not meant for long-term debt. It is a surgical strike on a small financial problem. Using it effectively requires a clear plan to pay it back within that three-month window.

Pros:
  • No credit check is necessary for Cash Please Loans.
  • Provides incredibly fast access to small amounts of cash.
  • Operates on a short 90-day timeline.
Cons:
  • Strictly limited to small amounts ($200-$500).

6. GreendayOnline

GreendayOnline – greendayonline.com

When the clock is ticking and time is your biggest enemy, GreendayOnline enters the ring. They specialize in rapid funding for borrowers with bad credit, sometimes even providing same-day payouts. Their entire business model is built for speed, allowing applications in mere minutes with near-instant decisions.

With amounts ranging from $100 to $5,000, they cover the vast majority of minor emergencies. It is a digital-first experience designed for the modern, fast-paced borrower. You won’t have to wait days for a bank manager to eventually glance at your file.

This is for the person who needs an answer right now, not next week. It is a high-speed option for high-speed problems. Just keep in mind that the faster the money arrives, the more careful you must be with the terms.

Pros:
  • Potential for same-day fund availability.
  • Extremely rapid online application process.
  • Welcomes applicants with bad credit.
Cons:
  • Rapid funding often carries higher interest rates.

7. Max Cash

Max Cash – maxcash.com

Max Cash functions as a comprehensive hub for high-velocity financial products, including installment and title loans. Their offerings are broad, starting from $250 and climbing to $10,000 or even higher. It is a highly versatile resource for anyone requiring immediate liquidity.

The entire platform is built for speed, often delivering results in just a few minutes. They provide several different ways to access cash, including options that may involve using your vehicle title as collateral. This can be a vital resource when traditional paths are blocked.

It is a heavy-duty option for those facing urgent financial pressures. While it provides the liquidity you need, the weight of the obligation is significant. It is a powerful tool that requires a steady hand to manage correctly.

Pros:
  • Diverse array of products including title loans.
  • Extremely quick decision-making capabilities.
  • Wide spectrum of available loan amounts.
Cons:
  • Title loans involve a substantial risk of losing your asset.

Picking the Perfect Match for Your Needs

Finding the ideal lender is rarely a straightforward path, as no two financial journeys are identical. It is much like picking a pair of boots; what works for a hiker might fail a marathon runner. You must carefully weigh your personal objectives against the specific terms offered by different institutions.

If your primary aim involves long-term stability and credit growth, exploring options like SkyOne or Coastline Credit Union could be wise. These entities often focus on helping members cultivate their financial health over several years. They act like a slow-burning candle, providing steady guidance for the long haul.

On the other hand, life sometimes throws a curveball that requires immediate, heavy-duty intervention. Should an unexpected medical crisis demand urgent cash, the substantial borrowing ceilings at Wells Fargo might be your best bet. When the house is on fire, you need a high-pressure hose, not a garden sprinkler.

Never let the excitement of a sudden approval cloud your judgment or make you act impulsively. It is easy to get swept up in the moment, but jumping at the first email you receive is a gamble. You must approach these offers with the eyes of a hawk, scanning for any hidden traps.

Scrutinize every fine print detail regarding variable interest rates or unexpected service charges. A deal that feels like a bargain right now can quickly turn into a financial quagmire if rates skyrocket. If the repayment timeline moves faster than your paycheck, that “cheap” loan might just become a heavy anchor.

Best Ways to Secure Lawn Mower Financing for Your Yard Upgrade

By Uncategorized
Lawn mower financing

Best Ways to Secure Lawn Mower Financing for Your Yard Upgrade

Last updated: 2026-10-16

Picking out a fresh lawn mower can feel like trying to scale a massive peak. Once a top-tier zero-turn model reaches a price tag in the thousands, it is rare that a buyer simply walks into a showroom and drops a heavy stack of bills. Usually, folks need a way to break those costs into manageable installments over a few months or even years.

The way you pay for your equipment is just as vital as the hardware you are choosing. Whether you are swapping out a beat-up push mower for a premium riding tractor or growing a professional landscaping business, you are balancing a large capital expense. You are essentially managing a major investment in steel and cutting edges.

Don’t get caught up thinking only about your monthly bill. Securing a solid lender requires looking at the fine print, like how interest rates play against your credit score. You also want to keep an eye on the clock to see how fast that mower actually arrives at your door.

A loan with high interest might look easy on your wallet right now. Yet, if that debt is dragged out over a 60-month term, the full price of that machine will soar. We have analyzed the most dependable ways to get behind the wheel, ranging from factory-direct incentives to rapid online lending options.

  1. Cub Cadet
  2. JetzLoan
  3. Gravely
  4. K and G Mowers
  5. Manhattan Bank
  6. Minute Loan Center
  7. Yanmar

Our Methodology for Rating Lenders

Our team didn’t just pull names out of a hat. We focused heavily on how easy it is for different people to actually get the money they need. It is a bit like tailoring a suit; a one-size-fits-all approach rarely works when everyone’s situation is unique.

For the average homeowner, landing a manufacturer-specific promotion is like finding a twenty-dollar bill in an old jacket. These deals can be a lifesaver. If you keep up with your scheduled installments, you might find yourself enjoying a zero-interest window on your new equipment.

On the other hand, professionals running landscaping businesses face a much harsher reality. When a piece of heavy machinery goes belly-up during the height of spring, time is quite literally money. Waiting several days for a bank to wake up is simply not an option.

A delay in funding means crews are standing around with nothing to do. They need liquidity by sunrise to keep the wheels turning. We recognize that for these business owners, a slow approval process is effectively a direct hit to their weekly revenue.

We put every company through a rigorous stress test. Our criteria centered on three main pillars: how quickly the cash arrives, how much flexibility the lender shows regarding credit history, and how clear they are about the fine print of their terms.

We looked closely at whether a lender would ding your credit score with a hard pull. We also checked if they are willing to shake hands with someone who has a less-than-pristine financial history. This ensures our list serves everyone from the hobbyist to the heavy-duty fleet manager.

Finally, we didn’t just look at the headline interest rate. We dug into the “total cost of credit” to see what was hiding under the rug. This means checking for sneaky origination fees, extra paperwork costs, or penalties if you try to pay the debt off early.

Nobody likes being handcuffed to a loan when they suddenly come into a windfall. We want you to have the freedom to settle your balance whenever you’re able. That level of transparency is what separates a good lender from a great one.

Lender Provider Maximum Funding Time to Funds Credit Standards Standout Benefit
Cub Cadet check website check website check website Manufacturer Financing
JetzLoan $35,000 24 Hours No Hard Credit Pull Fast Digital Funding
Gravely check website check website Subject to Credit Fleet Pricing Available
K and G Mowers check website check website No Credit Impact Prequal 0% APR for 48 Months
Manhattan Bank check website check website check website FDIC-Insured
Minute Loan Center check website Same Day Fair Credit Accepted Instant Online Approval
Yanmar check website check website check website Global Brand Support

Top-Rated Financing Solutions for Mowers

1. Cub Cadet

Cub Cadet – cubcadet.com

If you have your heart set on an Ultima Series zero-turn, Cub Cadet provides a direct path to ownership. Their financing plans are designed to bridge the gap between the showroom and your first yard pass quite rapidly. It’s a clever strategy to grab premium gear without draining your entire savings account in one go.

Since you are dealing directly with the manufacturer, the credit process is baked right into the sale. You avoid the headache of pitching your needs to a third-party bank that might not grasp the machine’s true worth. This keeps the entire transaction local and incredibly simple.

This route is a winner for homeowners who have a specific model in mind and want to stay within a trusted brand. Whether you are eyeing a snow blower or a riding mower, the terms are built around that specific piece of iron. Many shoppers can snag “no money down” deals, which is a godsend for seasonal laborers who need to keep their cash flowing for upkeep and fuel.

Pros:
  • Direct backing from the maker
  • Funding for specialized equipment types
  • Efficient, quick application workflow
Cons:
  • Terms vary depending on the specific model

2. JetzLoan

JetzLoan – jetzloan.com

When every second counts, JetzLoan is the sprinter in the field. They have mastered the art of speed, often getting funds into your hands within a 24-hour window. If your current mower decides to die right in the middle of your busiest season, this service is a total lifesaver.

For those in the landscaping industry, a broken machine isn’t just an annoyance; it is a direct hit to your daily income. JetzLoan plugs that leak by providing quick liquidity while traditional banks are still fumbling with their paperwork. It is built for the hustlers who simply cannot afford to stop working.

They provide capital up to $35,000 and won’t ding your credit score just to give you a quote. Because they use “soft pull” technology, you can shop around and compare monthly costs without any fear. It is the perfect way to window shop for rates before making a final commitment.

Pros:
  • Rapid 24-hour funding turnaround
  • Initial rates require no hard credit check
  • Substantial maximum loan amounts
Cons:
  • Purely digital interface may feel impersonal

3. Gravely

Gravely – gravely.com

Gravely is a heavyweight option for anyone treating lawn care like a serious professional vocation. Their financing structures are engineered for the long haul and the demands of a working business. They even provide specialized fleet pricing for professionals eager to scale up their entire crew’s capacity.

Commercial-grade financing differs significantly from what you’ll find in a residential store. Gravely’s options are tailored to account for the heavy usage and faster depreciation rates inherent in commercial machines. They realize a professional mower is a workhorse that runs much harder than a homeowner’s garden tool.

If your goal is to build out a fleet of commercial zero-turns, Gravely offers the structural backbone to make that dream a reality. They focus heavily on the professional who needs tools that can keep up with their work ethic. This may involve specialized lines of credit or tax-advantaged leasing as your client list expands.

Pros:
  • Outstanding fleet pricing opportunities
  • Built specifically for commercial use
  • Highly respected brand name
Cons:
  • Strict credit approval requirements apply

4. K and G Mowers

K and G Mowers – kgmowers.com

K and G Mowers serves up aggressive deals for those looking to squeeze every bit of value out of their budget. They offer 0% APR financing for up to 48 months on a variety of tractors and mowers. This is a massive win for anyone wanting to keep their cash liquid while upgrading their gear.

With 0% APR on the table, every single dollar of your payment goes toward the machine’s principal. You won’t find yourself being eaten alive by interest charges that could add thousands to the total cost. It is an incredibly efficient way to manage your capital.

Their system is incredibly user-friendly, permitting prequalification without touching your credit score. Operating out of Paris, TX, they also provide the comfort of local service and delivery. This hybrid setup—mixing modern digital prequalification with a physical shop—is perfect for those wanting fintech ease paired with a brick-and-mortar safety net.

Pros:
  • 0% APR for up to 48 months
  • Prequalify without impacting credit
  • On-site service and local delivery
Cons:
  • Physical operations are restricted to Texas

5. Manhattan Bank

Manhattan Bank – manhattanbank.com

When you crave the stability of a traditional institution, Manhattan Bank offers a rock-solid alternative. Being an FDIC-insured entity, they provide the peace of mind that comes with a government-backed bank. This level of security is vital when you are making massive commercial investments.

If your project requires a high-limit business loan and a deep dive into your company’s financial history, a bank is usually your best bet. They provide a wide array of personal and business loans tailored to many different financial scenarios.

While you won’t see the “instant” gratification of a fintech app, the oversight of a bank is invaluable for complex deals. If you are planning to build an equipment warehouse or buy a fleet of heavy tractors, a banking relationship can lead to much more flexible, long-term credit lines.

Pros:
  • Full FDIC-insured protection
  • Versatile business and personal loans
  • Reputable, established banking history
Cons:
  • Processing is likely slower than digital lenders

6. Minute Loan Center

Minute Loan Center – minuteloancenter.com

Minute Loan Center is a primary choice for those who need cash immediately and may have a complicated credit history. They prioritize rapid approvals, even for individuals with fair credit, and can handle same-day direct deposits. It is a perfect solution for those unexpected emergencies.

Picture a scenario where a mower breaks on a Monday, but you must have a replacement working by Tuesday to satisfy your clients. This is the ideal “emergency replacement” tool. Their process is transparent with no hidden fees, which helps lower the stress of a high-pressure purchase.

While you might pay higher interest rates due to the increased loan risk, the accessibility is a vital lifeline for keeping a business running. It is ultimately about ensuring your livelihood keeps moving even when things go sideways.

Pros:
  • Same-day funds disbursement
  • Approvals available for fair credit
  • Transparent with no hidden fees
Cons:
  • Rates may be steeper for non-prime borrowers

7. Yanmar

Yanmar – yanmar.com

Yanmar stands as a global benchmark for heavy-duty, high-caliber machinery. Though they are a massive international player, their financing is geared toward making world-class equipment accessible across the globe. Their structures often reflect the impressive resale value these machines command.

Because these machines hold their value so well, it can be much easier to secure a loan through specialized commercial or agricultural lenders. They are an excellent choice for anyone wanting top-tier engineering from a brand with a massive global footprint.

Choosing Yanmar is a long-term commitment to quality that transcends borders. When you finance one of these machines, you aren’t just buying a tool; you are investing in a piece of infrastructure designed to serve you for a decade or more.

Pros:
  • Top-tier machinery quality
  • Massive global brand presence
  • Extremely durable equipment
Cons:
  • Less focus on quick consumer-level loans

Calculating Your Real Expenses: Interest Rates and Lost Profits

Choosing between a manufacturer’s low-interest promotion and a rapid digital lending option requires a careful comparison of interest fees versus potential earnings. Imagine a scenario where a brand offers 0% APR for a 48-month term. Meanwhile, a quick lender like JetzLoan might charge a 5% interest rate but delivers the funds 4 days sooner. Which path truly serves your wallet?

Picture this: that extra 4-day window of liquidity enables you to finish three landscaping contracts, netting a $1,200 profit. In this specific case, the “costly” interest rate is actually a bargain. The velocity of your capital trumped the extra percentage points, proving that you must prioritize your total cash flow over simple interest rates.

On the flip side, a homeowner with plenty of liquid savings might lean toward paying upfront to dodge interest entirely. However, math tells a different story if your cash is sitting in a high-yield savings account earning 5%. If your mower loan only carries a 3% rate, paying in full is a costly mistake.

In that situation, you are essentially throwing money away by not leveraging the difference. Navigating these numbers is what separates a savvy investment from a heavy financial weight. You have to see the forest, not just the individual trees, when calculating your true expenditures.

Steer Clear of These Credit Traps

Before you ink that contract, take a deep breath and scrutinize every tiny detail. It is incredibly easy to get blinded by a small monthly installment. While a tiny number looks enticing on paper, high interest rates spread over a sixty-month term can effectively double the price of your equipment.

Don’t let the glossy brochures fool you. You must always determine the “Total of Payments” to understand the actual financial burden. Simply multiply each installment by the total number of months in your term. This quick math uncovers the real price hiding behind clever marketing schemes and keeps your budget honest.

You need to know every single cent that will eventually exit your bank account throughout the entire loan duration. It is better to be certain now than to feel regret later when the debt lingers longer than expected.

Look for lenders that provide a “no credit impact” prequalification process. This clever strategy lets you scout for deals from various providers, such as JetzLoan or K and G Mowers, without touching your credit score. Think of it as browsing store windows without actually stepping inside to buy anything yet.

Testing the waters with a soft inquiry is a smart way to shop for the best rates. It gives you the leverage to compare different terms without any risk to your financial standing.

Be on high alert for those sneaky “hidden” expenses lurking within the fine print. Certain institutions might slap you with origination fees or impose heavy penalties if a single payment is late. If your lawn care service is a professional operation, make sure your repayment schedule matches your revenue flow.

You might find it beneficial to inquire about “seasonal payment” structures specifically. These tailored plans let you pay larger sums during the busy summer months and smaller amounts throughout the dormant winter season. It is a lifesaver for commercial clients who need to keep their books balanced when the grass stops growing.

Many established companies are more than willing to offer these flexible arrangements. Such flexibility ensures that your cash flow remains steady even when the weather turns cold and the work dries up.

Secure the Best Rates on Tractor Financing for Your Next Purchase

By Uncategorized
Tractor financing

Secure the Best Rates on Tractor Financing for Your Next Purchase

Last updated: 2026-10-16

Finding the liquidity required to maintain a working farm frequently proves more exhausting than the physical labor of the harvest itself. Whether you are eyeing a massive fleet of combines to boost a large-scale operation or simply need one utility machine for a small hobby farm, your current contracts will govern your cash flow for years to come. It is a high-stakes game of math and timing.

A single slip-up with an interest rate or a sudden, unexpected balloon payment can send your seasonal budget into a tailspin. You really don’t want a grueling year of labor to devolve into an endless loop of debt. Selecting a lender shouldn’t just be about completing a transaction; it is about finding a partner who supports your growth rather than becoming a hurdle.

As you evaluate your choices, keep a close eye on the speed of funding and the flexibility of your repayment terms. You also need to weigh how a bank views your unique credit history. While the lightning-fast speed of a digital approval is tempting, don’t overlook the stability and competitive rates typically offered by traditional, brick-and-mortar institutions.

  1. Mahindra
  2. FastLendGo
  3. AgDirect
  4. Yanmar
  5. Manhattan Bank
  6. VivaLoan
  7. Roadrunner Financial

Our Selection Methodology

Selecting the right lenders required us to cast a wide net across the diverse landscape of modern agriculture. We didn’t want to just scratch the surface. Instead, we scoured the market to find a balanced blend of specialized equipment providers and local community banks.

Our goal was to ensure no farmer felt left behind in the selection process. We hunted for a diverse toolkit of options, prioritizing companies that offer quick turnaround times and approachable credit standards. It was vital to find lenders capable of funding everything from massive iron to small implements.

We ignored the glossy fluff found in sales pitches. Instead, our team focused on how these financial institutions integrate into the messy, beautiful reality of daily farm operations. We looked for partners, not just providers, ensuring our list reflects real-world utility.

How fast a bank says “yes” and what they demand as collateral served as our North Star. Some providers shine when it comes to lightning-fast digital requests using soft credit checks that keep your score intact. They are the sprinters of the lending world.

Conversely, traditional banks provide the marathon-runner stability needed for long-term, secured debt. We also weighed the “specialty” factor heavily. Does a lender exist specifically for high-ticket tractors, or are they better suited for the quick cash injection needed for a sudden mid-season repair?

This multifaceted approach guarantees a solution for every grower. Whether you are dropping a quarter-million dollars on a harvester or grabbing a $5,000 utility trailer, there is a fit. Every farm dances to its own drumbeat, and your financing should follow that lead.

Your business shouldn’t have to bend to fit a bank’s rigid, outdated mold. We believe the money should serve the machine, not the other way around. We have organized these findings to help you find your perfect match quickly.

Provider Loan Range Speed of Funds Credit Standards Primary Features
Mahindra refer to website refer to website 550 FICO minimum 6-year warranty options
FastLendGo $500 – $5,000+ Rapid disbursement All credit types Personal financing focus
AgDirect refer to website Most decisions in seconds refer to website New and used equipment
Yanmar refer to website refer to website refer to website Global availability
Manhattan Bank refer to website refer to website refer to website Personal and business
VivaLoan $100 – $15,000 As soon as tomorrow All credit types welcome Small personal loans
Roadrunner Financial refer to website Instant decisions All credit scores Powersports focus

Leading Agricultural Financing Providers

Mahindra

Mahindra – mahindratractor.com

Mahindra has carved out a massive presence within the global farming community. Their financing programs are tailor-made to address diverse requirements, serving as a lifeline for growers who might fall short of the strict criteria set by traditional banks. It is a dependable route for those seeking manufacturer-supported security and deep industry roots.

The lender opens doors for individuals maintaining a minimum 550 FICO score. This flexibility is a godsend for anyone facing a seasonal slump or those with a relatively thin credit history. Because they operate through an extensive dealer network, you can often sit down for a consultation and finish your application right on the showroom floor.

Pros:

  • Low threshold with a 550 FICO minimum
  • Supports borrowers with limited credit history
  • Highly respected brand with a massive footprint

Cons:

  • Approval is tied to specific contractual terms

FastLendGo

FastLendGo – fastlendgo.com

When time is of the essence, FastLendGo serves as a versatile lifeline. While their expertise lies in personal loans, their lightning-fast turnaround makes them a perfect tool for urgent farm expenses. Think of it as a way to cover sudden fuel costs or emergency equipment repairs that don’t quite fit into a standard budget. (fastlendgo.com)

If a sudden breakdown leaves you in a pinch, this lender moves with incredible speed. They serve a wide spectrum of clients, from those working to rebuild bad credit to high-earners seeking non-standard loan structures. Their digital-first approach is built for the modern era, ensuring you aren’t left waiting weeks for a bank’s committee to deliberate.

Pros:

  • Rapid access to liquid capital
  • Service coverage across many US states
  • Adaptable for various credit profiles

Cons:

  • Primarily personal loans rather than agricultural gear

AgDirect

AgDirect – agdirect.com

AgDirect stands as a heavy hitter when it comes to financing specialized farm machinery. Their reach extends to new equipment, used models, and even private sales, whether you are buying from a dealer or at a local auction. This versatility is a huge advantage when you spot a deal and need funding that works as fast as an auctioneer’s hammer.

Navigating their digital platform is a breeze. Most applicants receive a credit verdict within seconds, which is vital when high-demand machinery is being snatched up by competitors. This speed eliminates the friction of old-fashioned paperwork, making it a highly efficient way to secure the equipment you need before it disappears.

Pros:

  • Near-instant credit decisions for most users
  • Valid for new, used, and private transactions
  • Streamlined online application experience

Cons:

  • Focused on equipment rather than general cash needs

Yanmar

Yanmar – yanmar.com

Yanmar is a powerhouse on the international stage, bringing global expertise to your doorstep. With operations spanning from Asia to Europe and the United States, they are a rock-solid choice for those wanting standardized, world-class service. Their reputation for reliability is backed by a massive, widespread presence.

Partnering with a lender aligned with the manufacturer means you are working with experts who truly grasp the value of your machinery. They understand that a tractor’s utility is dictated by the seasons, allowing them to suggest repayment schedules that a standard bank might never consider. This alignment can result in much better terms for specialized gear.

Pros:

  • Extensive global reach and reliability
  • Expertise driven by manufacturer links
  • Wide regional availability for users

Cons:

  • Availability for certain products can be regional

Manhattan Bank

Manhattan Bank – manhattanbank.com

Manhattan Bank provides a traditional, steady hand for your financial needs. By offering a blend of personal and business loans, they serve as a vital partner for established farming operations seeking long-term structure. For a multi-generational farm, having a stable banking relationship often carries more weight than the speed of a loan.

If you prefer a human touch over a digital interface, you can speak directly with a loan officer. This is a lifesaver when dealing with complex issues like major facility upgrades or buying land. Walking into a branch to explain your specific harvest cycles offers a level of comfort that software simply cannot replicate.

Pros:

  • Direct access to human loan officers
  • Security of FDIC-insured banking
  • Diverse range of personal and business products

Cons:

  • May require more paperwork than fintech firms

VivaLoan

VivaLoan – vivaloan.com

VivaLoan is built specifically for the person who needs cash without drowning in paperwork. They specialize in smaller personal loans, typically ranging from $100 to $15,000. This makes them an agile option for bridging minor gaps, such as a sudden broken part that requires an immediate trip to the supplier.

The primary draw here is the sheer speed; funds can be in your account as early as the next business day. It is an incredibly efficient way to handle unexpected expenses, like a sudden vet bill or a small equipment repair. Think of it as a middle ground between a credit card and a heavy commercial loan.

Pros:

  • Rapid funding, often by the next day
  • Low minimum loan amounts available
  • Open to all credit tiers

Cons:

  • Loan limits are too low for major machinery

Roadrunner Financial

Roadrunner Financial – roadrunnerfinancial.com

Roadrunner Financial operates in the niche market of utility vehicles and powersports. They are an ideal match if your daily farm tasks rely on side-by-sides, ATVs, or golf carts rather than massive tractors. Many modern agricultural setups depend heavily on these smaller, mobile units to get the job done.

Their pre-qualification process is streamlined and won’t ding your credit score. This lets you scout different financing tiers without any risk to your financial standing. You can test the waters and see what you qualify for without the fear of a hard inquiry affecting your ability to get a larger loan later.

Pros:

  • No impact to credit score for rate checks
  • Specialists in utility and powersports
  • Real-time decision-making process

Cons:

  • Limited to specific utility-style vehicles

Evaluating Your Real Debt Obligations

It is incredibly easy to get seduced by a small monthly installment. While keeping your immediate cash flow smooth feels like a victory, looking solely at those individual checks is a trap. You really need to weigh the Total Cost of Ownership (TCO) for every dollar you borrow.

Think of it like planting a crop that grows slowly but requires constant feeding. A financing plan stretched over seven years with a modest interest rate might end up being much more expensive. In fact, you could wind up paying $5,000 more in total interest than if you had chosen a five-year term with a higher rate.

Don’t let the shiny brochure fool you into signing away your future profits. Before you ink the deal, you must scrutinize the fine print to ensure your farm remains profitable through every season.

Before you put pen to paper, keep these three critical elements in mind:

  • Amortization Schedule: Take a close look at how your payments are split. During the initial years of the loan, are you actually chipping away at the principal, or is most of your money simply vanishing into interest payments?
  • Prepayment Penalties: Suppose you have a bumper crop and find yourself flush with cash. If you try to settle the debt ahead of schedule to dodge interest, will the bank hit you with an unexpected penalty fee?
  • Variable vs. Fixed Rates: When inflation starts to bite, variable rates can turn into a nightmare if market rates climb. Opting for a fixed rate offers the peace of mind and budgetary stability your long-term planning requires.

Nailing Your Loan Application

Whether you’re walking into a brick-and-mortar bank or tapping away at a fintech app, the caliber of your paperwork dictates your fate. The speed at which you get a green light, as well as the interest rates offered, hinges entirely on how you present your case. Lenders are essentially looking for proof that you aren’t a gamble.

They want to see a seasoned operator who has a roadmap for the funds. If you look like you’re just throwing spaghetti at the wall, you’ll likely hit a wall yourself. To smooth the path toward approval and secure the most favorable terms, you need to be a step ahead of the curve.

Think of your application as a professional pitch. You aren’t just asking for money; you are presenting a business case that makes sense. Taking the time to tidy up your records now can save you a mountain of headaches when the clock is ticking and the dealer is waiting.

  1. Compile Your Fiscal Records: Dig up your tax returns from the previous two years. You will also need current profit and loss (P&L) statements along with your latest balance sheets. Keeping these files organized and ready for a quick upload is the best way to dodge unnecessary delays.
  2. Identify the Machinery’s Worth: You need to be specific about what you are buying. Grab the exact year, make, model, and serial number for the equipment. If you’re eyeing a pre-owned machine, make sure you’ve done your homework on its current market valuation.
  3. Audit Your Credit History: Do not leave your credit score up to chance. It is wise to pull your own report first to catch any mistakes before a lender sees them. If your score is currently lagging, be ready to tell the story behind it, such as the natural ebb and flow of seasonal debt cycles.
  4. Draft a Repayment Strategy: You must demonstrate exactly how this machine will put money back into your pocket. Don’t just say you need it; explain the ROI. For instance, you might argue, “Adding this harvester will slash our labor expenditures by 15%.”

Deciding on Your Financing Strategy

Before you put pen to paper on any agreement, scrutinize the complete price of your debt. It is easy to get swept away by a tiny monthly installment, but you must weigh the cumulative interest accumulated over the entire loan duration.

Chasing the smallest monthly bill can be a double-edged sword. A reduced monthly commitment frequently signals a much extended repayment period, which can ultimately drain your wallet far more than anticipated through the years of interest accrual.

Don’t let the availability of a shiny new machine cloud your judgment. It is vital to resist the urge to sign a deal hastily just because the tractor is sitting on the dealer’s lot waiting for a home.

Make it a habit to weigh the specific offerings of manufacturer-linked lenders against the terms provided by a local community bank. You might find that a local bank provides superior interest rates for the long haul.

On the flip side, the manufacturer might win on immediate ease of use and specialized insurance protections. Finding the sweet spot between these two options requires a bit of legwork but pays off in the end.

Lastly, your personal credit history plays a massive role in the outcome. If your credit score isn’t sitting at the top of the mountain, you should pivot your attention toward more flexible lenders.

Companies like VivaLoan or Mahindra are known for being quite accommodating to various credit backgrounds. They understand that a farmer’s wealth isn’t always found in a single number on a report.

Taking a moment to gauge your financial standing before you hit the showroom floor will save you mountains of headache. Being prepared helps you grab the heavy machinery you need to expand your operation without unnecessary stress.