Notice: Function _load_textdomain_just_in_time was called incorrectly. Translation loading for the wpforms-lite domain was triggered too early. This is usually an indicator for some code in the plugin or theme running too early. Translations should be loaded at the init action or later. Please see Debugging in WordPress for more information. (This message was added in version 6.7.0.) in /home/howhumansthink/public_html/wp-includes/functions.php on line 6131

Notice: Function _load_textdomain_just_in_time was called incorrectly. Translation loading for the salient domain was triggered too early. This is usually an indicator for some code in the plugin or theme running too early. Translations should be loaded at the init action or later. Please see Debugging in WordPress for more information. (This message was added in version 6.7.0.) in /home/howhumansthink/public_html/wp-includes/functions.php on line 6131

Notice: Function _load_textdomain_just_in_time was called incorrectly. Translation loading for the salient domain was triggered too early. This is usually an indicator for some code in the plugin or theme running too early. Translations should be loaded at the init action or later. Please see Debugging in WordPress for more information. (This message was added in version 6.7.0.) in /home/howhumansthink/public_html/wp-includes/functions.php on line 6131

Notice: Function _load_textdomain_just_in_time was called incorrectly. Translation loading for the salient domain was triggered too early. This is usually an indicator for some code in the plugin or theme running too early. Translations should be loaded at the init action or later. Please see Debugging in WordPress for more information. (This message was added in version 6.7.0.) in /home/howhumansthink/public_html/wp-includes/functions.php on line 6131
October 2026 – Page 400 – Will Steinberg, MD MSPH Skip to main content
Monthly Archives

October 2026

Get Quick Cash with Esign Loans for Bad Credit Today

By Uncategorized
Esign loans for bad credit

Get Quick Cash with Esign Loans for Bad Credit Today

Last updated: 2026-10-16

Navigating a financial crisis when your credit score is bottoming out can feel like wading through a heavy downpour without any cover. You are likely hunting for immediate funds, yet major banks frequently shut you out before you even get a foot in the door. In this climate, hunting for rapid approvals paired with e-sign capabilities represents the most streamlined route to finding stability.

When sudden car troubles or a pile of hospital invoices threaten your budget, you simply cannot afford to wait a fortnight for a person to review your file. The digital revolution has flipped the script entirely. What once required mountains of physical paperwork and days of waiting is now something you can wrap up using a smartphone while relaxing at home.

Our curated selection focuses on lenders that truly grasp the value of time. When you prioritize digital signing features, being able to access funds quickly becomes the ultimate priority. We investigated how these specific providers manage different types of credit history to ensure you find a practical solution that fits your unique circumstances.

Our review process went far beyond merely comparing APRs. We scrutinized the hurdles within their signup steps, the clarity of their mobile platforms, and the actual timing of the deposit into your checking account following your electronic signature. We wanted to see who delivers on their promises when the clock is ticking.

  1. Lift Credit
  2. OneMain Financial
  3. JetzLoan
  4. Avant
  5. Upgrade

Our Methodology for Testing Online Lenders

Our team focused heavily on user accessibility and the overall simplicity of the online application journey. Providing capital is only part of the story; the experience must be seamless from the initial tap to the eventual e-signature. We hunted for companies that bypass the red tape usually found at a brick-and-mortar bank.

We measured the exact number of hurdles standing between a user and a final decision. Our testers watched closely to see if you’re stuck uploading scanned paperwork or if the platform uses smart automation to grab data instantly. This specific detail is a lifesaver when you are racing against the clock.

Transparency regarding total loan sums and how quickly the cash hits your pocket was a top priority. When a car breaks down, every minute feels like an hour. A firm that promises rapid relief but drags its feet for five days simply doesn’t qualify as a fast-acting solution for emergencies.

We wanted to pinpoint providers offering a genuine way forward without masking terms in thick, confusing legalese. We took a magnifying glass to the small print for those with limited credit histories. Our focus remained on how they treat borrowers who possess steady paychecks but lack decades of financial history.

Company Funding Range Payout Velocity Eligibility Repayment Structure
Lift Credit check website Same day Regardless of credit Installment
OneMain Financial $1,500 – $30,000 As soon as 1 hour check website 24-60 months
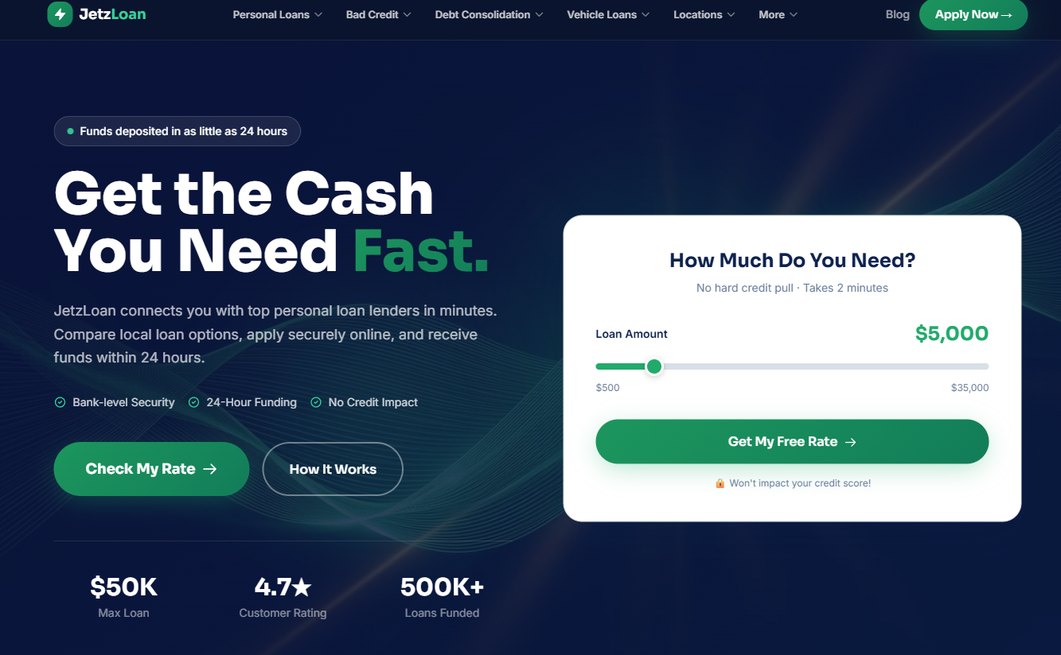
JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull check website
Avant check website check website check website check website
Upgrade Up to $50,000 Fast funding check website Fixed rate

Top-Rated Lenders for Rapid Online Cash

1. Lift Credit
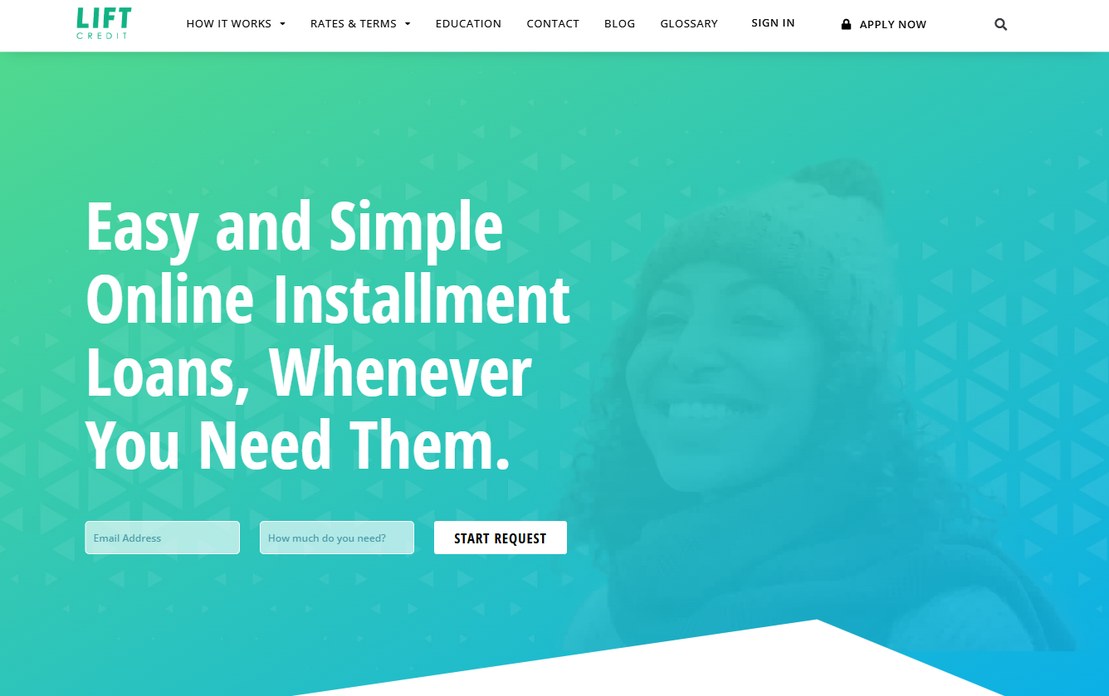
Lift Credit – liftcredit.com

If you reside in Missouri, Nevada, Idaho, or Utah, Lift Credit might be your best ally. They specialize in installment-based borrowing, which often carries a much lighter burden than the predatory payday loans targeting those with shaky credit. Traditional payday lenders typically demand one massive, overwhelming payment, often leaving borrowers drowning in a sea of recurring debt.

To prevent such a financial shipwreck, Lift Credit utilizes an installment strategy. Instead of one giant bill, you settle your debt through smaller, bite-sized payments over a fixed timeline. This method ensures you can keep your head above water even when things get tight.

The digital application moves like lightning, taking only a few moments to complete on your computer. It is an ideal pick for anyone wanting to bypass the hassle of visiting a physical storefront. Just ensure you have your valid ID and most recent pay stub ready for uploading to secure same-day funding.

Pros:
  • Access to same-day funding
  • Open to any credit standing
  • Manageable and simple repayment cycles
Cons:
  • Limited to specific states
  • Availability is not nationwide

2. OneMain Financial
OneMain Financial – onemainfinancial.com

OneMain Financial acts as a sturdy bridge, blending the convenience of modern apps with the reliability of traditional banking. With a massive network of 1,300 branches, they offer a friendly human element that purely digital lenders often lack. This is a lifesaver if you hit a snag with an electronic signature or have a complex income source.

Gig workers and seasonal earners, in particular, will appreciate being able to chat with a real person about their unique earnings. They provide a wide range of assistance, offering loan amounts that stretch from $1,500 all the way up to $30,000.

You can use their digital interface to scout potential terms in roughly five minutes. It is a perfect way to weigh your options without being tied down or hurting your credit score. They tend to look at your whole financial picture rather than just obsessing over a single FICO number.

Pros:
  • Huge branch network for in-person aid
  • Quick disbursement after signing
  • A diverse range of loan totals
Cons:
  • Requires a formal signing period
  • In-person visits might be necessary

3. JetzLoan
JetzLoan – jetzloan.com

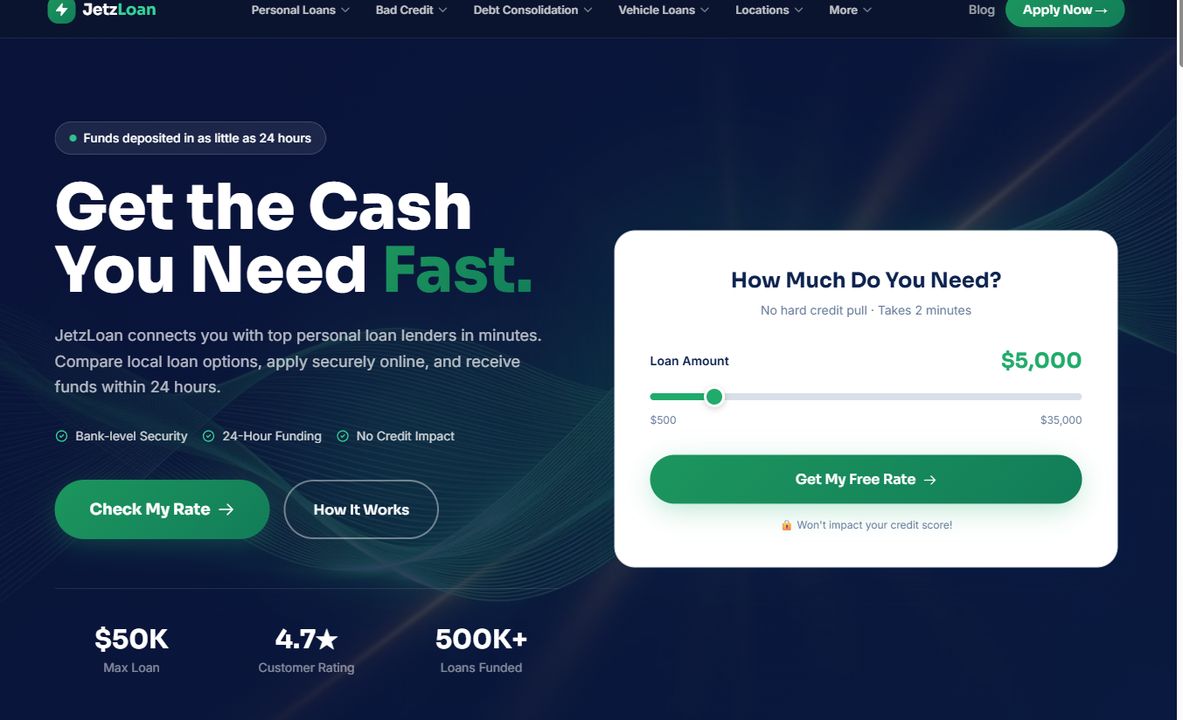
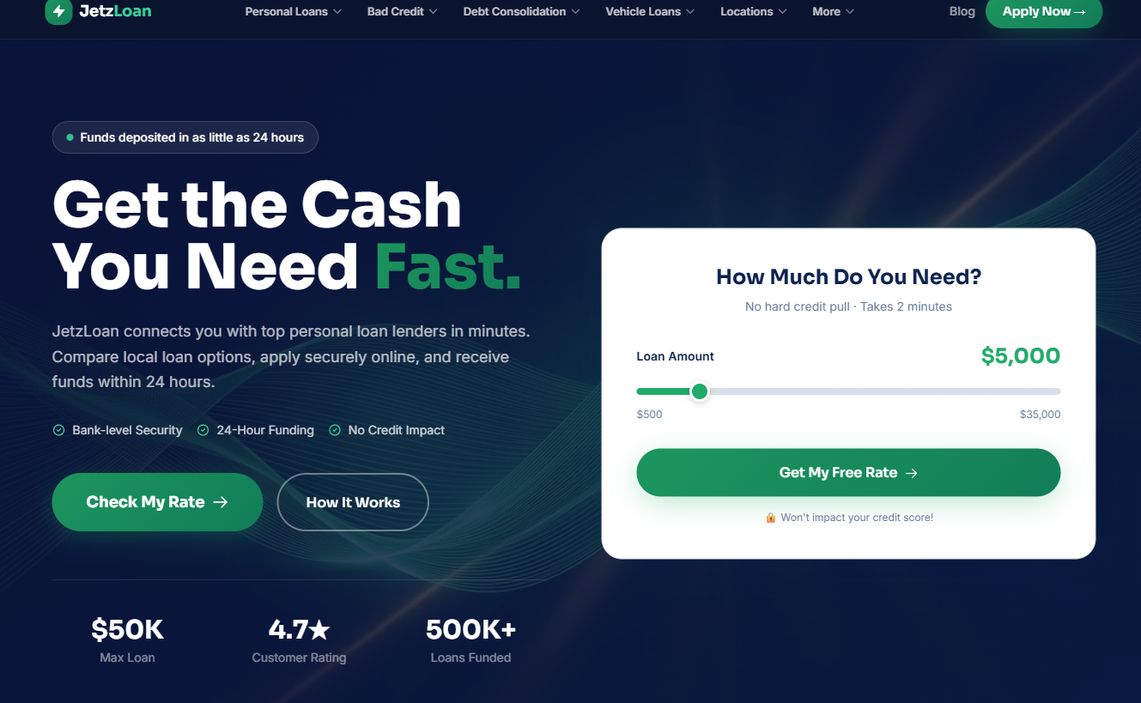
JetzLoan functions as a high-speed matchmaker in the lending landscape. Their specialty is slashing the wait time, moving you from the initial application to receiving funds in as little as 24 hours. By connecting you to a diverse group of premium lenders, they spare you the headache of repetitive paperwork for every individual company.

Think of them as a high-powered search engine tailored specifically for personal loans. Rather than you wandering from site to site, JetzLoan handles the heavy lifting, finding the exact lenders most likely to say “yes” to your specific profile.

A major perk of their service is the ability to see your rates without a hard credit inquiry. This is a massive distinction to keep in mind. While a “hard pull” leaves a mark on your report and can dent your score, a “soft pull” is merely a quick glance to see if you qualify.

This allows you to hunt for the best possible deal without causing further damage to your credit history. It is a low-stakes way to check for amounts up to $50,000 while you hunt for the most favorable interest rates available.

Pros:
  • Rate checks without hard credit pulls
  • Rapid 24-hour funding potential
  • Highly rated for their transparency
Cons:
  • Routes you to third-party lenders
  • Speed depends on the final lender

4. Avant
Avant – avant.com

Avant aims to be a long-term companion in your financial journey rather than a mere cash provider. They offer a versatile toolkit, including credit cards and installment loans, designed to support you through various life milestones. Their core philosophy is centered around providing flexible, adaptable choices.

This flexibility is a godsend if you are attempting to “reset” your financial habits. For example, you could use one installment loan to sweep up several smaller, high-interest debts into one single monthly bill. It is an excellent way to declutter your financial life.

Whether you are facing a sudden emergency or need to consolidate debt, Avant offers tailored paths. Those with moderate credit might find success with their credit card options, whereas someone needing a large sum for home repairs might prefer their installment loans.

Pros:
  • Variety of different financial products
  • Focuses on your long-term health
  • Intuitive digital management tools
Cons:
  • Specific products have stricter rules
  • Not a universal solution for all

5. Upgrade
Upgrade – upgrade.com

As a titan in the personal loan industry, Upgrade serves a massive community of over 8 million clients. They provide substantial loans, reaching up to $50,000, featuring fixed rates that ensure your monthly budget stays predictable. This makes them a top-tier option for major expenses like medical bills or home improvements.

Because your interest rate is locked in, your monthly obligations will never change unexpectedly. This acts as a vital shield against inflation or sudden shifts in your personal spending. You won’t have to deal with the shock of a rising interest rate.

Their entire digital ecosystem is deeply integrated, offering everything from standard personal loans to rewards-based checking accounts. You can check your potential rate for free, giving you a clear picture of your standing before you commit. This “no-obligation” approach lets you weigh payments against your income before signing anything.

Pros:
  • Substantial loan amounts offered
  • Predictable payments with fixed rates
  • Wide array of financial services
Cons:
  • May not lead for perfect credit
  • Broad ecosystem may feel complex

Choosing Your Path: Installment Options vs. Quick Cash

When your bank account is running on fumes, the temptation to grab any available cash is strong. You might feel like you’re just trying to keep your head above water. However, rushing into a bad deal is a slippery slope that many people fall down quite easily.

It is vital to distinguish between a personal installment loan and the dreaded payday loan. Think of an installment loan as a roadmap; it has a clear destination with a fixed end date and controlled interest rates. You know exactly when the journey ends.

In contrast, a payday loan acts more like a temporary bridge that often collapses under your weight. These loans are notoriously difficult to settle. When you look at the annual percentage rate, the numbers can skyrocket to 400% or even higher, making it a heavy burden.

Using these short-term fixes often feels like a quick fix, but it frequently results in a debt spiral. Instead of solving a problem, you might just find yourself digging a deeper hole. It’s a dangerous game of musical chairs with your finances.

Comparison Points Personal Installment Loan Payday/Short-Term Loan
How long to pay back Months to Years Typically 2-4 Weeks
Annual Percentage Rate Moderate (Fixed or Variable) Extremely High
Effect on your score Can build credit if paid on time Often no benefit; can harm credit if defaulted
Overall expense Predictable and manageable Can lead to a cycle of debt

If you can snag a personal loan from one of our recommended lenders, you’ll likely be in much better shape. It is a far safer bet than walking into a neighborhood check-cashing shop. Don’t let the immediate pressure cloud your judgment.

Even if the interest rates feel a bit steep compared to a standard mortgage, they are still a drop in the bucket compared to predatory lenders. Always aim for the most stable option available to protect your future self.

Finding Your Perfect Lending Match

Finding the ideal lender feels a lot like hunting for a new pair of boots. You wouldn’t want them to pinch your toes, so why settle for a loan that doesn’t suit your life? If you’re in a pinch and need cash before sunset, prioritize how quickly the provider can deposit funds.

On the other hand, if your credit score makes you a bit nervous, seek out companies that utilize soft credit pulls. This allows you to shop around for the best interest rates without damaging your precious score.

For those navigating a tangled web of previous debts, a traditional brick-and-mortar institution can be a lifesaver. Companies like OneMain Financial offer a physical desk where you can sit down and talk.

Having a real human being to walk you through your income documentation can save you from a massive headache down the road. It turns a cold digital transaction into a guided conversation.

Don’t let a small monthly bill lure you into a financial trap. It is easy to get blinded by a low installment amount, but there is always a catch hidden in the math.

A lower monthly cost frequently implies a much longer repayment window. Take a $5,000 loan with a $100 monthly installment as a prime example. If that debt drags on for 72 months, you will end up handing back almost twice the original amount due to interest.

Before you sign on the dotted line, comb through the fine print for any sneaky late fees. You also need to check for prepayment penalties that might haunt your future progress.

It sounds backwards, but some lenders actually charge you extra for being responsible and settling your debt early. Always hunt for a “no prepayment penalty” clause in your contract.

Securing this type of flexibility is crucial for your long-term wealth. It ensures that as you get your finances back on track, you aren’t punished for your own financial victories.
Top Rated Plastic Surgery Loans for Bad Credit: Secure Your Dream Look Now

By Uncategorized
Plastic surgery loans for bad credit

Top Rated Plastic Surgery Loans for Bad Credit: Secure Your Dream Look Now

Last updated: 2026-10-16

Stepping into a clinic should feel like a fresh start, not a plunge into a pit of monetary despair. Too often, patients gaze at their desired cosmetic improvements while their credit reports look grim. This gap between aesthetic dreams and bank balances can feel like a mountain too steep to climb.

When your wallet is empty, the joy of a potential transformation often evaporates. It is a bitter pill to swallow when the fear of mounting debt begins to cloud your vision. Instead of anticipating a glowing recovery, you end up tossing and turning, wondering about the monthly cost.

Securing funding for surgical enhancements requires looking far beyond the glossy advertisements. You need a partner that truly grasps the nuance of healthcare financing, particularly if your financial history is a bit messy. Big-name banks typically play it safe with strict rules that shut the door on anyone with a high debt-to-income ratio or a minor hiccup in their payment history.

We have rounded up the premier solutions for navigating the choppy seas of medical financing and reconstruction this year. If you are struggling with less-than-stellar credit, these providers might just be your lifeline.

  1. JetzLoan
  2. Cherry
  3. CareCredit
  4. United Credit
  5. Acorn Finance
  6. MedLoan Finance

Our Criteria for Selecting Medical Loan Providers

Finding a lender when your credit score is struggling can feel like looking for a needle in a haystack. While high-scorers have endless options, those with less-than-perfect histories often face immediate rejection. We set out to find the companies that actually open their doors to everyone.

Our research prioritized lenders known for high success rates and honest, straightforward contracts. We wanted to avoid those sneaky “gotcha” moments that plague the financing world. Nobody likes a sudden mountain of fees appearing right when you think you are ready for your procedure.

Unexpected costs, such as hefty origination fees or ballooning interest rates after a teaser period, are the enemies of a budget. Discovering you are ineligible after paying a non-refundable deposit would be a nightmare. We filtered for transparency to protect your hard-earned money.

We also placed a heavy emphasis on how quickly you can actually get your hands on the cash. Speed is everything when you are planning a life-changing surgery. We looked for services that offer lightning-fast results to keep your recovery timeline on track.

Lastly, we scrutinized the credit check process to ensure you could shop around safely. We prioritized “soft pull” options so you can compare various rates without bruising your score. This allows for stress-free browsing while you finalize your medical plans.

Financing Provider Loan Limits Time to Funds Effect on Credit Score
JetzLoan $500 – $35,000 Within 24 hours No hard credit pull
Cherry See site As soon as approved No hard credit check
CareCredit See site Immediate decisions Prequalify with no impact
United Credit See site See site See site
Acorn Finance See site See site No credit score impact
MedLoan Finance $500 – $100,000 See site See site

Navigating Interest Rates and Loan Structures

Before you sign on the dotted line, you must grasp how different interest structures actually impact your wallet. Financing options generally split into two distinct camps: revolving lines and installment-based loans. Think of revolving credit, which is offered by services like CareCredit, as a flexible digital reservoir.

Once you deplete your available funds, paying down your balance restores your purchasing power. This flexibility is a lifesaver if you need several dermatological appointments or extended orthodontic care over a long period. However, it is a double-edged sword that demands strict discipline to master.

If you’re not careful and leave a large balance hanging, those interest rates can snowball like an avalanche. You might find yourself trapped in a cycle of debt if you aren’t vigilant. It is essential to treat this credit like a tool rather than free money.

On the other hand, installment loans from companies such as MedLoan Finance or JetzLoan behave much more predictably. These lenders hand you a single large sum upfront, which you then settle through set monthly installments. It is a straightforward path for those undergoing major transformations.

For a singular event like a tummy tuck or a rhinoplasty, this structure is often the smarter choice. Because the schedule is fixed, you aren’t left guessing what your next bill will look like. It brings a sense of stability to your financial planning during a major life change.

When weighing your options, don’t just fall for a tiny monthly payment that looks easy on the eyes. You must scrutinize the Annual Percentage Rate (APR) to see the real picture. A long 60-month term might feel light on your monthly budget, but the total cost could be staggering.

In many cases, you could end up paying twice what the surgeon originally quoted due to accumulated interest. Always do the math on the total amount repaid rather than just the immediate monthly cost. It’s the difference between a manageable plan and a long-term financial burden.

Premier Financing Alternatives for Your Procedure

1. JetzLoan

JetzLoan – jetzloan.com

Think of JetzLoan as a rapid financial bridge when you find yourself in a pinch. If you need cash for a medical necessity urgently, this service is designed for lightning speed. They aim to deposit your funds in as little as 24 hours, making them a true powerhouse for those unexpected costs.

Whether it is an emergency dental fix or a sudden corrective operation, you won’t have to wait around. You can use (jetzloan.com) to secure the funds you need when time is of the essence. It is perfect for those last-minute surgical surprises that simply cannot wait for a slow banking process.

The interface is incredibly smooth, allowing you to scout potential rates in a mere two minutes. Because they utilize a “soft pull” method, your credit score won’t take a hit while you are window shopping. You can see your estimated interest and the length of the term before ever committing to a formal application.

For those looking to borrow up to $35,000, this is a stellar way to bypass the usual red tape found at traditional banks. When you need a significant amount of money quickly, this service gets the job done. It is the perfect solution when timing is the most critical factor in your medical journey.

  • Pros: Rapid funding delivery, no credit score damage during inquiries, and amounts up to $35,000.
  • Cons: The ceiling on loan amounts might be lower than some niche medical lenders.

2. Cherry

Cherry – withcherry.com

Cherry has carved out a massive reputation in the healthcare landscape, earning the trust of tens of thousands of medical providers. It is a go-to option for patients who crave a “no fuss” experience. The application process is incredibly fast, often finishing in about 35 seconds.

This speed is a lifesaver for busy individuals who might be bouncing between different specialists in a single afternoon. Because the system is so streamlined, it is widely considered an ideal choice for anyone on a tight schedule. It makes managing medical expenses feel like a breeze.

If you are looking for high approval rates, this might be your best bet. The ease of use can act as a balm for the stress of accumulating medical debt. Many doctors prefer working with Cherry because it integrates into the office checkout process, making your transaction feel seamless.

Essentially, it functions as a specialized digital payment tool for the medical world. It removes the awkwardness of talking about money in a doctor’s exam room. You can keep your eyes on your health and your recovery instead of worrying about your wallet.

  • Pros: Exceptional approval odds, instant results, and a lightning-fast application.
  • Cons: Your eligibility depends on the specific doctor’s participation and medical terms.

3. CareCredit

CareCredit – carecredit.com

CareCredit is a household name that you will likely recognize, as it is accepted at hundreds of thousands of various locations. It operates as a credit card specifically designed for health and wellness needs. This versatility means it covers much more than just cosmetic surgery.

You can use it for vision care, pet-related veterinary services, or even certain types of physical therapy. This wide range of applications makes it a highly flexible tool for many different life situations. It is like a Swiss Army knife for your medical expenses.

The true strength of this card lies in its ability to let you pay over time, which helps protect your cash flow during healing. Many patients take advantage of “deferred interest” promotions. These allow you to pay without interest for 6, 12, or even 24 months.

However, beware: this is a classic double-edged sword. If you miss that final deadline and fail to pay the full balance, interest can be backdated to the very first day of your purchase. This could result in a massive, sudden bill that catches you completely off guard.

  • Pros: A vast network of locations, versatile financing, and immediate credit decisions.
  • Cons: Requires a formal credit approval; high interest rates if terms aren’t met.

4. United Credit

United Credit – unitedcredit.com

United Credit prefers building lasting relationships rather than just chasing a single transaction. They collaborate with a diverse group of lenders to provide consumers with a wide array of options. This variety acts as a lifeline for people with many different credit profiles.

Whether your credit is pristine or quite bad, they aim to find a way forward. They don’t believe in a “one size fits all” strategy. Instead, they act as a direct conduit to a much larger marketplace of lending specialists.

Their philosophy is rooted in supporting the consumer’s personal journey and overall well-being. By maintaining an extensive network, they can often uncover a path to funding when a traditional bank might say no. This is a huge advantage for many people.

They are particularly helpful for individuals who might be denied by major banks because they are “self-employed.” If your income stream is non-traditional, they can still help. It is a solid choice for those wanting a personalized experience where the lender looks at the person, not just a number.

  • Pros: Multiple lender options and support for diverse credit backgrounds.
  • Cons: The process may take longer due to the variety of lender choices.

5. Acorn Finance

Acorn Finance – acornfinance.com

Acorn Finance takes a slightly different approach by offering funding often used for major medical or home projects. They specialize in matching borrowers with customized rates without the usual sting of a credit score hit. It is a very transparent way to shop around.

Think of them as an aggregator that brings various specialized lenders together into one single dashboard. This makes comparing different options much easier for the consumer. It saves you from the headache of visiting dozens of different websites.

Users often praise the platform for the speed of its SMS and email application processes. Even if your credit isn’t perfect, they work hard to find a provider or contractor who can meet your specific requirements. It is about finding the right fit for you.

This makes them an incredible resource for complex medical transformations involving several specialists. If you need full facial reconstruction or extensive orthopedic surgery, they keep everything organized in one place. It is ideal for multi-stage procedures.

  • Pros: No impact on credit score when checking rates and easy SMS/Email applications.
  • Cons: Better suited for large project financing rather than small cosmetic tweaks.

6. MedLoan Finance

MedLoan Finance – medloanfinance.com

MedLoan Finance is a dedicated player that stays laser-focused on the medical sector. They specialize in specific procedures like cosmetic, dental, or bariatric surgery. They are built to serve people from all backgrounds and various credit histories.
Their goal is to provide the “best medical financing around” through a very specialized form of medical underwriting. Because they understand the industry, they can offer much more relevant solutions. They aren’t your typical general-purpose lender.

With loan amounts that can reach up to $100,000, they are a serious contender for major aesthetic or reconstructive journeys. They understand the unique timelines required for medical recovery. They even offer specialized terms, such as the possibility of interest-free periods for 12 to 18 months.

This can be a massive weight off your shoulders during recovery. If you are unable to work for a short time while healing, this provides a vital cushion. It is peace of mind when you need it most during a significant life change.

  • Pros: Very high maximum loan amounts, medical focus, and potential interest-free periods.
  • Cons: Rates and terms are dependent on the specific type of medical procedure.

Mapping Out Your Path to Funding

Selecting a lender involves much more than hunting for the smallest interest rate. You really need to find a financial ally that aligns perfectly with your medical goals. It is a bit like matching a key to a lock; the wrong fit will only cause friction later on.

If you are looking for a quick fix for a minor cosmetic enhancement, speed is often your best friend. In these cases, a rapid-funding provider like JetzLoan might be the most sensible route to take. They specialize in getting you moving without the long wait times.

On the flip side, major reconstructive procedures carry much heavier price tags. For these large-scale operations, you might require the substantial borrowing limits offered by MedLoan Finance. This ensures you can cover everything from the surgeon’s fee and anesthesia to facility costs and aftercare.

Protecting Your Financial Standing

Don’t fall into the trap of submitting several applications in a frantic burst. This behavior can make you appear financially unstable to potential creditors. Such a move might cause your credit score to take a sudden, painful dive.

Every time a company conducts a “hard pull” to finalize your approval, they leave a permanent mark on your report. Think of it as a digital footprint that lenders follow closely. You want those footprints to be sparse and intentional, not a messy trail of desperation.

Instead, you should lean heavily on “pre-qualification” or “no impact” assessment tools first. This strategy lets you scout your actual options without any damage to your credit. It allows you to construct a mental map of your future debt before you sign anything.

Knowing the true cost of borrowing is vital before you ever touch that surgical schedule. It is always better to walk into a consultation with a clear financial picture. You wouldn’t go into a high-stakes poker game without knowing the stakes, so don’t do that with your health.

Understanding the Hidden Risks

When you see “interest-free” windows advertised, proceed with extreme caution. Many medical lenders offer these promotional periods as a way to attract clients. However, these offers often come with significant strings attached that are tucked away in the fine print.

If you miss a single payment or fail to settle the full balance by the deadline, you could face retroactive interest. This isn’t just a minor nuisance or a small administrative fee. Depending on your principal, the sudden jump in cost can reach into the thousands of dollars.

Stay on top of your schedule by setting up automatic payments to prevent accidental slips. You should approach these medical loans with the same level of discipline you would use for a mortgage. Treating your debt with high priority will save you from many sleepless nights.

Get Fast Bad Credit Loans Arkansas: Compare Best Rates Online Today

By Uncategorized
Bad credit loans arkansas

Get Fast Bad Credit Loans Arkansas: Compare Best Rates Online Today

Last updated: 2026-10-16

Navigating finances throughout the Natural State often feels like wandering through dense brush if your credit rating is lagging. Many residents find themselves facing unexpected medical costs or sudden vehicle maintenance without a financial cushion to fall back on. Once those unpaid invoices begin to stack up on the counter, securing a dependable source of funding becomes a vital necessity.

In the sweltering heat of a Little Rock summer, an air conditioning failure is far more than a mere nuisance; it is a genuine emergency. The same logic applies to Northwest Arkansas, where a broken work truck can halt your livelihood instantly. The desperate scramble to find immediate liquidity can feel like being caught in a whirlwind when you’re simply trying to stay afloat.

As you hunt for financial assistance, prioritize companies that value clarity and rapid processing. It is essential to grasp the full price of your loan before you sign any legal documents. We have compiled a list to illuminate which lenders provide the smoothest routes for people attempting to mend their credit standing. One unexpected surcharge or a misunderstood interest rate can quickly transform a helpful lifeline into a heavy anchor.

  1. FastLendGo
  2. Balance Credit
  3. NetCredit
  4. Rent-A-Center
  5. Roadrunner Financial
  6. Best Egg

Our Methodology for Reviewing Arkansas Lenders

When weighing various lenders across the Natural State, we applied a rigorous set of benchmarks tailored specifically to local needs. We primarily scrutinized the impact on your credit rating during the application process. It is vital that checking an rate doesn’t inadvertently sink your score further.

Timing is everything when you are staring down an unexpected emergency. A sluggish provider can leave you stranded when a sudden car repair or a medical bill lands on your desk. If an electric company threatens to cut your power, waiting a full week for a wire transfer is simply not an option.

Consequently, we prioritized services that can move money into your account with incredible velocity. We wanted to see which companies could bridge that gap between a crisis and a solution. Speed acts as the lifeline for many families navigating tight monthly budgets.

We also scrutinized the breadth of loan amounts and the terms for paying them back. Small micro-loans are fine for a grocery run, but they won’t fix a blown transmission costing $3,000. We looked for lenders that offer enough runway to actually solve a problem rather than just masking it.

Flexibility is the name of the game for those working with less-than-ideal credit scores. Our selection process focused on ensuring a wide spectrum of options was available. Whether you need a mere $500 for a quick fix or a substantial $50,000 to roll your debts into one, we have you covered.

Ultimately, we weren’t interested in a collection of names that merely look impressive in marketing brochures. We wanted tools that actually deliver when the pressure is on. Every firm on this list was thoroughly tested to ensure their real-world performance matches their sales pitch.

Provider Maximum Borrowing Transfer Velocity Credit Status
FastLendGo See site See site Bad/Fair/Good
Balance Credit $4,000 Next business day Inclusive consideration
NetCredit $10,000 Same-day available See site
Rent-A-Center See site See site No credit needed
Roadrunner Financial See site Real-time decision All credit welcome
Best Egg $50,000 See site See site

Top-Rated Lending Options for Arkansas Residents

1. FastLendGo

FastLendGo – fastlendgo.com

When life throws a curveball, such as a sudden car breakdown or an unexpected trip to the dentist, you need cash fast. FastLendGo specializes in providing quick liquidity for these exact moments. It is an excellent tool for those who prefer to survey local options without getting bogged down in endless paperwork.

They understand that financial emergencies don’t pause for a weekend or a holiday. Because of this, their streamlined process is built for speed. Whether you are looking for a modest $500 to cover a quick necessity or something larger for a major life shift, they offer various levels of assistance.

This provider is a lifesaver for individuals who might find traditional banking doors closed due to a thin credit history. They sit in that helpful middle ground, bridging the gap between restrictive banks and high-interest payday lenders.

Pros:

  • Rapid access to multiple loan tiers
  • Tailored for specific costs like roofing or dental work
  • Straightforward online comparison tools

Cons:

  • The website layout can be somewhat tricky to navigate

2. Balance Credit

Balance Credit – balancecredit.com

Think of Balance Credit as a financial companion during your leanest months. Sometimes, life just demands an extra cushion, like a security deposit for a new apartment or an unexpected jump in your utility bill. Their primary goal is keeping things simple and stress-free for the borrower.

They avoid the typical headaches of confusing legal jargon and mountains of paperwork. Instead, they focus on a smooth experience that gets you the funds you need to keep moving forward without the extra baggage.

One of their most attractive features is the ability to pay off your debt early without being hit with penalties. If a bonus or a tax refund lands in your lap, you can slash your principal immediately. It is a win-win for anyone trying to be smart with their money.

Pros:

  • No extra costs for early repayment
  • Funds often arrive by the following business day
  • Checking eligibility won’t hurt your credit score

Cons:

  • Borrowing is limited to a maximum of $4,000

3. NetCredit

NetCredit – netcredit.com

NetCredit operates under the belief that a person is far more than just a cold set of numbers. Rather than looking strictly at a single score, they utilize advanced algorithms to view your overall financial landscape. This nuanced approach can be a total game-changer for someone with a minor credit hiccup.

For instance, a single late payment from a year ago shouldn’t define your entire future. If your income is stable, they take that into account. This holistic perspective helps many people find the breathing room they desperately need.

With loan ceilings reaching up to $10,000, they offer much more substantial support than many other quick-cash outfits. This is perfect for anyone looking to roll multiple high-interest credit card balances into one single, manageable monthly payment. It is a great way to simplify your life.

You can test the waters by checking your eligibility without risking a hit to your FICO score. This low-risk exploration lets you see what you qualify for without any guesswork or commitment.

Pros:

  • Generous borrowing limits up to $10,000
  • Option for same-day funding
  • A more comprehensive review of your financial health

Cons:

  • Specific terms depend heavily on the underwriting process

4. Rent-A-Center

Rent-A-Center – rentacenter.com

Rent-A-Center takes a completely different path by leaning into the rent-to-own philosophy. Rather than handing you a pile of cash, they provide the actual items you need through a lease-to-own setup. This is a fantastic way to furnish a new home immediately when cash is tight.

If you need a new sofa, a refrigerator, or a television, this model works wonders. It is a “no credit needed” alternative that bypasses the traditional banking hurdles. It is perfect for anyone who wants to avoid the stress of a hard credit inquiry.

This approach is a lifesaver for managing short-term cash flow gaps. If your washing machine dies on a Tuesday, you can get a replacement running without needing a bank’s blessing or a perfect credit history.

Pros:

  • Many household items require no credit check
  • Very low initial costs to get started
  • Massive selection of essential home goods

Cons:

  • The cumulative cost can be higher due to the rental structure

5. Roadrunner Financial

Roadrunner Financial – roadrunnerfinancial.com

Roadrunner Financial is a niche player designed specifically for those who love powersports. Whether you are hunting for a new motorcycle, an ATV, or even a golf cart, they have a dedicated lane for you. They cut through the noise of standard dealership haggling and long waiting lists.

They provide a rapid pre-qualification process that delivers a real-time decision. This is incredibly helpful if you find a killer deal at a local shop in Fort Smith or Fayetteville and need to pull the trigger quickly. It allows you to walk onto a lot with total confidence.

Because they understand the seasonal nature of riding, they offer a service that feels personalized. They don’t waste time on generalities; they focus on the specific needs of the powersports community.

Pros:

  • Tailored specifically for powersports enthusiasts
  • Instant decisions that don’t impact your credit
  • Rates remain valid for a 30-day window

Cons:

  • Very specialized; not meant for general personal expenses

6. Best Egg

Best Egg – bestegg.com

Best Egg is a heavyweight in the personal loan arena, particularly when it comes to larger sums for debt consolidation. If you are tired of juggling multiple high-interest payments and want to merge them into one predictable monthly chunk, they are a top-tier choice.

They utilize modern technology to keep the user experience smooth and intuitive. Instead of getting lost in a labyrinth of menus, you can focus on what matters. Their fixed interest rates offer a level of stability that variable-rate loans simply cannot match.

For those who can provide a bit of collateral, such as home fixtures, they might even offer even lower rates. This is a premium solution for anyone looking to move out of “survival mode” and start focusing on long-term financial stability.

Pros:

  • High borrowing capacity up to $50,000
  • Fixed rates allow for easy budgeting
  • Strong reputation with great BBB ratings

Cons:

  • The best rates are often reserved for those with higher credit scores

Mastering the Art of Comparing Loan Conditions

Do not just glance at the fine print and sign your name away. Before any contract is inked, you must distinguish between the “Interest Rate” and the “APR.” While the interest rate merely reflects the cost of the borrowed principal, the APR tells the real story by factoring in extra expenses like processing or origination fees.

Think of the interest rate as just one piece of the puzzle. If you want to see the genuine price of your debt, always prioritize the APR when weighing different lenders against one another. It is the most honest metric for your wallet.

Follow these three essential steps to ensure you aren’t walking into a financial trap:

  1. Determine the Full Cost of Borrowing: Grab a calculator and perform a simple bit of math. Multiply your monthly installment by the total length of the repayment term. Once you subtract the original principal from that sum, the remaining number represents the true weight of your interest and various service fees.
  2. Investigate Early Payoff Fees: It is a bit like a trap if you aren’t careful. Just as we observed with Balance Credit, certain lenders might penalize you if you attempt to settle the debt ahead of schedule. Aim for companies that permit early settlement without slapping any unexpected surcharges on your account.
  3. Assess Your Monthly Cash Flow: Take a hard look at your current lifestyle and spending habits. You must ask yourself if this new installment fits smoothly into your budget. A payment that leaves you with absolutely no breathing room could be dangerous if life throws a sudden curveball your way.

Staying Sharp While Borrowing in Arkansas

Steering through the world of high-interest lending in the Natural State demands a watchful eye. It is a mistake to assume the smallest interest rate displayed on a website is the best deal. You really have to dig into the actual contract to ensure no traps are lurking in the shadows.

Always hunt for those sneaky surcharges, such as late fines or origination charges. These little details can cause your total debt to skyrocket without you even realizing it. It’s like a leak in a bucket; you might not notice it immediately, but eventually, the water is gone.

Consider a scenario where you secure a $1,000 loan. If the lender charges a $100 origination fee, you only see $900 hit your bank account. However, the interest you owe is calculated based on the full $1,000 amount. This is a critical distinction for any borrower to grasp.

It is vital to avoid the trap of signing for a loan that exceeds your budget. This sounds like common sense, but when life throws a curveball, it’s easy to ignore future monthly costs. Focus on the long game rather than just the immediate relief.

Think of a loan as a hammer meant to fix a house, not a tool to tear it down. If you are using credit to consolidate existing debts, ensure the new interest rate is much lower than your old ones. Shuffling money between cards without lowering rates is just spinning your wheels.

Lastly, always calculate the full price of the credit. A company might promise small monthly payments to lure you in. However, if the repayment period stretches to three years, you might pay back twice the original amount. Take a moment to breathe and choose what truly fits your lifestyle.

Best Personal Loans for Low Income Individuals to Apply for Today

By Uncategorized
Personal loans for low income individuals

Best Personal Loans for Low Income Individuals to Apply for Today

Last updated: 2026-10-16

Struggling to keep your head above water when every cent is spoken for is a heavy weight to carry. It feels like you are treading water in a storm, just trying to stay afloat. You might find yourself staring at an endless pile of invoices, searching for a helping hand that doesn’t demand a spotless credit history. This anxiety can be overwhelming.

Life has a knack for throwing curveballs exactly when you think you have things under control. One minute you are managing, and the next, an unexpected repair or a sudden doctor’s bill has turned your world upside down. Whether it is a broken car part or a spike in your heating bill, these surprises can wreck a budget in an instant.

When you are looking for a way out, ignore the shiny advertisements that promise the moon. Instead, you must dig into the gritty details of how quickly you get your funds and what the actual interest costs look like over the life of the loan. It is vital to know if looking for a quote will damage your credit rating.

The thin line between a useful financial lifeline and a crushing weight often depends on the Annual Percentage Rate (APR) and the specifics of your repayment schedule. Navigating these numbers is crucial for your long-term stability. Don’t let the marketing fluff distract you from what really matters: the actual cost of the money you borrow.

We have curated this selection to highlight lenders that actually look at people who are typically ignored by the major banking institutions. Our list covers a wide variety of financial needs. Some of these choices provide quick cash for emergencies, while others are designed to help you consolidate various debts into one manageable payment.

  1. JetzLoan
  2. Best Egg
  3. Avant
  4. OneMain Financial
  5. OppLoans

Our Vetting Standards

When we sat down to sort through these providers, our primary goal was to protect the person on the other side of the screen. We didn’t want to just list names; we wanted to see how these firms treat people facing a tight squeeze. It is a heavy responsibility to recommend financial help to those who need it most.

We dug deep into the ease of use for every platform. Speed is everything when the rent is due or a car needs fixing. We specifically hunted for services that offer lightning-fast determinations so you aren’t left hanging in uncertainty.

A major part of our investigation involved finding lenders that won’t ding your score just for checking your eligibility. There is nothing worse than getting a cold, automated rejection without any human interaction. We sought out companies that offer genuine clarity and real support.

Transparency shouldn’t be a rare find in the lending world; it should be the baseline. We scrutinized their fee breakdowns to ensure there were no hidden landmines waiting to trip you up. If a company hides its costs, it doesn’t pass our test.

We also weighed how different companies react to diverse credit histories. A one-size-fits-all approach rarely works for folks living on the edge. We needed to ensure these options were actually functional for a broad spectrum of financial backgrounds.
Timing is the heartbeat of our selection process. For anyone dancing from one paycheck to the next, a two-week wait is basically a lifetime. We leaned heavily toward providers capable of delivering cash within the same business day or within a twenty-four-hour window.

After all, financial aid is only useful if it hits your bank account when the emergency is actually happening. We prioritize those who treat your time with respect. Slow money often solves none of the problems it was intended to fix.

Finally, we looked closely at the “soft inquiry” mechanism. This clever feature lets you hunt for better deals without the sting of a hard credit inquiry. It is a vital tool for anyone trying to safeguard their credit standing while shopping around.

Company Borrowing Limits Delivery Timeframe Impact on Credit
JetzLoan $500 – $35,000 Minimum 24 hours No hard credit pull
Best Egg Up to $50,000 See site See site
Avant See site See site See site
OneMain Financial $1,500 – $30,000 As little as 1 hour No credit score impact
OppLoans See site Same-day funding available Does not affect FICO score

Leading Lenders Offering Accessible Credit Options

1. JetzLoan

JetzLoan – jetzloan.com

When time is of the essence, JetzLoan serves as a bridge between borrowers and a wide array of premier lenders. The system is engineered for lightning-fast simplicity. This makes it a top-tier remedy for anyone looking to roll multiple debts into one or cover a sudden vehicle expense. The entire path is smoothed out to ensure you aren’t drowning in paperwork.

They embrace a digital-first philosophy, which is a godsend for folks who cannot wait for the slow gears of traditional banking to turn. Because they offer a way to check your rates without a hard credit pull, the fear of a damaged score vanishes. This “pre-qualification” stage is a total game-changer for savvy shoppers. It lets you eye potential interest rates and terms before diving into a formal application.

In a crowded marketplace, this company has carved out a reputation for being a rock-solid partner. Boasting a 4.7-star rating and a history of funding over 500,000 loans, they truly know the ropes. It is a dependable route if you need to see your hard numbers before making a major financial leap.

Pros:

  • Checking rates won’t impact your credit score
  • Funds can arrive in as little as 24 hours
  • Borrow up to $35,000

Cons:

  • Loan amounts top out at $35,000

2. Best Egg

Best Egg – bestegg.com

Best Egg acts as a heavy hitter in the personal loan arena. They are widely recognized for assisting individuals in tackling high-interest debt. Their primary mission is to simplify your financial life by streamlining your monthly obligations. Imagine taking a messy pile of medical debts or various credit card balances and turning them into a single, manageable payment. By consolidating, you can often snag a lower interest rate than your current cards allow.

This strategy can pave a clear road toward becoming debt-free while saving you serious cash over time. They have earned deep consumer trust, backed by an A+ rating from the Better Business Bureau and a mountain of positive testimonials. For those who own homes, there might be extra ways to lower rates by using assets like vanities or cabinets as collateral. However, the majority of clients stick to their standard unsecured loans.

This is a more methodical way to manage your money. It is perfect for individuals seeking a long-term strategy rather than just a temporary band-aid. If your goal is to get your finances organized and stay that way, this might be your best bet.

Pros:

  • High borrowing ceilings reaching $50,000
  • Outstanding BBB rating
  • Potential savings for homeowners

Cons:

  • The application process requires more detailed info

3. Avant

Avant – avant.com

Avant operates on the belief that no two financial stories are exactly the same. They provide a toolkit of solutions, ranging from installment loans to credit cards. Their mission is to provide the wind in your sails as you move forward. Whether you are facing a sudden emergency or renovating your living space, they aim to offer choices that actually fit your unique lifestyle.

Unlike the rigid, robotic scoring used by many big banks, Avant takes a wider view of your overall financial health. They want to be a partner in your journey rather than just a lender. This provides a flexible cushion for people who might struggle with traditional banking hurdles. It is a versatile pick for those needing a specific tool, like debt consolidation, rather than a generic, one-size-fits-all product.

The platform is built for anyone seeking straight answers to tough financial questions. Their streamlined digital interface cuts through the thicket of paperwork usually found with personal loans. It is designed for the modern borrower who wants clarity and speed rather than endless, tedious forms.

Pros:

  • A variety of credit card and loan options
  • Tailored for different stages of life
  • A philosophy of financial progress

Cons:

  • Specific qualification rules aren’t always crystal clear

4. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial is a premier choice for those who crave a human connection. With a massive network of over 1,300 branches, you can actually sit down and talk to a real person. This can be a total lifesaver when you are staring at confusing terms or dealing with a nuanced situation that a computer might miss. Having a physical storefront provides a sense of security for people who prefer face-to-face business.

Their speed is nothing short of impressive. You could potentially see your money just an hour after you sign the papers. They provide loans between $1,500 and $30,000 with the benefit of fixed monthly payments. This predictability is vital for families living on a tight budget, as it makes your monthly planning much easier.

It is a fantastic option if you need cash almost immediately to handle an urgent matter. If a car repair or a home maintenance issue pops up out of nowhere, having a local branch to visit can offer immense peace of mind. You can walk through the door, talk through your options, and get things moving quickly.

Pros:

  • Huge network of physical branches for help
  • Extremely rapid funding after signing
  • Fixed payments lasting 24 to 60 months

Cons:

  • Interest rates can fluctuate wildly

5. OppLoans

OppLoans – opploans.com

OppLoans is built on the principle that your credit score is not the whole story. Their lending partners look far beyond that single, lonely number. They take into account your income stability and your employment history instead. This makes them a viable lifeline for people who have faced a recent credit dip due to unexpected life events.

If life throws you a curveball like a medical emergency or a stint of unemployment, they may still be willing to work with you. It is a practical way to find relief without getting tangled in complicated fine print or hidden fees. The application is incredibly fast, and you often receive a decision within minutes. If approved, the cash might hit your account the very same business day.

This makes them a high-speed solution for emergencies where every second counts. Whether you are trying to keep the lights on or cover an immediate cost of living gap, they offer quick relief. Their commitment to fee transparency ensures you won’t be blindsided by the total cost of your loan.

Pros:

  • Possibility of same-day funding
  • Applying does not impact your FICO score
  • Total lack of hidden fees

Cons:

  • Might not be the best fit for long-term debt

Calculating Your Real Debt Burden

When life throws a curveball and money is tight, our eyes tend to fixate on the immediate cash availability. We often gloss over the interest percentage in our hurry to get things sorted. Yet, that tiny number carries the weight of your entire financial future. It is the heartbeat of your agreement.

It is vital to separate the base interest rate from the Annual Percentage Rate, or APR. While the interest rate is just the cost of the money itself, the APR tells the whole story. This figure absorbs everything, including pesky administrative charges or mandatory processing costs. Think of it as the true price tag.

Let’s say you need a $2,000 loan and see a 10% interest rate. If the lender sneaks in a $300 origination fee, your APR will jump much higher than that initial 10% suggests. Always look past the surface. The fine print is where the real costs like to hide from unsuspecting borrowers.

The Math Behind the Money

Before you put pen to paper, run a quick “monthly impact test” to see how this affects your wallet. This little mental exercise acts as a safety net. Take your scheduled monthly installment and multiply that amount by the total number of months in your repayment period.

Next, take that final sum and subtract the original principal you actually received. This simple subtraction reveals the true price of your convenience in cold, hard cash. It transforms abstract percentages into a real number that fits into your grocery or rent budget.

If a $2,000 emergency repair ends up costing you $600 in interest over time, you need to stop and think. Ask yourself if your monthly paycheck can handle that extra dent without breaking. Avoid the dreaded “debt trap” where you’re essentially running on a treadmill just to stay in place.

If you spend your whole paycheck just covering interest, you’re never actually paying down what you owe. You’ll find yourself spinning your wheels while the debt stays stubbornly high. Staying ahead of these calculations ensures you stay in control of your finances rather than the lender.

Navigating Potential Financial Traps

It is incredibly easy to let greed or desperation drive a wedge between your current reality and your future stability. Many people find themselves reaching for the highest ceiling a lender offers, even when their actual need is quite modest. For example, you might find yourself signing for $5,000 when a $3,500 loan would have solved your problem perfectly fine.

This extra cash might feel like a windfall at first, but it carries a hidden sting. Every additional dollar you borrow increases the weight of your monthly installment. If your paycheck varies from week to week, these higher costs can quickly turn into an anchor that drags you under a mountain of interest.

Before you sign any paperwork, try to cultivate a little breathing room in your existing monthly spending plan. Life rarely goes according to script; a sudden car repair or a spike in utility costs can throw everything off balance. You never want to find yourself choosing between servicing a debt and keeping the lights on.

Managing Credit Inquiries and Debt Cycles

Understanding how lenders peek at your financial history is vital to maintaining a healthy profile. Most companies allow you to shop around using a “soft pull,” which is a gentle way to gauge your interest rates without causing any damage to your standing. It is like window shopping at a boutique without actually taking anything to the register.

However, once you decide to move forward and officially accept the funds, the lender will perform a “hard inquiry.” This is a formal interrogation of your credit history that can cause your score to take a temporary tumble. Think of it as a commitment; make sure you are truly comfortable with the fine print before you cross that line.

Furthermore, steer clear of the dangerous habit of “rolling over” your short-term obligations into fresh, new loans. This maneuver is a classic trap that turns tiny, manageable debts into massive, crushing financial burdens. It creates a deceptive sense of stability that masks a much larger problem.

It might feel like you are simply treading water during a storm, but you are actually sinking just at a slower pace. Instead of moving forward, you are merely paying for the privilege of staying in the same precarious position. True financial freedom requires facing the debt, not just rescheduling it indefinitely.

Score the Best Furniture Financing Deals Today

By Uncategorized
Furniture financing

Score the Best Furniture Financing Deals Today

Last updated: 2026-10-16

Most people have experienced that sudden rush of excitement when a luxurious velvet sofa catches their eye in a showroom. It is a beautiful sensation, but the reality often sets in when you spot the total cost. This is where payment plans step in to save the day.

Rather than paying everything upfront, you can split the bill across many months or even several years. This method allows you to enjoy your new home comforts immediately. It turns a massive one-time hit to your wallet into a manageable series of smaller bites.

Managing a modern household requires some flexibility with your cash flow. Think about the stress of moving into a fresh apartment or the urgent need to replace an old dining table. You shouldn’t have to endure a bad night’s sleep because you’re waiting on a savings account.

Sometimes, you just need a quality mattress right now. Spreading out your expenses ensures that your lifestyle doesn’t have to wait for every penny to accumulate. It bridges the gap between your immediate needs and your long-term financial goals.

Selecting a lender is about much more than just checking the monthly installment amount. You really need to dive deep into the interest rates and the tricky fine print. Many people forget that your credit score might dictate which doors are open to you.

Be careful, because high interest can make your furniture much more expensive than the sticker price suggests. For instance, that $1,000 sofa could end up costing you $2,000 by the time your last payment is made. It’s a heavy price to pay for convenience.

Don’t let a pretty showroom floor distract you from the cold, hard math of your potential debt. It is vital to look at the actual cost of borrowing before you sign anything. You need to weigh the visual appeal against the long-term financial impact.

This guide breaks down the leading choices for financing your home decor. Whether you are hunting for a quick promotional deal or a lengthy repayment structure, understanding your paths is the best way to decorate without regret.

  1. Furniture Row
  2. FastLendGo
  3. Jordan's
  4. Rent-A-Center
  5. CashUSA

Our Methodology for Assessing Finance Providers

Shopping for a new sofa is one thing, but navigating the maze of monthly payments is a different beast entirely. When we vetted these companies, we looked well past the showroom floor. It isn’t just about the stitching on a recliner; it is about the fine print in your contract.

We prioritized examining the fluidity of repayment terms and the ease of the initial signup. It is easy to fall head over heels for a “0% interest” headline. Nevertheless, these enticing deals often act as a gilded cage, requiring a spotless credit profile to unlock the gate.

Many programs that promise interest-free periods if the balance is cleared in full demand a stellar FICO rating. Financial institutions want a paper trail of steady earnings to mitigate their own danger. They aren’t just handing out money; they are measuring your reliability against their risk.

We also scrutinized the turnaround time for receiving your funds. Some firms cater to the credit-savvy, providing the most competitive APRs for those with deep history. Meanwhile, other lenders act as a lifeline for folks working to rebuild after a financial stumble.

Balancing the lightning-fast approval speeds against the ultimate price tag was our main goal. This approach gives every shopper a realistic view of their financial landscape. We measured every provider against these core benchmarks:

  • Turnaround Time: The actual duration between hitting the submit button and having funds ready for checkout.
  • Clarity: Whether a company is upfront about all costs, such as late fees or hidden origination charges.
  • Payment Versatility: The ability to settle the debt ahead of schedule without incurring extra penalties.
  • Eligibility Thresholds: Whether there is a strict credit floor or if those with thin files can still qualify.
Provider Maximum Funding Rate Varieties Qualification Criteria
Furniture Row check their website 0% APR is possible Contingent upon verification
FastLendGo $5,000 check their website Poor, Average, or Decent
Jordan’s check their website 0% APR for a 2-year term Contingent upon verification
Rent-A-Center check their website Lease-to-own models No credit history required
CashUSA $10,000 check their website check their website

Leading Choices for Financing Home Decor

1. Furniture Row

Furniture Row – furniturerow.com

For shoppers seeking a blend of premium merchandise and customized payment plans, Furniture Row stands out. By teaming up with numerous lenders, they provide a diverse array of deals. This ensures that every customer can locate a financial arrangement that aligns with their unique monthly budget and lifestyle.

The allure of interest-free windows is hard to ignore. If you qualify for a 0% interest deal, you dodge those pesky extra costs. Take a $3,000 couch, for example. Spreading that cost over 12 months at 0% means a $250 monthly payment. However, with a standard 18% APR loan, that same piece of furniture could end up costing you almost $3,500 total.

This approach makes luxury pieces feel within reach for most households. You just need to ensure your monthly budget can handle the installments. It is a savvy method to secure high-end goods without draining your savings in one single, massive transaction.

Pros:

  • Availability of special 0% interest deals.
  • Vast inventory of bedroom, dining, and living room pieces.
  • Choices to shop online or visit in-person showrooms.

Cons:

  • Specific promotional deals depend on credit approval.
  • Missing a deadline may trigger “retroactive interest,” applying charges back to the original purchase date.

2. FastLendGo

FastLendGo – fastlendgo.com

If you need immediate liquidity for various projects, FastLendGo is a reliable ally. While they serve many purposes beyond decor, their personal loan setup is perfect for outfitting an entire living space. Unlike credit tied to one shop, a loan from FastLendGo grants you total autonomy. You can browse various retailers to hunt for the best deals.

This service shines when your credit history is less than perfect. By catering to good, fair, and even bad credit, they open paths that traditional banks often shut tight. It is a digital-first, modern solution that lets you weigh different options without the hassle of traveling to physical bank branches.

This is a lifesaver if you are rushing to furnish a new rental. You receive a lump sum of cash and can shop anywhere. It breaks the chains of being restricted to the stock of one particular furniture store.

Pros:

  • Accommodates a wide variety of credit scores.
  • Loan amounts ranging from $500 to $5,000.
  • Quick digital application process.

Cons:

  • Focuses on personal loans rather than direct store-specific credit.
  • Repayment windows might be shorter than specialized furniture installments.

3. Jordan’s

Jordan's – jordansfurniture.com

Jordan’s Furniture is a heavyweight in the industry, famous for its expansive showroom. They provide sophisticated financial setups that make expensive items feel quite manageable. Their deals frequently include extras like complimentary “white glove” delivery, which saves you both significant manual labor and mental stress.

With white glove service, workers bring items inside, handle the assembly, and clear out all the cardboard and plastic. When you combine this with their 24-month 0% APR offer, the value is incredible. It allows you to revamp your bedroom or lounge without that immediate, painful hit to your wallet.

It is a smart move for anyone with a steady paycheck who wants to keep their cash liquid for emergencies or rent. Think of this interest-free period as a short-term bridge. It keeps your money working in your savings account while you enjoy your new home comforts.

Pros:

  • Promotional 0% APR available for 24 months.
  • Access to white glove delivery services.
  • Massive selection across categories like outdoor, gaming, and more.

Cons:

  • Special rates require credit approval.
  • High-priced items can lead to significant debt if you aren’t careful.

4. Rent-A-Center

Rent-A-Center – rentacenter.com

For those looking to bypass the standard credit system entirely, Rent-A-Center is the answer. Their business model is centered on extreme flexibility. You can grab necessary household items today without needing a formal credit check or a long-term commitment. Essentially, you are entering a lease-to-own arrangement.

You pay for the ability to use the product, with the option to eventually own it after a certain number of installments. This is a vital resource for people in transition. Students or seasonal workers often find this model incredibly helpful. You can start with a small down payment and then upgrade as your circumstances change.

Suppose you start with a simple coffee table. Once you have made a few successful payments, you could trade it in for a larger entertainment center. It offers a level of freedom that standard loans lack. You aren’t stuck with one piece of furniture for the duration of the contract.

Pros:

  • No credit history needed to start.
  • Significant flexibility to change or upgrade plans.
  • Very low initial costs to begin renting.

Cons:

  • Lease-to-own options can become more costly over time.
  • If you fail to finish the term, you never own the goods and have only paid for temporary use.

5. CashUSA

CashUSA – cashusa.com

CashUSA functions as a digital matchmaker. They assist users in finding personal loans tailored to specific needs. If a room remodel requires up to $10,000, this service can guide you toward a suitable lender. It is a modern, efficient way to shop for credit, much like a comparison engine for your bank account.

The journey is designed to be effortless. Typically, it follows a four-step path: apply, compare, select, and receive funds. While they might offer debt relief if a loan isn’t a match, their main goal is making connections. This is perfect for tech-savvy people who want to see many options on one screen.

You can avoid spending hours on hold with different banks. Instead, you get a fast, digital experience. This saves precious time when you need to make major household changes on an accelerated timeline.

Pros:

  • Access to potential loans up to $10,000.
  • Rapid connection to various lenders.
  • Simple, user-friendly online application.

Cons:

  • You might receive marketing offers rather than actual loans if no match is found.

Vital Inquiries for Your Loan Agreement

Before pulling the trigger on a new payment schedule, you must put your wallet through a trial by fire. It is easy to get swept up in the allure of a low monthly installment. A mere $50 every month feels like a walk in the park to most shoppers.

However, time is a thief that works slowly. If that small payment spans a 60-month term, you are essentially tethered to that furniture for half a decade. That is a long time to be thinking about a couch or a dining set.

When interest rates climb, you might find yourself paying for the same piece of wood and fabric twice. Do not let the fine print blindside you. Use these specific prompts when sitting down with a dealer or a credit representative.

These questions act as a shield against unexpected financial headaches down the road. Keep this list handy as you navigate the high-pressure environment of a showroom floor. It is better to be cautious now than broke later.

  1. “What is the final sum of this purchase once all interest and extra fees are added?” This specific figure represents the most critical data point in your entire deal.
  2. “Will I be charged a penalty if I pay the balance early?” Suppose a surprise bonus lands in your bank account and you decide to settle your sofa debt by month six. You should be able to clear the debt without facing extra costs.
  3. “What are the consequences of being even one day late with a payment?” Certain agreements contain brutal “default” rules. In these cases, you could lose your 0% interest perks and face immediate, backdated interest charges.
  4. “Do you charge any service fees or origination costs?” Lenders sometimes sneak in a $100 “processing fee” at the start. This amount is rarely factored into the monthly price they show you in advertisements.

Selecting the Ideal Financing Option

Before you ink any contracts, scrutinize the full price tag of your commitment. It is incredibly easy to get lured in by a tiny monthly installment that masks a decade-long financial burden. You should constantly ask yourself how much the entire purchase will actually cost when the final payment is made. This calculation peels back the curtain on what you are truly paying.

Don’t let the thrill of a gorgeous new dining set cloud your judgment regarding your monthly cash flow. It is vital to avoid accumulating more debt than your budget can comfortably swallow. Think of your financial health as the bedrock of your domestic peace. If you opt for rent-to-own arrangements, keep in mind that you are paying a premium for the sheer luxury of flexibility.

Treat rent-to-own schemes as a convenience-based service rather than a permanent solution. In contrast, personal loans or store credit accounts function as instruments for building equity and gaining true ownership. You must also investigate the interest rates very carefully. Should you snag a 0% APR promotion, be wary of the heavy penalties for tardiness. A solitary late payment could cause your interest rates to skyrocket overnight.

Maintaining a sharp eye on your schedule is your best defense against unexpected headaches. I always suggest marking every due date on a physical calendar or your digital phone alerts. Setting up automatic payments is a brilliant way to ensure you never miss a beat. By staying ahead of the curve, you can relax in your stylish new living room without that nagging shadow of debt.

Best Ways to Secure Land Loans for Bad Credit Online

By Uncategorized
Land loans for bad credit

Best Ways to Secure Land Loans for Bad Credit Online

Last updated: 2026-10-17

Locating the perfect plot of earth is frequently a breeze compared to securing the capital required to purchase it. Many folks chasing the dream of a tranquil wooded area or a rural sanctuary find their aspirations hitting a brick wall. Often, a bruised credit history stands in the way of those eager to settle down.

Big-name banks typically turn a blind eye when your score falls below specific thresholds. They might insist on upfront costs ranging from 20% to 30% of the total price. For most people buying their first piece of property, that amount of cash simply isn’t sitting in a bank account waiting to be spent.

From the perspective of a traditional lender, undeveloped ground is a gamble. Unlike a house, a vacant lot lacks a building to act as security if you can’t pay the debt back. This reality turns the quest for financing into quite an uphill battle for the average seeker.

You essentially need to hunt for specialists who prioritize the worth of the terrain. These lenders care more about the potential of the soil than the numbers printed on a credit report. It takes a bit of luck and persistence to find someone willing to take that specific leap of faith.

This guide highlights several routes through those daunting economic obstacles. Whether your heart is set on a tiny garden, a weekend getaway, or a sprawling farm, knowing your choices is vital. You must also learn the distinction between “finished lot” sites with utilities and “raw land” that lacks any infrastructure.

Getting these details straight is the best way to find the right money source. Understanding what you are actually buying will help you navigate the complex landscape of property financing. Take a look at these top contenders for your next big investment.

  1. Acorn Finance
  2. JetzLoan
  3. LightStream
  4. Country Bank
  5. Lendersa
  6. USDA

Our Methodology for Comparing Financing Choices

When we sat down to vet these options, our main goal was determining who would actually answer the door for various credit scores. It is a bit like shopping for shoes; not every brand is designed for every foot. You must grasp the massive chasm between a simple personal loan, a high-interest hard money setup, and federal assistance schemes.

Choosing a provider for a quick cash boost is a different beast than seeking a permanent mortgage. While a personal loan acts like a sprint, offering rapid capital, you will likely pay a premium through elevated interest rates compared to a standard mortgage tied to the land itself.

On the flip side, conventional bank financing can be a slow turtle, often taking up to 45 days to reach the finish line. In that agonizing wait, your ideal plot of dirt might slip through your fingers to a more aggressive buyer. We also weighed the velocity of capital against the fallout of credit inquiries.
Some firms permit you to scout rates through a “soft pull,” which leaves no scar on your score. This is a total lifesaver when you are trying to gauge your financial reach before making a serious move. We kept our eyes glued to transparency throughout this entire investigative journey.

Our team scrutinized how fast money hits your account and how many hoops you must jump through during the paperwork phase. We dug into the specific collateral demanded for each transaction. Understanding whether an inquiry is a “hard pull” or a mere “soft” informational glance can make or break your monthly budget.

Provider Maximum Limit Payout Velocity Score Criteria Primary Use Case
Acorn Finance Check website Check website Fair to Poor Scores Renovations/Contracting
JetzLoan $50,000 Within 1 day Soft Inquiry Only Rapid Liquidity/Debt Management
LightStream $100,000 Check website Prime to Superb Premier Credit Profiles
Country Bank Check website 60 Day Fixed Rate Based on Review Unimproved Lots/Acreage
Lendersa Check website Quick Turnaround Variable (Private Capital) Property Flippers/Real Estate Pros
USDA Check website Check website Variable Countryside Living/Residences

Top Rated Land Financing Providers

1. Acorn Finance

Acorn Finance – acornfinance.com

Think of Acorn Finance as a specialized intermediary that connects you to a vast network of financing sources. One of their standout features is the complete absence of dealer fees, which helps you avoid those sneaky costs that often inflate total debt. It is a refreshing change in a market where service charges can unexpectedly drive up your costs.

This service is a perfect match if you are looking to buy acreage and immediately start working on it. If you need to clear brush or lay down a new driveway right away, this flexibility is gold. They bridge the gap between acquiring the dirt and making it habitable.

For those struggling with less-than-perfect credit history, this provider is a lifeline. Unlike big banks that might turn you away based on a single score, Acorn Finance links you with specialists who look at the bigger picture. This increases your chances of finding a lender who says “yes” even when your FICO might say “no.”

It is a smart, versatile choice for modern property seekers. Instead of hitting a brick wall of rejections, you are being matched with people who understand your unique financial journey. It is all about finding a partner that works for your specific situation.

Pros:
  • $0 dealer fees for contractors and borrowers
  • Personalized rates with no credit score impact during checking
  • High customer satisfaction with 4.3 stars on Trustpilot
Cons:
  • May not offer the lowest rates compared to prime lenders

2. JetzLoan

JetzLoan – jetzloan.com

When a real estate deal moves at lightning speed, JetzLoan is often the first call to make. They have the incredible ability to get cash into your hands in as little as 24 hours. This makes them a vital tool for urgent acquisitions or when you need to consolidate debts quickly.

In a hot market, having cash on hand is like having a golden ticket. Sellers often favor “cash offers” because they skip the long, drawn-out inspections and appraisals that traditional banks require. This speed can be the deciding factor in winning a property auction or a competitive bidding war.

The application itself is a breeze, taking roughly two minutes to finish. This is ideal for the shopper who spots a perfect lot on a weekend and needs to prove they are a serious buyer immediately. You can explore your options without the fear of damaging your credit score.

By allowing you to check rates without a hard credit pull, they protect your financial standing while you shop. It is a high-octane solution for anyone living in a fast-moving real estate landscape. If you need to act now, this is your best bet.

Pros:
  • Funding in as little as 24 hours
  • No hard credit pull to check rates
  • High loan limits up to $50,000
Cons:
  • Limited to personal loan structures rather than traditional land mortgages

3. LightStream

LightStream – lightstream.com

LightStream operates on an entirely different level than the others. This is the premier choice for individuals who have successfully navigated their way to a high credit standing. They offer incredibly competitive, fixed interest rates that are hard to find elsewhere if your profile is excellent.

If you crave stability, this is the place to be. You can lock in your interest rate and know exactly what your monthly obligations look like for the entire life of the loan. It takes the guesswork out of your long-term financial planning, providing peace of mind.

With loan amounts reaching up to $100,000, you have plenty of capital for large land purchases or even subdividing a massive plot. However, if your credit is currently in the “bad” category, you will likely find these doors firmly shut. Their automated systems prioritize those with impeccable FICO scores and consistent income.

This is a top-tier destination for those who want to avoid the high costs of subprime financing. If your financial house is in perfect order, LightStream offers one of the smoothest paths to property ownership. It is efficient, predictable, and highly professional.

Pros:
  • Low fixed interest rates
  • Loan amounts up to $100,000
  • Highly reputable through Truist
Cons:
  • Requires good to excellent credit; not for bad credit

4. Country Bank

Country Bank – countrybank.com

Country Bank brings a localized, community-driven spirit to the lending world. As an FDIC-insured institution, they provide a level of security and personal touch that massive national banks often lack. They possess a deep understanding of land that purely digital lenders simply cannot replicate.

While a giant bank might see a lot without paved road access as a high risk, this bank sees the local potential. They understand regional zoning laws and the unique value of specific geographic areas. They look at the land through the eyes of a neighbor, not just a spreadsheet.

A standout perk of their service is the ability to lock in your rate for 60 days. This is a massive advantage when navigating a volatile market. It gives you the breathing room to hire surveyors or architects without worrying about sudden interest rate spikes.

Whether you are looking at raw land or a site ready for construction, they offer customized financing. They recognize that the risks for these two types of property are worlds apart. It is an ideal choice for someone looking to build a long-term banking relationship.

Pros:
  • 60-day rate lock availability
  • FDIC-insured security
  • Offers financing for both raw and buildable land
Cons:
  • Standard bank approval processes can be rigorous

5. Lendersa

Lendersa – lendersa.com

Lendersa is tailor-made for the aggressive investor who refuses to slow down. By utilizing advanced AI, they match borrowers with an extensive network of private investors and hard money lenders. This technology is optimized to ensure the fastest closing times possible for their clients.

This is a high-energy option perfect for real estate pros focusing on land flipping or quick developments. While a traditional bank might spend weeks verifying a survey, the Lendersa network is built for rapid movement. They focus on getting you from “offer” to “closed” in mere days.

If you are hunting for deals at auctions or in fast-paced “fix and flip” scenarios, this is your best ally. In a market where every second counts, they help you beat the competition to the finish line. Their reach covers both commercial and residential properties alike.

It is important to note that these terms often differ significantly from a standard mortgage. While you might pay a premium for this incredible speed, professional investors find the rapid turnaround worth the cost. It is all about how quickly you can cycle your capital.

Pros:
  • Uses AI to match lenders and optimize rates
  • Designed for fast closing and auctions
  • Covers residential and commercial property types
Cons:
  • Hard money terms can be much more expensive than traditional loans

6. USDA

USDA – rd.usda.gov

The USDA serves as a government-supported pillar of support for rural development. Their mission is to fuel the growth of the country’s countryside by providing essential loans and grants. They want to help people build, buy, or mend homes in specific rural stretches of America.

This is a beautiful opportunity for anyone dreaming of a rural lifestyle and a fresh start. These programs are specifically designed to bolster local economies. They help families establish deep roots in areas they might have otherwise been priced out of due to low down payments.
While the paperwork can be a bit more involved and location requirements are strict, the rewards are substantial. This isn’t just a profit-driven enterprise; it is a program designed to serve the people. If you qualify, it is a powerhouse for achieving homeownership.

It is a mission-driven path for homesteaders and families looking for stability. By lowering the barriers to entry in rural areas, the USDA helps keep the heart of the country thriving. If you fit the mold, this is a wonderful way to secure your future.

Pros:
  • Government-backed stability and support
  • Focuses on rural economic development
  • Offers various programs including grants and loans
Cons:
  • Strict geographic requirements for eligibility

Differentiating Between Real Estate and Raw Acreage

Before you dive into the paperwork, you must grasp how banks perceive the difference between a structure and a plot of dirt. Think of it like a safety net. When you secure a mortgage for a home, the physical residence serves as collateral. If you hit a rough patch and default, the bank simply sells the dwelling to get their cash back.

However, land is a different beast entirely. With a vacant lot, the only security is the soil itself. If the local real estate market takes a sudden nosedive, that dirt might end up being worth much less than the original loan amount. This creates a significant headache for lenders, as their fallback option is far less liquid and reliable.

Because the stakes are much higher, the requirements for land financing can feel like an uphill battle. You won’t find the same lenient terms used for suburban homes. Instead, you might find yourself digging deep into your savings to meet much steeper upfront requirements.
Expect to shell out a significantly larger chunk of change upfront. For raw land, down payments frequently range from 20% to 50% of the total value. Furthermore, the interest rates on these loans typically climb much higher than those of standard residential mortgages. It is a steep price to pay for the flexibility of building your own way.
Lenders will also scrutinize your property with a magnifying glass. They will demand exhaustive proof regarding utility access, legal easements, and how you plan to reach the site. If you happen to be working with a hard money lender, you might even be squeezed into a short-term repayment schedule.

Navigating the Path to Your New Acreage

Buying raw earth feels like a dream until you realize you’ve purchased a beautiful island in a sea of thicket. To avoid the heartbreak of an unusable plot, you must be a detective during your initial investigation. Don’t just fall in love with the sunset; look beneath the surface of the deal.

First, you must confirm how you will actually reach your front door. A dusty trail through a neighbor’s yard might look inviting, but without a formal legal right-of-way, that path is nothing more than a polite suggestion. Without guaranteed legal access to a public street, most banks will refuse to fund the project, leaving you stranded.

Next, consider the invisible necessities that make a site livable. If you intend to build a home, you’ll need a “perc test” to see if the earth can handle a septic system. Bad drainage can turn a dream into a money pit overnight. Also, keep a close eye on utility connections. Bringing electricity to a remote site can easily drain tens of thousands of dollars from your bank account.

Don’t assume the local laws will allow your vision to come to life just because the area feels wild. Zoning laws are the silent gatekeepers of every community. You need to scrutinize local ordinances to understand the rules regarding setbacks, the minimum amount of land required for a build, and whether you are allowed to keep livestock or specific outbuildings on the property.

Finally, never trust a boundary marked by a leaning fence or a neighbor’s casual word. Handshake agreements are worth very little when it comes to legal property lines. To ensure the acreage you are paying for matches the actual dirt on the ground, you must hire a professional to perform a formal survey.

Finding the right financier is a journey, not a race, and the “best” option depends entirely on your specific goals. If you are a fast-moving investor who needs to close a deal yesterday, a hard money lender like Lendersa might be your savior, despite the steeper interest rates. However, a permanent resident might find more peace of mind through a traditional bank or a USDA program.

A massive pitfall for many buyers is ignoring the “hidden” price tag attached to raw dirt. Unlike a finished house, a piece of land often requires an immediate infusion of cash for roads, water, and power. Make sure your loan covers these infrastructure necessities. If you spend every penny on the purchase price, you might end up owning a gorgeous view that you can never actually reach.

Keep a watchful eye on your credit score while you shop around for terms. Using services like Acorn Finance or JetzLoan can be a lifesaver because they offer rate checks that won’t dent your credit score. In the high-stakes world of land acquisition, being well-informed is your greatest asset. Do your homework thoroughly to ensure your financing aligns with your future life on the land.

Secure Fast Bad Credit Loans North Carolina: Compare Best Online Rates Now

By Uncategorized
Bad credit loans north carolina

Secure Fast Bad Credit Loans North Carolina: Compare Best Online Rates Now

Last updated: 2026-10-16

Managing your finances in the Tar Heel State can feel like navigating a thick fog when your credit report isn’t looking particularly bright. Residents across the state often hit a wall when an unexpected mechanical failure strikes a vehicle in Raleigh, or when medical expenses from a Charlotte urgent care center arrive all at once.

These sudden expenses demand instant liquidity to ensure your daily routine remains uninterrupted. It is a heavy burden to carry when life’s surprises collide with a tight budget. One minute you are planning your grocery list, and the next, you are staring at a looming electricity bill that threatens to drain your reserves.

Financial emergencies have a way of throwing a wrench in even the most disciplined monthly spending plans. Suddenly, the funds earmarked for your rent or basic utilities must be diverted to cover a crisis. It is an incredibly high-pressure scenario that can leave many families feeling like they are barely treading water.

Selecting an ideal lender requires a much deeper look than just checking the interest rate. You must balance the necessity of rapid funding against the ultimate price of the debt. While a low APR might look tempting on a brochure, waiting ten business days for funds won’t help when the utility company is at your door.

Conversely, those lightning-fast cash options might solve your problem today but could lead to much higher repayments than anticipated due to steep APRs. We have compiled this list to help you navigate these trade-offs between quick access to cash and long-term financial health. It aims to clarify which providers fit your current needs during turbulent times.

  1. FastLendGo
  2. Addition Financial
  3. PaydayPact
  4. Credit Human
  5. LoanStart

Assessing Cash Options for NC Residents

When putting this list together, our primary focus was how quickly someone could get cash if their credit isn’t stellar. We didn’t want to just look at numbers; we wanted to see if the process was actually painless.

Speed was a massive factor for us. We tracked how fast money hits your account and whether the application feels like a breeze or a heavy lift. If you are in a pinch, a slow website is as useless as a paper umbrella.

We also paid close attention to the “on-the-go” factor. Could you finish the form on a mobile phone while grabbing coffee, or is a bulky laptop mandatory? True convenience is a lifeline when life throws a curveball your way.

In North Carolina, it is a bitter pill to swallow that easier approvals often come with steeper interest. Lenders have to cover their backs when scores are low, so the APR usually takes a hit. It is the price of taking a chance on someone.

That is why our list favors lenders who are honest from the jump. We looked for companies that provide clear options for folks who got a “no” from the big banks earlier. It’s about finding a way forward when doors are slammed shut.

Transparency was our North Star throughout this research. We wanted to know if the total cost of borrowing is shouted from the rooftops or hidden in fine print. Nobody likes a surprise bill after they have already signed their life away.

You really need to see the final price tag before you commit. For anyone living paycheck to paycheck, knowing exactly what is coming out of your pocket is the only way to keep your head above water.

Company Borrowing Limits Eligibility Payout Timing Agreement Details
FastLendGo $500 – $5,000 Bad Credit / Fair Credit Same day or next business day see site
Addition Financial see site see site see site see site
PaydayPact see site Guaranteed approval online see site see site
Credit Human As little as $500 No credit review see site Up to 72 months
LoanStart Up to $40,000 see site see site see site

Top-Rated Lending Services for North Carolina Residents

FastLendGo

FastLendGo – fastlendgo.com

When an unexpected crisis strikes, like a sudden car breakdown or an urgent trip to the dentist, you need cash yesterday. FastLendGo is tailor-made for these high-pressure moments, bypassing the usual mountain of tedious paperwork. Their digital platform is incredibly sleek, catering to busy people who need solutions in a heartbeat rather than waiting around for days. (fastlendgo.com)

The versatility of their loan amounts is a major plus for varied needs. You might only require a $500 boost to cover groceries, or perhaps a $2,000 personal loan to patch up a leaky ceiling. They don’t care if your credit score took a hit from a medical emergency or if you are just trying to rebuild your reputation through timely payments.

Pros:

  • Loan values ranging from $500 to $5,000.
  • Rapid funding, with money potentially arriving the same day.
  • No minimum credit score needed to qualify.

Cons:

  • Cap on loan amounts limits larger borrowing needs.

Addition Financial

Addition Financial – additionfi.com

Sometimes, you want more than just a quick infusion of cash; you want a financial home. Addition Financial provides a full suite of banking tools, including mortgages, credit cards, and checking accounts. They are a fantastic pick if you are looking to foster a long-lasting relationship with a lender instead of just grabbing a temporary fix.

For those focused on building wealth, they offer various savings paths and competitive interest rates. If you are tired of the “quick fix” mentality and want to escape the cycle of high-interest debt, this institution offers a stable, traditional path. It is a smart move for anyone aiming to transition back into mainstream banking structures.

Pros:

  • A broad array of different banking products.
  • Opportunities to earn through various referrals.
  • Provides a wide spectrum of financial services.

Cons:

  • The application process may involve more paperwork than quick-cash lenders.

PaydayPact

PaydayPact – paydaypact.com

If other lenders have turned you away, PaydayPact might be your digital lifeline. Their platform is built to be incredibly user-friendly and secure, making the process a breeze. Whether you are riding the bus through Durham or sitting at your kitchen table, you can apply via any device without needing a printer.

The real magic here is the promise of a guaranteed approval through their online system. That certainty can be a massive weight off your shoulders when you are staring down an overdue rent payment. Knowing whether you have a “yes” or a “no” immediately helps quiet the mental storm of financial chaos.

Pros:

  • Highly accessible via any mobile device.
  • A secure environment for online applications.
  • Focuses on providing guaranteed approval.

Cons:

  • This type of lending model often comes with high interest rates.

Credit Human

Credit Human – credithuman.com

Credit Human brings a sense of order to the borrowing process by offering fixed interest rates. They are a great safety net for those needing as little as $500, providing a steady, predictable repayment plan. Because your rates are locked in, you won’t wake up to a monthly payment that has suddenly jumped due to market shifts.

One thing that really sets them apart is their ability to look beyond a single credit score. For North Carolinians who are tired of being defined by a three-digit number, this is a breath of fresh air. They tend to evaluate your overall financial stability, making them ideal for people who have faced temporary setbacks but remain reliable.

Pros:

  • Repayment terms can last up to 72 months.
  • Some products do not require a formal credit review.
  • Predictability through the use of fixed rates.

Cons:

  • Longer terms can result in paying more interest overall.

LoanStart

LoanStart – loanstart.com

Think of LoanStart as a high-tech matchmaker for your debt. Rather than sticking to one single lender, they tap into a vast network of affiliates to find your perfect fit. Since everyone’s financial situation is unique, this “wide net” approach ensures you aren’t forced into a one-size-fits-all solution that doesn’t suit your life.

This service is a powerhouse for anyone needing substantial capital, with the potential to secure up to $40,000. If you are drowning in credit card debt, using a structured installment loan to consolidate those balances can be a game-changer. It simplifies your monthly bills and could save you hundreds of dollars in interest over the long haul.

Pros:

  • Potential for large loans reaching up to $40,000.
  • A free service that won’t impact your credit score.
  • Connects you to a massive network of partners.

Cons:

  • Final terms are determined by the specific affiliate lender.

Evaluating Your Borrowing Options

For those navigating the tricky waters of debt in North Carolina, knowing which financial tool to grab is essential. Most lenders offer two distinct paths: quick-access, high-cost options or structured, long-term plans. Selecting the wrong vehicle for your money can quickly turn into a runaway train of interest payments.

Think of it like choosing between a sprint and a marathon. One is built for speed and immediate relief, while the other is designed for a long, steady journey. If you stumble into the wrong agreement, you might find yourself running in place while the debt grows.

Before signing any paperwork, you must look at the fine print. It is better to be cautious now than to be drowning in payments later. Understanding the fundamental split between these two categories will keep your finances on a much steadier course.

Characteristic Short-Term Loans Installment Loans
Standard Term A few months or mere days Between 12 and 72 months
Cost of Interest Extremely High (Frequently exceeding 300%) Moderate to High (Ranging from 10% to 36%)
Ideal Scenarios Urgent needs, like a $200 utility bill Major costs, like a $3,000 car engine or debt consolidation
Payback Method One single payment or many tiny ones Consistent monthly amounts

If a sudden crisis arises that your next paycheck can easily cover, a short-term loan might act as a quick band-aid. These are meant for temporary hiccups that don’t require a long-term commitment to resolve.

On the other hand, if your financial hole is deeper than what two paychecks can plug, look toward installment loans. Using a short-term fix for a massive problem is like trying to put out a forest fire with a water pistol; you’ll likely fall into a “debt trap” instead.

Navigating Your Repayment Journey After Taking a Loan

Grabbing the cash you need is merely the opening act; the real heavy lifting starts when the repayment schedule kicks in. It’s a common tale across North Carolina that once a financial fire is extinguished, the smoke leaves behind a lingering debt burden. Many people find that while the immediate emergency is over, the new obligation feels like a heavy weight on their shoulders.

To prevent your finances from slipping into a downward spiral, you need to be proactive rather than reactive. Think of it as steering a ship through a storm; you can’t just stop the waves, but you can certainly change your course to avoid the rocks. Staying ahead of your obligations requires a bit of discipline and a solid game plan.

Consider these three essential strategies to keep your financial health on track after securing your funds:

  1. Enable Automatic Transfers: Schedule your payments to leave your checking account automatically just one day after your payday hits. This simple trick acts as a safety net, ensuring you never accidentally miss a due date. Since missed payments are a direct hit to your credit score, this habit is worth its weight in gold.
  2. Focus on High-Interest Rates: If you are juggling several different debts, try utilizing the “avalanche method” to gain momentum. You should make the minimum required payments on everything, but channel every spare cent toward the debt with the steepest interest rate. This mathematical approach is the most efficient way to slash the total interest you’ll end up paying.
  3. Talk to Your Providers: If you are looking for a loan to cover a doctor’s bill or a utility expense, hold your horses before signing any papers. Reach out to the company directly to see if they offer hardship assistance or flexible payment schedules. Often, these companies can provide terms that are far more forgiving than the predatory rates found in quick-cash lending.

Staying Clear of Financial Missteps

When money is tight, the temptation to sign papers without scrutinizing the details is incredibly strong. You shouldn’t let desperation blind you to the actual price tag attached to your borrowing. Always hunt for the “total cost of credit” metric to understand your full liability. It reveals the true sum of every dollar that will eventually leave your pocket.

Imagine you borrow $1,000, but the interest rates are sky-high. By the time those six months conclude, you might find you’ve surrendered $1,500 to the lender. That extra $500 represents the hefty price you pay for immediate cash. It is essentially the premium for skipping the long wait of traditional banking.

Don’t fall into the trap of using new debt to cover old obligations unless the math makes sense. If a new loan carries a much smaller interest rate, it might help. However, using a high-interest payday loan to pay off a credit card is just shifting weight from one heavy anchor to a much heavier one.

If you’re constantly rotating through various short-term loans, you might be caught in a dangerous debt spiral. It feels like running on a treadmill that only goes faster. This cycle usually indicates that your monthly budget requires a complete overhaul rather than a quick fix through more borrowing.

Before you hand over any private details, double-check that the company is legitimate. In this digital era, it is frighteningly easy for scammers to pose as reputable financial institutions. They often use high-pressure tactics to make you act impulsively before you can think clearly.

You might see aggressive warnings like, “You have been pre-approved! Act now or lose the offer!” to trick you. These predators want your Social Security number or your bank credentials immediately. They rely on creating a sense of urgency to bypass your natural caution and steal your identity.

Protect your hard-earned cash by sticking to official and secure web addresses. Always look for that little padlock icon sitting in your browser’s address bar. Additionally, ensure the URL begins with “https://” before you type in any sensitive information. These small steps act as a vital shield for your digital life.

Best Ways to Secure Loans for Postal Employees with Bad Credit Today

By Uncategorized
Loans for postal employees with bad credit

Best Ways to Secure Loans for Postal Employees with Bad Credit Today

Last updated: 2026-10-17

Navigating your personal finances while grinding through grueling mail delivery shifts often feels like wading through heavy sludge. Sometimes, life hits you with a sudden punch that your regular salary simply cannot blunt. Whether it is a sudden mechanic’s bill or a surprise hospital invoice, many postal workers find themselves in a pinch that standard banks are all too eager to ignore.

Trying to balance the physical exhaustion of the route with the mental weight of mounting bills can make any obstacle seem like a mountain. When your credit rating takes a hit, the road to securing capital starts feeling like a labyrinth. You aren’t just hunting for a quick fix; you are searching for a lender that appreciates the inherent security of a government job.

A big-name bank might look at a temporary dip in your FICO score and simply slam the door. Specialized lenders, however, see past the numbers to the steady reliability of your federal wages. This evaluation examines how various lenders assist those needing a lift, prioritizing ease of use, rapid funding, and genuine empathy for your unique financial landscape.

Our analysis breaks down the leading options for 2026, specifically tailored to your needs.

  1. USPS Federal Credit Union
  2. Federal Employee Loans
  3. JetzLoan
  4. BMG Money
  5. Acorn Finance
  6. Credit Ninja

Our Criteria for Selecting Lenders

Hunting for a trustworthy money source involves more than just chasing flashy web banners or those tempting “get approved instantly” slogans. We decided to dig much deeper than the surface level. Our team aimed to see how these companies actually handle the unique financial life of a mail carrier.

Instead of obsessing over a perfect FICO, we examined if these lenders respect the ironclad security of a government-issued paycheck. We specifically sought out institutions that value payroll allotments as a way to offset risk. For many in the postal service, a steady federal salary matters far more than a damaged credit report.

We also had to strike a delicate balance between the speed of the cash and the long-term cost. When a delivery truck breaks down unexpectedly, you need help fast. A provider that can wire funds within a single day acts as a vital safety net during those sudden, stressful emergencies.

Yet, a quick fix can turn into a financial anchor if the interest rates are predatory. We carefully vetted the borrowing limits, how much wiggle room exists in repayment, and the impact of the application itself. We hunted for “soft pull” mechanisms that let you check your eligibility without harming your score.

Company Borrowing Limits Timeframes Payout Pace Eligibility Standards
USPS Federal Credit Union To $15,000 Check website Check website Check website
Federal Employee Loans $500 to $3,000 6 – 12 months Within the day No FICO check
JetzLoan Up to $35,000 Check website In under 24 hours No hard pull
BMG Money $500 – $12,000 6 – 48 months Immediate access Regardless of score
Acorn Finance Check website Check website Check website No score impact
Credit Ninja Check website Check website Decision within one day Check website

Top-Rated Lending Options for Postal Staff

1. USPS Federal Credit Union

USPS Federal Credit Union – uspsfcu.org

Since 1934, this organization has functioned on the principle of community solidarity. For anyone working in the postal service, there is a unique comfort in banking with a group that understands your specific professional background. It offers a sense of kinship that a cold, massive national bank can’t quite match.

Because these are nonprofit, member-owned cooperatives, their mission is to serve you rather than enrich distant shareholders. They provide various financial tools, including personal loans that can reach up to $15,000. These can help you navigate life’s twists, whether you are merging several expensive credit card balances or managing an unplanned relocation.

They truly grasp the intricacies of federal pay structures, such as seniority-based raises and regular adjustments. Because of this, their loan products feel custom-built for the lifestyle of a dedicated carrier or clerk. When you walk in, you aren’t just another number; you are a vital part of their legacy.

Pros:

  • Built specifically for USPS staff
  • Personal loans up to $15,000
  • Versatile terms for life’s changes

Cons:

  • Eligibility requirements or membership may apply

2. Federal Employee Loans

Federal Employee Loans – federalemployeeloans.com

You might not need a massive lump sum; sometimes, you just need a way to bridge the gap until your next paycheck arrives. This lender focuses on allotment loans, which are tailored specifically for those in the USPS and government sectors. This method allows a portion of your earnings to be sent directly to the lender for repayment.

This setup offers a level of assurance to the lender, which enables them to provide much more forgiving terms to you. It is a straightforward path for anyone needing a quick financial fix without the usual headache of intense underwriting. The sheer simplicity of this method is its greatest strength.

They don’t fixate on your FICO score; instead, they look at your federal employment status and your steady income shown on pay stubs. If you need a small amount to cover groceries or fuel, this is a remarkably efficient route. It’s like a helpful, silent nod from a trusted coworker in the sorting facility.

Pros:

  • No need for FICO credit checks
  • Get funds the same day for rapid help
  • Small, easy-to-manage loan amounts

Cons:

  • Lower borrowing ceilings than other lenders

3. JetzLoan

JetzLoan – jetzloan.com

In a modern age where speed is everything, waiting weeks for a loan feels like a relic of a bygone era. JetzLoan prioritizes velocity, working to ensure money hits your bank account within a single day. This is perfect for those facing an immediate crisis, like a broken washing machine or a sudden house repair.

They act as a vital middleman, introducing you to several different lenders so you can compare deals without hurting your credit score. This marketplace approach is a real game-changer. Rather than hitting ten different banks and triggering ten separate “hard pulls” on your report, JetzLoan lets you check eligibility with just one inquiry.

This is a contemporary solution for anyone wanting to see their true options without the anxiety of guessing at interest rates. You get to face the reality of your financial choices without the stress of endless, repetitive applications.

Pros:

  • Money can arrive in as little as 24 hours
  • Checking rates won’t trigger a hard credit pull
  • Maximum loan limits reaching $35,000

Cons:

  • Functions as a marketplace, not a direct lender

4. BMG Money

BMG Money – bmgmoney.com

Your worth is much more than a single digit on a credit report. BMG Money operates on the belief that a score doesn’t define your whole potential. They focus on employees and retirees working toward financial stability who need help right this moment. They understand that a credit score is just a look back at the past, while your current job and future salary are much better indicators of your reliability.

Their loan amounts are quite flexible, spanning from $500 up to $12,000. This makes them useful for everything from small home fixes to majorly tackling debt. For instance, instead of paying high interest on various retail cards, you could use a BMG Money loan to merge those debts into one single, manageable payment.

Their goal is to act as a partner in your journey toward better health in your finances. It is a very practical way to tidy up your debt with a more reasonable interest rate and a single monthly due date.

Pros:

  • Open to everyone regardless of credit history
  • Options for instant funding are available
  • Flexible repayment terms up to 48 months

Cons:

  • Some borrowers may face higher interest rates

5. Acorn Finance

Acorn Finance – acornfinance.com

If your money troubles are specifically about your house, Acorn Finance is the specialist you want. They concentrate on financing for contractors, making it much simpler to fund home upgrades even if your credit history isn’t perfect. This is incredibly helpful for postal workers who have spent years building their community and now want to boost their own property value.

They emphasize a transparent experience, letting you scout rates without any negative impact on your credit score. It is an ideal way to see what a new roof, deck, or kitchen remodel might cost without the pressure of a formal application. By smoothing the path between homeowners and specialist lenders, they remove the friction often found in home renovation loans.

Pros:

  • Contractors face zero dealer fees
  • No impact on credit when checking rates
  • Top-tier customer feedback on Trustpilot

Cons:

  • Mainly restricted to home improvement needs

6. Credit Ninja

Credit Ninja – creditninja.com

When big banks tend to shut their doors on you, Credit Ninja is often the one standing there with an invitation. They specialize in assisting people who might not fit the mold for standard loans, such as those with recent credit setbacks or thin credit histories. Their application setup is built to be swift, easy, and incredibly fast.

They cut through the red tape that typically stalls small loan requests. Their mission is to provide a way out when unexpected costs arrive and you feel like you’ve hit a dead end. If you cannot find a “yes” elsewhere because of a specific credit issue, their installment loans might offer the breathing room you need.

Think of them as a safety net for those sailing through choppy credit waters. They provide a path forward even when every other door seems to be locked tight.

Pros:

  • Quick decisions on the same day
  • Straightforward and rapid online application
  • Built for those with non-traditional credit

Cons:

  • Not a fit for every single credit scenario

Navigating the Hidden Dangers of Lending

Before ink hits the paper on any credit contract, you must truly grasp the machinery of your agreement. It is easy to get swept up in the allure of flashy advertisements that promise tiny monthly installments. Unfortunately, these often act as bait, masking the actual price of borrowing within the microscopic text of the fine print.

To ensure you aren’t walking into a financial ambush, demand a comprehensive breakdown of the “Total Cost of Loan.” This number serves as your North Star, revealing the full amount of capital that will vanish from your bank account throughout the entire life of the debt.

Keep a sharp eye on these three critical areas to keep your finances on the straight and narrow:

  • The Prepayment Penalty: It feels like a slap in the face if you try to settle your debt ahead of schedule. Some institutions levy extra charges if you attempt to clear your balance early. If a sudden windfall or a tax return lands in your lap, you should be able to pay it off without being penalized for your prudence. Seek out lenders that offer “no prepayment penalties.”
  • The Origination Fee: Think of this as a processing toll that the lender collects for setting up your account. This amount is frequently sliced directly from your initial disbursement. If your car repair requires exactly $2,000, a lender applying a 5% origination fee will only deposit $1,900 into your hands. Never forget to confirm the “net proceeds” before committing.
  • Variable vs. Fixed Rates: A variable interest rate can feel like a rollercoaster ride in a shifting economy. While the initial rate might seem incredibly tempting, your monthly obligation could skyrocket if market conditions change. For someone who needs a steady, predictable budget, locking in a fixed-rate loan is generally the much smarter, safer path forward.

Setting Yourself Up for a Smooth Approval Process

Securing a loan when your credit isn’t stellar requires more than just hope; it requires a strategy. Even when dealing with lenders who offer a bit of grace regarding your score, arriving fully prepared acts as your best wingman. Being organized signals to the creditor that you are a serious, reliable candidate.

Lenders essentially want a clear roadmap of your financial life. They need to verify that every dollar you claim to earn is actually hitting your bank account. Taking a quick thirty minutes to round up your files can save you from a massive headache later on.

There is nothing worse than needing cash urgently only to find your application stuck in limbo because of a missing document. Preparation is the bridge between a “maybe” and a “yes.” By doing the heavy lifting now, you ensure that your funding arrives exactly when you need it most.

Use this checklist to iron out the kinks before you hit submit:

  1. Collect Income Evidence: Keep your last two or three pay stubs in a neat folder. Since you work for the USPS, having your latest W-2 at your fingertips is a smart move. It provides a quick way for lenders to confirm how long you’ve been on the job.
  2. Map Out Your Monthly Costs: Lenders will scrutinize your “debt-to-income ratio,” which is just a fancy way of measuring your monthly obligations against your take-home pay. Total up your rent, vehicle loans, and any other debts to get a realistic view of your budget.
  3. Double-Check Personal Data: Make sure your current address, workplace details, and phone number are identical to what your bank has on file. If these details don’t line up, it might trip a red flag for fraud, which will slow everything down.
  4. Scrutinize Your Credit History: Even if you are pursuing a “no credit check” loan, you should still know exactly what is on your record. If you spot a mistake, like a payment marked late by error, fix it now to improve your future borrowing power.

Finding the right lender is a lot like picking out a new pair of work boots. You need a fit that accommodates your unique feet, provides enough ankle support for the long haul, and won’t crack under pressure. Don’t just look at the sticker price; look at the long-term wear and tear.

It is vital to look beyond the initial “easy” pitch. While a “no credit check” offer might seem like a lifeline in a pinch, the interest rates can often be quite steep. Always run the numbers to see the full cost of the loan over its entire lifespan.

You never want to be blindsided by a mountain of interest when you thought you were just making a small monthly payment. Knowing the total amount you will ultimately repay is the only way to avoid a financial trap. Transparency is your best friend when entering into any contract.

Lastly, lean into the fact that you have a stable career. Many lenders see postal workers as gold because of the job’s inherent reliability. You might find better terms or more lenient requirements by specifically seeking out lenders that favor federal employees or highlight your professional stability.

Top-Rated RV Financing Options for Buying Your Dream Rig Online in 2026

By Uncategorized
Rv financing

Top-Rated RV Financing Options for Buying Your Dream Rig Online in 2026

Last updated: 2026-10-16

For many adventurers, nothing beats the sensation of cruising down a highway in a high-end motorhome or a snug travel trailer. Yet, facing the massive price tag on a contemporary recreational vehicle can feel like staring up at a sheer cliff face without any climbing gear.

Securing a loan for these machines isn’t quite like walking into a dealership for a sedan. An RV occupies a strange middle ground; it is a blend of a motorized vehicle, a private residence, and a significant personal lifestyle investment.

This unique character means that the world of borrowing money is far more intricate than typical car loans. You aren’t just buying a way to get from point A to point B; you are acquiring a mobile piece of real estate.

It is vital to track down a creditor that truly grasps the intricacies of these leisure-oriented assets. Whether your goal is a permanent secondary dwelling on wheels or just a small camper for quick weekend escapes, your chosen loan structure dictates your actual level of liberty.

Bad terms can turn a beautiful dream into a heavy weight around your neck. If you end up stuck with punishing interest rates or rigid monthly demands, you might find yourself staring at your driveway rather than the scenic vistas of our national parks.

  1. FastLendGo
  2. My Financing USA
  3. Southeast Financial
  4. GreatRVLoan
  5. GadCapital
  6. Manhattan Bank

Our Methodology for Rating RV Loan Providers

Finding the right way to fund your nomadic lifestyle is about more than just hunting for the smallest percentage rate. It is a delicate balancing act involving how fast you get a thumbs up, how adaptable the repayment schedule is, and if the firm accepts different scoring tiers. Sometimes, what works for a million-dollar diesel pusher won’t work for a beat-up camper van.

Think of it like buying shoes; a high-end marathon runner needs different support than someone strolling through a park. A bank catering to luxury coaches might demand a mountain of cash upfront and extensive proof of wealth. Conversely, a lender focused on pre-owned trailers might care much more about the resale value of the unit itself.

We didn’t just glance at the surface level. Instead, our team dissected several fundamental categories to build a comprehensive list that actually makes sense for real-world travelers.

  • Financing Framework: We checked if they provide steady, fixed-rate options or variable rates that might start cheap but climb later.
  • Asset Range: We looked for lenders capable of covering a shiny new Class A, a dusty used pop-up, or even watercraft like jet skis.
  • Approval Velocity: It matters how much time passes between shaking hands at the dealer and seeing the money hit the account.
  • Credit Accessibility: We sought out institutions that offer a seat at the table for those with limited history or bruised credit scores.

This list spans the entire financial spectrum. We included everything from elite brokers for high-net-worth clients to approachable digital lenders for those rebuilding their standing. Whether you are looking for a standard personal loan or navigating a tricky credit situation, our research covers the map.

Provider Available Products Credit Standards Unique Advantages
FastLendGo Personal Loans Accepts Fair to Poor Scores Rapid liquidity
My Financing USA RV and Boat Loans All Credit Tiers National coverage
Southeast Financial Various Vehicle Loans Consult Website Credit Union Perks
GreatRVLoan New, Used, Private Party Credit Repair Options Duration up to 20 years
GadCapital Payday/Short-term No Credit Check Required Immediate payments
Manhattan Bank Personal & Business Consult Website FDIC-Insured Security

Leading Recreational Vehicle Financing Providers for 2026

1. FastLendGo

FastLendGo – fastlendgo.com

Think of FastLendGo as a financial bridge for those needing to plug a sudden gap in their funds. They specialize in versatile personal loans that work for a wide spectrum of credit profiles. It is a lifesaver for the spontaneous adventurer who spots a vintage camper at a yard sale and needs cash before the sun sets on the deal. (fastlendgo.com)

This option is a solid choice if you are looking to cover minor expenses without a headache. Their lending range spans from $500 up to significant sums for those with high earnings. Since these are typically unsecured, your RV won’t be tied to the debt, letting you keep your precious toy free from the clutches of a lien.

Pros:
  • Welcomes everyone from those with poor credit to those with stellar scores.
  • Delivers rapid cash for immediate requirements.
  • Tailored loan structures for high-income earners.
Cons:
  • Primarily offers personal loans rather than specialized RV financing.

2. My Financing USA

My Financing USA – myfinancingusa.com

If you have your eyes on a massive fifth wheel or a sleek new boat, My Financing USA acts as your personal scout. They scour the entire country to hunt down the most suitable programs for your specific lifestyle. Rather than just checking a single bank’s list, they scan the whole horizon to pair you with the right lender.

They are a heavy hitter for anyone owning diverse recreational gear. Whether it is a yacht, a camper van, or even jet skis, their reach is incredibly wide. This is a dream for the multi-vehicle traveler who wants to handle all their fun-related debt through one expert source.

Pros:
  • Huge variety including jet skis, boats, and RVs.
  • Conducts nationwide searches for optimal programs.
  • Options available regardless of your credit history.
Cons:
  • The massive product range might result in a more involved application.

3. Southeast Financial

Southeast Financial – southeastfinancial.com

Southeast Financial operates as a full-service credit union, offering a steady and community-focused atmosphere. Their toolkit goes well beyond vehicle loans, touching on things like wealth management and mortgages. It is a perfect home for someone wanting to tuck all their finances—from their house to their weekend camper—into a single, convenient bucket.

For the seasoned traveler who wants a deep banking relationship, this is a fantastic path. Because they are member-owned non-profits, you often find a more personal touch. This structure frequently translates into better deals, such as higher savings yields or lower interest rates than your average commercial bank.

Pros:
  • Full-spectrum services from wealth management to insurance.
  • Member-focused benefits via the credit union model.
  • Diverse loan products covering homes and autos.
Cons:
  • Access may be restricted by specific membership criteria.

4. GreatRVLoan

GreatRVLoan – greatrvloan.com

Operating out of the West Coast, GreatRVLoan is a specialized brokerage that has been in the game since 2002. They realize an RV is more than just metal and tires; it’s a ticket to freedom. Their long history helps them understand exactly how different depreciation curves impact your interest rates and approval odds.

They really shine when the road gets bumpy, such as when buying from a private seller or purchasing out-of-state. While many big banks turn their noses up at private sales because of the messy paperwork, GreatRVLoan has the systems in place to handle them. They are a lifeline for smart buyers looking in the used market.

Pros:
  • Experts in tricky situations like private party transactions.
  • Flexible repayment terms that can span up to 20 years.
  • Navigates credit challenges with high efficiency.
Cons:
  • Operates as a broker, acting as a middleman rather than a direct lender.

5. GadCapital

GadCapital – gadcapital.com

Sometimes, life throws a wrench in your gears when you least expect it. GadCapital steps in when you need cash fast, offering quick installment and payday loans for urgent scenarios. This might cover an unexpected engine repair mid-trip or a sudden tax bill that stands between you and your next camping adventure.

This lender is built for speed, specifically for those who might hit a wall with traditional banks. Their application process is digital-first and incredibly straightforward. While you wouldn’t use them to buy a luxury motorhome, they are a vital safety net for the sudden expenses of the nomadic life.

Pros:
  • Built specifically for rapid, pressing financial needs.
  • Offers paths to cash without a credit check.
  • Fast results via a simple online application.
Cons:
  • The speed of these short-term loans often carries higher costs.

6. Manhattan Bank

Manhattan Bank – manhattanbank.com

Manhattan Bank provides the rock-solid stability that comes with an FDIC-insured institution. They offer a formal route for those seeking business or personal loans through highly regulated channels. This is a top choice for entrepreneurs looking to write off a luxury RV as a legitimate business expense.

For the borrower who wants to play it safe, this is the gold standard. They provide loans for “every occasion” within a professional and highly secure framework. While they may lack the high-tech gloss of a new fintech app, their institutional weight offers the peace of mind that comes with massive, regulated stability.

Pros:
  • High levels of trust and security via FDIC insurance.
  • A professional and established banking environment.
  • Wide range of business and personal loan options.
Cons:
  • Standard banking procedures can move slower than tech-driven competitors.

Crucial Elements to Weigh Before Committing to an RV Loan

Getting your hands on a loan is just the tip of the iceberg; the real work begins once you start paying it back. Since these vehicles are depreciating assets, they lose a chunk of their worth as the years roll by.

Because of this inevitable drop in value, you must grasp how your specific financing setup aligns with what your rig is actually worth. If you aren’t careful, the math might not stay in your favor.

The Reality of Depreciation and Negative Equity

The most significant pitfall in the world of RV lending is finding yourself “underwater” or “upside-down.” This messy situation occurs when your outstanding debt exceeds the current market price of your recreational vehicle.

You see this most often with brand-new, luxury motorhomes. The moment those tires touch the pavement outside a dealership, the resale price takes a massive nosedive, leaving you stuck with a high balance.

To keep your head above water, try to put down a substantial amount of cash upfront. Experts frequently suggest a 20% down payment to build immediate equity in your new mobile home.

Calculating the Real Price of Ownership

When you are crunching the numbers for your travel budget, don’t just fixate on that single monthly installment. A smart traveler looks at the big picture to avoid any nasty financial surprises.

You need to factor in several “hidden” expenses that will inevitably eat into your vacation fund. Ignoring these can turn a dream trip into a stressful debt spiral very quickly.

Cost Type Estimated Monthly Cost Details
Insurance Coverage $100 – $300+ Standard auto policies won’t cut it; you need specialized RV plans.
Storage Costs $50 – $200 An essential expense if your driveway is too small for the rig.
Upkeep and Repairs $100 – $500 Budget for roof checks, tire rotations, and routine oil changes.
Camping Site Rates Variable Expect to pay anywhere from $30 for primitive spots to $150+ for luxury resorts.

Charting Your Financial Course Toward Freedom

Securing the keys to your new home on wheels involves navigating a complex maze of monetary decisions. Many buyers make the mistake of focusing solely on what they owe each month. This narrow view can be a dangerous trap for your long-term budget.

You must scrutinize the complete price tag of your debt over its full duration. For instance, a $500 monthly installment might seem like a breeze at first glance. However, if that obligation stretches across 20 years with a high interest rate, you could effectively pay for your vehicle twice through interest alone.

Don’t let the lure of a rapid “yes” blind you to the hidden costs of credit. While getting a quick approval feels like a victory, it often carries a heavy interest rate penalty. These high rates can act like a heavy anchor on your finances for years to come.

Always dig deeper into the fine print regarding prepayment penalties. These clauses are designed to keep you paying interest even when you have the extra cash to settle the debt. You want the flexibility to make extra payments toward your principal without facing extra fees.

Suppose a sudden windfall or a generous tax refund lands in your bank account. Ideally, you should be able to apply that money directly to your RV loan. Without the ability to pay down the balance early, you miss a massive opportunity to save thousands.

Keep your paperwork in tip-top shape to avoid unnecessary delays. Whether you are working with a local credit union or a giant national bank, speed is your best friend. Having every document organized will save you a massive amount of stress later.

Make sure your proof of income is ready for immediate review. This includes W-2 forms, your latest pay stubs, or your most recent tax returns if you are self-employed. Being proactive with these files is the secret to a smooth transaction.

A disorganized file can turn a quick weekend purchase into a month-long headache. If you aren’t prepared, you might watch your dream rig roll off the lot to another buyer. Don’t let someone else drive away in the life you planned simply because your credit check was delayed.

Get Fast Approval on Bad Credit Loans Virginia Residents Trust Today

By Uncategorized
Bad credit loans virginia

Get Fast Approval on Bad Credit Loans Virginia Residents Trust Today

Last updated: 2026-10-17

Navigating your finances within the Commonwealth often feels like wandering through a dense mist when your credit score is lagging. Suddenly, an unexpected medical expense or a broken car transmission on I-95 can leave you feeling completely stranded. It is easy to lose your bearings when a sudden dental bill in Alexandria demands immediate payment.

When these emergencies strike, the hunt for quick cash can make your head spin. You aren’t just looking for a temporary fix; you are searching for a lifeline that won’t drag your financial stability into the abyss. It is vital to keep a clear head during these high-pressure moments to avoid making costly mistakes.

Finding a trustworthy lender means peering behind the curtain of glossy marketing to find the real truth. Speed and clear terms are essential, but they aren’t the only things that matter. You must weigh the immediate benefit against the total cost of borrowing over the next six months.

Our curated selection focuses on providers that offer rapid access to funds while maintaining transparency. We want you to grasp the fine print before you ever pick up a pen. This list identifies the best ways to bridge the gap between your current budget and those sudden, unavoidable life expenses.

  1. OppLoans
  2. MaxCash
  3. JetzLoan
  4. Vacu
  5. 1st Advantage

Comparing Financing Options Throughout Virginia

Our team vetted these providers by looking at their reach in major hubs, including Norfolk, Richmond, and Virginia Beach. We wanted to ensure folks aren’t drowning in a sea of endless forms. When life throws a curveball, you need cash that moves faster than a snail.

A sudden power outage or a threat of losing your home won’t wait a week for some bank clerk to sign off on a file. Traditional institutions often drag their feet for several days. We prioritized lenders that respect the urgency of a financial emergency.

Timing is everything when your back is against the wall. While a few companies can drop funds into your account by the end of the day, others might make you wait. We looked at the entire timeline from application to payout.

We also weighed how these inquiries might bruise your FICO score. It is a heavy blow to see your rating drop when you are already scraping the bottom of the barrel. A “hard pull” can haunt your record for years, potentially sabotaging future car loans or house purchases.

Think of a “soft pull” as a trial run that costs you nothing. It allows you to scout the landscape without any damage to your standing. This method lets you weigh your different paths without the dread of a plummeting score.

If you are just dipping your toes into the market, hunt for companies that offer this safety net. It is the smartest way to hunt for better rates without gambling with your financial reputation. Knowledge is power when you are navigating tricky waters.

Comparing Local Borrowing Services in Virginia

Finding the right lender can feel like looking for a needle in a haystack when your credit score is lagging. You want someone who won’t drop a hammer on your FICO score just for asking a question.

Every situation is unique, and what works for your neighbor might not be the silver bullet for you. Some folks need a quick infusion of cash, while others require a much larger safety net to get through the month.

We have gathered a snapshot of various providers available in the Old Dominion State. This breakdown helps you weigh your options before you sign any paperwork or dive into a new debt obligation.

Provider Borrowing Limits Speed of Funds Credit Inquiry Effect Primary Benefit
OppLoans $500 – $5,000 Funds can arrive today FICO score remains untouched Transparent fee structure
MaxCash $250 – $10,000+ Approval occurs in minutes Soft inquiry only Diverse loan varieties
JetzLoan $500 – $35,000 Quickly within 24 hours Avoids hard credit pulls Excellent user feedback
Vacu Starts at $100 Check website for details Check website for details Ability to refinance
1st Advantage Maximum $750 Check website for details Choice of no credit check Specializes in short-term loans

Top Rated Lending Services for Virginia Residents with Low Credit

1. OppLoans

OppLoans – opploans.com

If you are tired of being ghosted by big banks because of a bumpy financial history, OppLoans might be your saving grace. They don’t play the FICO game as strictly as the traditional giants do. Instead, they cast a wider net by looking at your steady income and recent banking activity.

Speed is the name of the game here. Their digital system works like a lightning strike, often delivering a decision in mere minutes. When life throws a curveball, having funds arrive on the same day can feel like finding an umbrella in a thunderstorm. It serves as a perfect bridge between your current wallet and your next payday.

Pros:

  • Checking your eligibility won’t dent your FICO score.
  • Approved borrowers can receive same-day funding.
  • The fine print is clear of hidden fees.

Cons:

  • The total amount you can borrow is smaller than what major banks offer.

2. MaxCash

MaxCash – maxcash.com

Think of MaxCash as a financial Swiss Army knife. Whether you just need a tiny bit of extra cash for a sudden errand or a hefty sum for a major life event, they have a tool for the job. Their inventory of loan options is incredibly broad, catering to various levels of financial urgency.

Maybe you need a quick $300 to keep the lights on, or perhaps a $5,000 injection is needed to get your work vehicle back on the road. The beauty of their platform is the “no strings attached” inquiry. You can scout your options without any hard credit pull, which is a breath of fresh air for those testing the waters.

Pros:

  • Funding options range from $250 all the way up to $10,000+.
  • You can check your rates for free without any obligation.
  • A diverse selection including installment and title loans.

Cons:

  • The sheer number of different products might feel a bit dizzying.

3. JetzLoan

JetzLoan – jetzloan.com

When time is of the essence, JetzLoan steps up to the plate. They have built their reputation on velocity, aiming to get cash into your hands within a 24-hour window. If you are facing a crisis, you won’t want to spend a week waiting on paperwork to clear. (jetzloan.com)

They aren’t just playing in the small leagues, either. You can access significant capital, reaching up to $35,000, which is quite a heavy hitter for such a fast service. This makes them a top contender for massive surprises, like an unexpected hospital bill or a sudden roof leak. Their transparency is refreshing, and your credit score stays safe during the initial rate-check phase.

Pros:

  • Boasts an impressive 4.7-star customer rating.
  • Money can be sent within 24 hours of being approved.
  • Initial rate checks do not require a hard credit pull.

Cons:

  • Some users might find the rapid application process a bit rushed.

4. Vacu

Vacu – vacu.org

Vacu operates with a philosophy more akin to a neighborhood credit union than a faceless online lender. Because they are member-owned, the atmosphere—and sometimes the terms—can feel much more personal. They provide a safety net for the small stuff, offering personal loans that start as low as $100.

One of their standout moves is the ability to help you clean up your financial house through refinancing. If you have high-interest debt, you might find rates as low as 4.49% APR in specific scenarios. It’s like taking a heavy weight off your shoulders by consolidating multiple debts into one manageable, lower-cost monthly payment.

Pros:

  • Extremely low minimum amounts for borrowing.
  • Offers the chance to refinance and lower your interest rates.
  • Provides a full suite of banking services.

Cons:

  • You may need to meet specific membership requirements.

5. 1st Advantage

1st Advantage – 1stadvantage.org

1st Advantage is like the emergency toolkit in your drawer. They specialize in the “right now” moments that require a quick, short-term fix. Their loans go up to $750 and are tailor-made for people who need to bridge a gap immediately without jumping through standard credit check hoops.

Don’t expect to fund a kitchen remodel here, but if you find yourself facing a sudden $200 repair bill for your car, this is a direct line to help. The application is stripped down to the essentials. You won’t spend your afternoon typing into a screen; you’ll spend your time actually solving your immediate financial hiccup.

Pros:

  • Certain short-term options require no credit check.
  • Specifically tailored for urgent, unexpected life events.
  • The application process is incredibly straightforward.

Cons:

  • The borrowing limits are quite low compared to other players.

Cracking the Code of Your Debt Obligations

When life throws a curveball and cash is tight, your eyes naturally gravitate toward the monthly installment amount. It feels like a lifeline when a creditor whispers that you can settle your debt for a mere $50 every month. This small figure feels much lighter than a massive, single payment.

Don’t let that comfort fool you, though. This is where the real math gets slippery and hidden costs start to crawl out of the woodwork. You really need to keep a sharp eye on the Annual Percentage Rate, or APR. This specific number wraps up both the interest rates and any extra processing or origination fees into one figure.

It is vital to look past the surface-level numbers to see the bigger picture of your debt. If you focus only on the immediate monthly chunk, you might find yourself in a tighter spot than you anticipated. Think of it as looking at the price tag without checking if the assembly costs are double the original amount.

Take a look at how different loan structures can trick the eye:
Comparison Case Installment Amount Sum of Fees and Interest Full Loan Expenditure
Option A (Lower APR) $100 $200 $1,200
Option B (Higher APR) $75 $500 $1,300

In the scenario pictured above, Option B looks like a steal because the monthly commitment is lower. However, that choice actually bleeds more money from your wallet over the lifespan of the agreement. You end up paying a higher premium just to keep the monthly payments manageable.

Always run the numbers to find the final amount you will have handed over once the contract expires. This “Total Cost of Credit” is the gold standard for evaluating your commitment. It is the only metric that truly shows how much your financial stability will be taxed in the long run.

Steps to Streamline Your Request

Think of your application like a first date; you want everything to look polished and professional. Before you even begin clicking through an online form, it is wise to round up your paperwork. Having these items ready to go can be the difference between a swift approval and a long wait.

Most creditors will ask you to upload a clear photograph or a digital scan of several specific documents. Taking a moment to organize these files beforehand keeps the momentum going. You won’t want to be hunting through drawers for a lost bill when the clock is ticking.

Keep an eye on these essential items to ensure your submission is watertight:

  • Identity Verification: A current state ID or your valid driver’s license.
  • Income Verification: Recent bank statements, W-2 paperwork, or your latest pay stubs.
  • Address Verification: A rental contract or a utility bill that confirms where you live.
  • Banking Information: Your routing and account numbers for ACH transfers into an active account.

Precision is your best friend during this stage of the journey. Even a tiny slip-up, such as a misplaced digit in your Social Security number, can throw a wrench in the works. Small mistakes often lead to a manual review by a loan officer, which slows everything down.

If you are dealing with an urgent financial crisis, every hour counts. A mismatched street name or a typo in your address might seem minor, but they can postpone your cash injection by several days. Staying meticulous ensures the money hits your account when you need it most.

Making Smart Choices for Your Loans

Selecting a financier is remarkably similar to shopping for footwear; the perfect match depends entirely on your unique feet. If your goal involves financing a massive, multi-year renovation, a local credit union might offer the most favorable terms. These institutions often prioritize community stability over rapid turnover.

On the other hand, if an unexpected mechanical failure leaves your vehicle stranded, time becomes your most vital asset. You might find that online lenders offer the lightning-fast response you desperately need. There is no universal solution in the credit market; there is only the choice that solves your immediate emergency without breaking your future finances.

Don’t let a low monthly installment lure you into a financial pitfall. While a tiny payment looks enticing on paper, the actual weight on your budget is determined by the cumulative cost of interest and extra charges. Always scrutinize the fine print to ensure you aren’t blindsided by hidden costs.

For instance, watch out for prepayment penalties. Some lenders will actually charge you an extra fee if you try to settle your debt ahead of schedule. It sounds counterintuitive, but those clauses can make early repayment quite expensive. Always check these terms before signing your name to a contract.

A frequent blunder involves firing off numerous loan applications to various providers at the same time. Even if a lender performs a soft pull that protects your score, a sudden flurry of requests might cause alarm for traditional banks later. They tend to view a high volume of recent inquiries as a warning sign.

To a strict creditor, this pattern might suggest you are drowning in debt and desperately hunting for liquidity. Such a perception can make securing future mortgages or car loans much more difficult. Take a deep breath and weigh your possibilities carefully before hitting that submit button.