Notice: Function _load_textdomain_just_in_time was called incorrectly. Translation loading for the wpforms-lite domain was triggered too early. This is usually an indicator for some code in the plugin or theme running too early. Translations should be loaded at the init action or later. Please see Debugging in WordPress for more information. (This message was added in version 6.7.0.) in /home/howhumansthink/public_html/wp-includes/functions.php on line 6131

Notice: Function _load_textdomain_just_in_time was called incorrectly. Translation loading for the salient domain was triggered too early. This is usually an indicator for some code in the plugin or theme running too early. Translations should be loaded at the init action or later. Please see Debugging in WordPress for more information. (This message was added in version 6.7.0.) in /home/howhumansthink/public_html/wp-includes/functions.php on line 6131

Notice: Function _load_textdomain_just_in_time was called incorrectly. Translation loading for the salient domain was triggered too early. This is usually an indicator for some code in the plugin or theme running too early. Translations should be loaded at the init action or later. Please see Debugging in WordPress for more information. (This message was added in version 6.7.0.) in /home/howhumansthink/public_html/wp-includes/functions.php on line 6131

Notice: Function _load_textdomain_just_in_time was called incorrectly. Translation loading for the salient domain was triggered too early. This is usually an indicator for some code in the plugin or theme running too early. Translations should be loaded at the init action or later. Please see Debugging in WordPress for more information. (This message was added in version 6.7.0.) in /home/howhumansthink/public_html/wp-includes/functions.php on line 6131
admin-pro – Page 4180 – Will Steinberg, MD MSPH Skip to main content
All Posts By

admin-pro

Get Fast Cash with Bad Credit Loans New Jersey Today

By Uncategorized
Bad credit loans new jersey

Get Fast Cash with Bad Credit Loans New Jersey Today

Last updated: 2026-10-16

When an unexpected transmission failure or a sudden hospital invoice arrives, it can feel like you’ve crashed into a financial wall. Residents throughout New Jersey often find themselves trapped in this exact scenario. They are frequently staring down a mountain of unexpected debt that seemed to appear out of thin air.

You shouldn’t be judged solely by a single number on a credit report. Instead, you need a creditor that evaluates your actual ability to settle the balance. It is about looking at the person, not just the score, to ensure you can actually manage the repayments.

From a broken car in Newark to a sudden dental emergency in Jersey City, the pressure of a crisis can cloud your judgment. It becomes incredibly difficult to perform due diligence when you are feeling the heat. This sudden urgency often clouds our vision.

You might feel a desperate urge to grab the first deal you see just to stop the bleeding. However, acting on pure impulse can lead to massive headaches down the line. Taking a breath is essential before making any permanent moves.

Navigating the vast ocean of available lenders requires both a keen eye and a grounded perspective. Some firms provide instant cash but demand a heavy price for that lightning speed. On the other hand, traditional banks offer more reliability but move like a snail in traffic.

Our goal is to find that sweet spot for those with less-than-perfect credit. We want to help you stay on a healthy financial path. Finding the right balance between speed and cost is the key to long-term success.

There is a world of difference between a high-interest installment loan and a structured plan for medical bills. Picking the wrong vehicle for your debt can turn a small bump in the road into a permanent cycle of struggle. You must choose your path wisely.

Use this information to carefully evaluate every option before you ever pick up a pen. Taking the time to weigh your choices now can save you years of stress later. Knowledge is your best defense against predatory practices.

  1. Max Cash
  2. FastLendGo
  3. XCEL Federal Credit Union
  4. Fulton Bank
  5. Loanz
  6. Cherry
  7. CareCredit

Comparing Loan Providers Across the Garden State

Picking a lender that truly aligns with your personal circumstances requires a deep dive into several distinct factors. Most people facing a sudden crisis value rapid turnaround time above everything else. Since commuting is a way of life in New Jersey, a car breakdown can be catastrophic; waiting several days for funds could be a dealbreaker.

That said, the long-term impact on your wallet depends on the total cost of your debt. It is vital to scrutinize interest rates alongside any hidden administrative charges. A lightning-fast loan won’t help much if the high interest rates eventually swallow your entire monthly paycheck.

We also evaluated the level of flexibility available when your credit history isn’t exactly pristine. Some companies offer title loans if you lack traditional collateral, whereas others specialize specifically in medical financing. These options span a huge range, from a modest $250 cash advance to substantial $60,000 signature loans.

Our research investigated whether a lender prioritizes your employment status or your numerical credit score. Generally speaking, your actual ability to repay—based on steady income—is a much more reliable indicator of financial stability than a single digit on a credit report.

Lender Name Funding Range Turnaround Time Credit Standards
Max Cash $250 – $10,000+ Minutes Bad Credit Options
FastLendGo Small Loans Available Quick Access Bad Credit/No Credit
XCEL Federal Credit Union $500 – $60,000 See Site Secured/Unsecured
Fulton Bank See Site See Site See Site
Loanz $100 – $10,000 Quick/Convenient See Site
Cherry See Site Instant Approval High Approval Rate
CareCredit See Site Instant Decisions Subject to Credit

1. Max Cash

Max Cash – maxcash.com

Think of Max Cash as a comprehensive hub for various borrowing needs. Their product lineup stretches from small $250 advances to significant loans exceeding $10,000. This makes them a dependable resource if you are facing an unexpected bill that needs immediate attention. A $500 injection might cover a broken appliance, while larger amounts tackle car or home repairs.

Speed is the heartbeat of this platform. They cater specifically to individuals who require installment or title loans in just a matter of minutes. Because they cater to those with poor credit, they offer a vital lifeline that traditional big-box banks often refuse to provide. Just remember, that rapid speed often comes with a higher interest rate.

Pros:

  • Rapid processing for time-sensitive emergencies.
  • A broad spectrum of loan types, including title options.
  • Accessible for borrowers with poor credit scores.

Cons:

  • Title loans require collateral, which puts your car at risk.

2. FastLendGo
FastLendGo – fastlendgo.com

FastLendGo serves as a versatile tool for managing personal finances. They accommodate every credit tier, whether you are sitting on good, fair, or bad credit. It serves as an efficient way to scan local possibilities without having to physically visit multiple bank branches. (fastlendgo.com)

This lender is particularly helpful for specific milestones, like unexpected dental work or emergency auto repairs. If you are hunting for personal loans in your immediate area, their digital model streamlines that entire search. They aggregate various profiles to help align your specific credit score with a provider that actually wants to work with you.

Pros:

  • Useful for diverse needs like roofing or dental costs.
  • Availability for those lacking a credit history.
  • A user-friendly online comparison interface.

Cons:

  • Primarily functions as a comparison service rather than a bank.

3. XCEL Federal Credit Union
XCEL Federal Credit Union – xcelfcu.org

If you are searching for a more traditional sense of security, XCEL Federal Credit Union provides both secured and signature loans. Their borrowing capacity can climb as high as $60,000, offering a substantial safety net for major life transitions. Such funds might be utilized for consolidating debt, renovating your home, or managing unexpected medical bills.

Operating as a credit union, they tend to feel more community-centered than predatory lenders. Since these institutions are member-owned rather than beholden to shareholders, you often receive more personalized attention. You have the choice between secured or unsecured loans to find your perfect fit. Often, using a savings account as collateral can unlock much more favorable rates.

Pros:

  • Large borrowing maximums reaching up to $60,000.
  • The option to use secured loans for better rates.
  • A service model that focuses on the member.

Cons:

  • Likely requires specific eligibility or membership.

4. Fulton Bank
Fulton Bank – fultonbank.com

Fulton Bank is a prominent name throughout the New Jersey landscape. They possess the robust infrastructure of a large-scale institution while retaining a distinctly local character. This makes them a dependable partner for long-term banking and navigating complex financial obligations over many years.

Their offerings span from standard personal accounts to sophisticated commercial banking. While they might not be the quickest way to grab a $200 emergency loan, they are exceptional for overseeing significant assets or business ventures. Their institutional stability provides peace of mind if you want a lender that will be standing tall for decades.

Pros:

  • Extremely secure with FDIC insurance.
  • A vast array of services from personal to business.
  • A formidable presence in the New Jersey area.

Cons:

  • Stricter criteria may exist compared to specialized lenders.

5. Loanz
Loanz – loanz.com

Loanz specializes in helping you take charge of your financial future through targeted loan options. With borrowing limits ranging from $100 to $10,000, they are perfect for tackling smaller debts or upcoming costs like wedding expenses or moving. This allows you to nip small financial problems in the bud before they grow into massive burdens.

The core objective here is helping you regain control of your daily life. Their specific debt consolidation tools help you manage multiple different obligations at once. Rather than juggling five separate due dates, you can merge them into a single monthly payment to simplify your budget and reduce interest-related stress.

Pros:

  • Very low entry point with loans from $100.
  • Specialized products designed for debt consolidation.
  • Smooth and modern digital transactions.

Cons:

  • Maximum loan amounts are capped at a modest $10,000.

6. Cherry
Cherry – withcherry.com

Cherry operates as a specialist within the retail and healthcare finance sector. They boast a remarkable 90% approval rate and are utilized by thousands of different service providers. Their fundamental mission is to let you access essential services immediately and pay for them over time, removing the barrier of high upfront costs.

The application process is incredibly swift, frequently concluding in just 35 seconds. This makes them a top-tier choice for those needing immediate home repairs or dental work who prefer to spread out their payments. Cherry integrates directly with your provider to make the entire experience seamless.

Pros:

  • Lightning-fast application procedures.
  • Strong approval rates for most consumers.
  • Seamlessly integrated with many healthcare providers.

Cons:

  • Functionality is restricted to certain merchants.

7. CareCredit
CareCredit – carecredit.com

CareCredit is a credit card designed exclusively for the wellness and medical industries. Since it is accepted at more than 285,000 different locations, it is among the most versatile tools for managing health expenses. You can utilize it for anything from vision care and dental work to veterinary bills.

You can determine if you qualify through a prequalification process that does not impact your credit score. This is a crucial feature if you are cautious about your score while shopping for medical care. Many plans include “no interest if paid in full” incentives, but stay sharp—missing a payment can trigger retroactive interest charges.

Pros:

  • Prequalifying won’t hurt your credit score.
  • A massive network of thousands of locations.
  • Flexible financing options for health needs.

Cons:

  • Approval and terms are subject to credit checks.

Navigating the Divide Between Secured and Unsecured Financing

Before you dive headfirst into the application process, you must grasp whether your borrowing option is secured or unsecured. This fundamental distinction alters your entire risk profile. Think of it as a safety net that works both ways for the borrower and the lender.

When dealing with a secured loan, you are essentially putting up skin in the game. These agreements are tied to a specific asset, such as your house, your vehicle, or even funds held in a savings account. Because the lender has a fallback option if you fall behind on payments, they are frequently more willing to extend credit to those with less-than-stellar credit scores.

While these types of loans frequently offer more favorable interest rates, the personal stakes are significantly higher. If you lose track of your title loan payments, your car could be taken away. It is a classic balancing act between enjoying a lower cost of borrowing and the potential loss of your cherished property.

On the other hand, an unsecured loan functions without any physical collateral to back it up. Most credit cards and standard personal loans operate under this model. Since the lender lacks the immediate ability to seize your car if you default, they tend to demand higher interest rates and more robust credit histories.

If you run into financial trouble with an unsecured debt, your house won’t be snatched away overnight. However, the consequences aren’t nonexistent. Lenders have the legal right to pursue you in court or even seek a garnishment of your wages to recover what is owed.

Setting the Stage for Your Loan Request

Stepping into a loan application without a roadmap is like driving through a thick Jersey fog without headlights. You might eventually reach your destination, but you’re likely to hit some unexpected bumps along the way. By organizing your affairs beforehand, you can secure more favorable terms and bolster your approval odds.

The key to a smooth process is staying proactive rather than reactive. Many applicants find themselves scrambling for paperwork at the eleventh hour, which only adds unnecessary stress. Taking a moment to tidy up your financial profile can prevent sudden dips in your credit standing.

A little bit of homework goes a long way when dealing with lenders. It isn’t just about proving you can pay them back; it is about presenting the most polished version of your financial self possible. Think of it as a first date where you want to look your absolute best.

Consider these essential steps to ensure your application stands on solid ground:

  • Double-Check Your Paperwork: Before diving in, assemble your identification, latest bank records, and recent income statements. If you’re pledging an asset to secure the loan, ensure you have the legal title or ownership documents ready to go.
  • Analyze Your Debt-to-Income (DTI) Ratio: Lenders act like detectives, calculating what portion of your paycheck is swallowed by existing monthly payments. If that slice of the pie is too large, they might walk away. It’s wise to clear out small balances to improve this ratio before officially applying.
  • Scour Your Credit Report for Mistakes: A single clerical error regarding a late payment can act like a lead weight on your score. Don’t let a typo cost you thousands; use a free service to hunt down and challenge any inaccuracies before you start seeking capital.
  • Look at APRs, Not Only Interest Rates: Don’t let a low interest rate blindside you. The Annual Percentage Rate (APR) is the true metric because it folds in mandatory fees alongside the interest. For example, a 12% rate with zero fees actually beats a 10% rate that carries a $500 charge.
  • Leverage Prequalification Options: Seek out lenders that utilize “soft pulls” for their initial quotes. This clever method allows you to shop around for estimated rates without leaving a lasting scar on your credit report.

Hunting for a lender shouldn’t feel like a blindfolded sprint toward the first hand offering paper. You really need to scrutinize the microscopic details in those contracts. It is incredibly easy to fall into a debt spiral by grabbing an expensive loan out of sheer desperation.

When you act too quickly, you might find that the cumulative interest ends up eclipsing the actual amount you initially took out. It is a bitter pill to swallow when the cost of borrowing outweighs the principal.

Don’t let a low monthly installment blindside you to the true price of your debt. A tiny, manageable payment often acts as a Trojan horse for an extended repayment period. This tactic can end up draining thousands of extra dollars from your pocket through interest alone.

Imagine you secure a $5,000 loan. If that comes with a $100 monthly bill, it looks like a breeze. However, the reality is that you will be tethered to that debt for seven long years.

Avoid the temptation to pepper the market with dozens of applications simultaneously. Every single formal request triggers what experts call a “hard inquiry,” which chips away at your credit standing. It’s like leaving a trail of breadcrumbs that tells every bank you’re running low on fuel.

If you submit five different requests in a single week, lenders will assume you are drowning in financial trouble. Instead of diving into the deep end, utilize prequalification instruments first. This allows you to trim down your options without hurting your score before making any official commitments.
Top-Rated No Credit Check Home Improvement Loans to Fund Your Next Project

By Uncategorized
No credit check home improvement loans

Top-Rated No Credit Check Home Improvement Loans to Fund Your Next Project

Last updated: 2026-10-17

Imagine staring at a kitchen that needs a total overhaul or a ceiling dripping onto your floor. When your credit score is bottoming out, finding the money to fix these issues can feel like trying to catch smoke with your bare hands. Most mainstream banks tend to shut you out before you even get through the front door.

It is a wearying loop of “no” from lenders that leaves many people feeling stranded in their own homes. You want to upgrade your living space, but the standard financial system often plays by rules that seem designed to exclude you. It can be a real headache when your property needs urgent attention.

We have put together this resource for homeowners who need cash for renovations but lack a stellar credit history. Don’t get distracted by the shiny marketing used by every firm in town. Instead, prioritize how quickly you can get your hands on the funds and what the total borrowing limit looks like.

You also want to ensure that browsing different options won’t tank your score. Look for lenders that allow soft credit inquiries during the initial shopping phase. This approach lets you compare rates without any hidden damage to your financial standing as you weigh your various options.

  1. Solar Energy Loan Fund
  2. JetzLoan
  3. SoFi
  4. Upgrade
  5. Best Egg

Our Methodology for Sorting Top Home Renovation Lenders

When we set out to rank these options, our primary goal was to ensure clarity and ease of access. We know that many homeowners facing unexpected repairs are essentially walking a tightrope financially. Therefore, we insisted that any featured provider must allow users to browse interest rates without hurting their credit score via a hard inquiry.

We ignored the old-school obsession with a single, static credit score. Instead, we hunted for companies that weigh a person’s actual capacity to settle a debt more heavily than their history. It is about seeing the human behind the paperwork, ensuring that a bad month doesn’t bar you from necessary home repairs.

Speed is another make-or-break factor in our vetting process. If a bank takes half a month to process a wire, it’s a non-starter when your plumber is standing in your kitchen demanding a down payment by tomorrow morning. We demanded lightning-fast transfers and significant borrowing limits to ensure our readers stay afloat.

Finally, we cross-referenced every company against the current economic climate of 2026. We evaluated whether their core values matched their actions and if their interest rates actually hold up against the competition. Every firm was measured against its deployment of funds, its corporate purpose, and its overall market competitiveness.

Provider Maximum Funding Transfer Speed Credit Inquiry Effect Standout Benefit
Solar Energy Loan Fund Check website Check website No impact Mission-driven
JetzLoan $50,000 As little as 24 hours No impact Fast connection
SoFi Check website Same-day funding Check website No collateral required
Upgrade $50,000 Fast funding No impact Cash back options
Best Egg $50,000 Check website Check website Homeowner discount

Leading Lending Providers for Property Upgrades and Repairs

1. Solar Energy Loan Fund

Solar Energy Loan Fund – solarenergyloanfund.org

This organization functions with a deep sense of compassion, prioritizing the development of resilient and sustainable neighborhoods. They distribute equitable capital to assist both nonprofit groups and individual households in bolstering their economic durability. It is a refreshing departure from the impersonal, cold demeanor typical of large banks that focus solely on credit metrics.

Their primary mission involves funding renovations that promote environmental sustainability and neighborhood stability. If your priority is enhancing local infrastructure or improving housing quality, this purpose-driven model might be your ideal match. It is not merely about injecting cash; it is about fostering lasting community impact.

Navigating the application is designed to be equitable, and checking your eligibility won’t touch your credit score at all. You can explore different paths without the dread of a sudden drop in your rating. This offers a zero-risk way to see if their low-cost financing is a fit for you.

Pros:

  • A mission-centric model that prioritizes community strength.
  • Prequalifying checks will not impact your credit rating.
  • Provides fair capital to nonprofits and households alike.

Cons:

  • Strictly focused on specific ecological and community-based objectives.

2. JetzLoan

JetzLoan – jetzloan.com

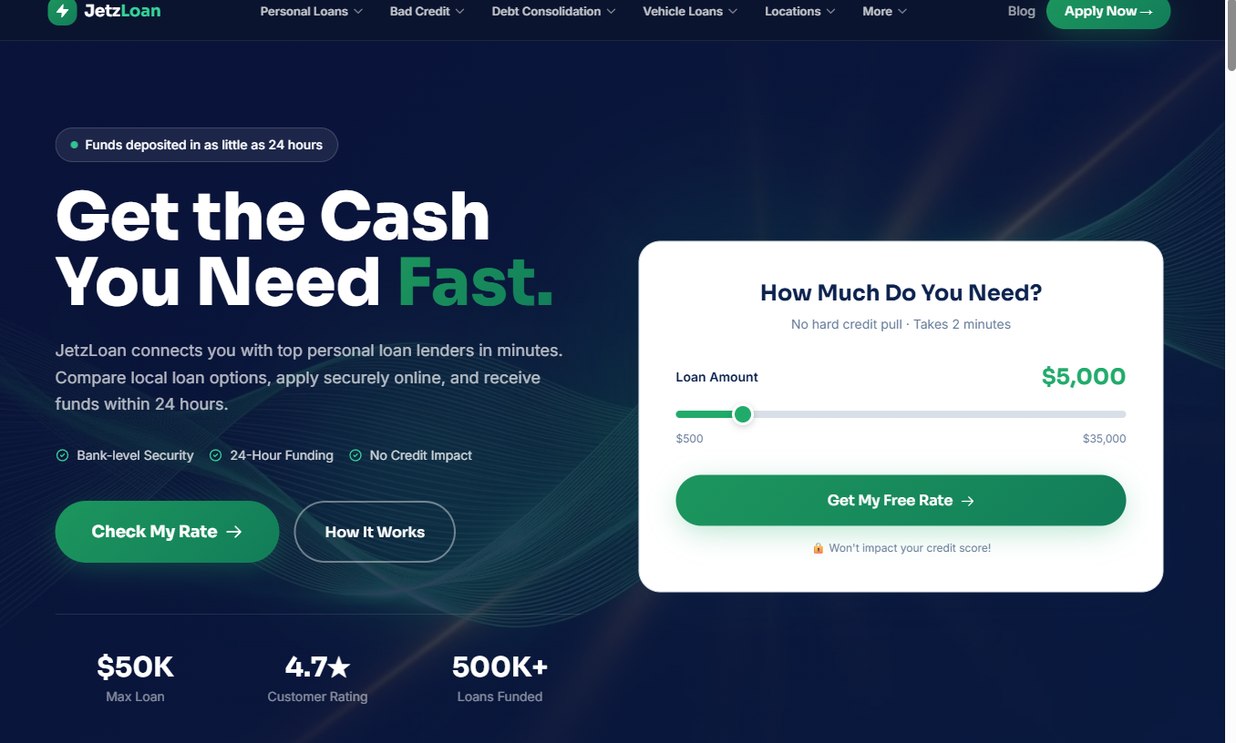
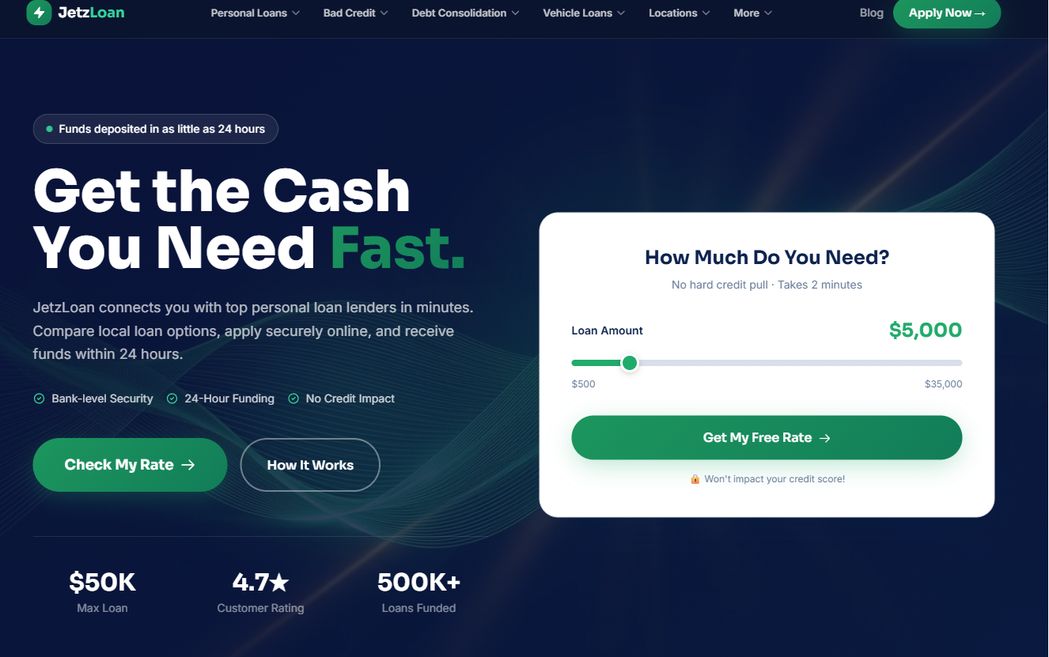
When a home emergency strikes and time is of the essence, JetzLoan jumps into action. They act as a bridge, connecting you with premier personal loan lenders within a matter of minutes. This streamlined system is perfect for homeowners facing urgent maintenance crises who need liquidity immediately.

Speed is the name of the game here, with the possibility of receiving funds in your bank account in as little as 24 hours. Such quick turnaround makes them a top-tier choice if you need to pay a contractor right away to keep work moving. They facilitate loans ranging from $500 up to $50,000.

The platform prioritizes clarity, featuring an application that takes a mere two minutes to complete. You can obtain a rate quote for free without a hard credit inquiry, which is a huge weight off your shoulders. It is a high-velocity solution built for the fast-paced lifestyle of today’s homeowners.

Pros:

  • Lightning-fast funding, potentially arriving within a 24-hour window.
  • No hard credit pull is required to view your rates.
  • A quick application process taking only two minutes.

Cons:

  • The maximum loan limit is capped at $50,000.

3. SoFi

SoFi – sofi.com

SoFi is a heavyweight in the financial sector, boasting a massive suite of tools from mortgages to standard banking. When it comes to upgrading your house, they shine because they often provide same-day funding. This rapid access to cash is a lifesaver during those high-pressure renovation moments.
Because their personal loans do not require collateral, you won’t be losing sleep over putting your residence on the line. This makes the borrowing experience much smoother and less scary for those navigating loans for the first time. It is a sophisticated, tech-forward option for modern users.

Beyond simple loans, they offer a full ecosystem of banking tools, including savings accounts with high yields. If your dream is to consolidate your entire financial life under one digital roof, SoFi is a polished contender. It remains a premium selection for the tech-savvy consumer.

Pros:

  • Availability of same-day funding options.
  • Borrowing does not require collateral.
  • An expansive variety of financial services.

Cons:

  • Eligibility criteria may be more stringent than lenders specializing in bad credit.

4. Upgrade

Upgrade – upgrade.com

Upgrade serves as a versatile financial companion, particularly useful for various home-related expenses. They provide personal loans reaching up to $50,000 with fixed interest rates, ensuring your monthly budget remains steady. This is a perfect fit if you crave the certainty of a consistent monthly payment.

One standout feature of Upgrade is the ability to view your potential rate without dinging your credit score. They also provide unique perks, such as the chance to earn cash back on certain transactions or utilize high-yield savings. It feels like a modernized, refreshed take on the traditional lending model.

The company boasts a massive footprint, serving over 8 million customers and facilitating $50 billion in borrowed funds. This immense scale suggests a highly polished infrastructure capable of handling everything from small purchases to major debt consolidation. It is a dependable, middle-of-the-road choice for most people.

Pros:

  • Fixed rates offer long-term stability for your budget.
  • Check your rates without any impact on your credit score.
  • Includes incentives like savings and cash back.

Cons:

  • The specific terms of personal loans can fluctuate quite a bit.

5. Best Egg

Best Egg – bestegg.com

Best Egg aims to instill financial confidence through an application process that is remarkably simple. They offer personal loans up to $50,000 with both flexible terms and fixed interest rates. This versatility allows you to tailor your debt to align perfectly with your monthly cash flow.

Homeowners may find a special advantage here, as they offer discounts that can lead to their most competitive rates. Additionally, you can use certain household fixtures, such as vanities or cabinets, as collateral to potentially secure better terms. This is a smart way to tap into home equity without a full mortgage.

Boasting an A+ rating from the Better Business Bureau, this company has earned thousands of glowing reviews. Their reputation for being reliable makes them a powerhouse for those seeking peace of mind. They focus on making every step of the process quick and painless.

Pros:

  • Specialized interest rate discounts for homeowners.
  • Possibility of using home fixtures as collateral.
  • Extremely high marks for customer satisfaction.

Cons:

  • You must provide more details to see your specific options.

Navigating the Dangers of Rapid Funding

Picture yourself staring at a decaying porch or a broken window, feeling the sudden urge to fix it at any cost. In these moments of house-related stress, people often rush into agreements without a second thought. This haste can be a slippery slope leading straight into a financial pitfall.

It is vital to ensure that any company offering quick cash is a verified, legitimate business. Before you hand over any personal data, scan the fine print for sneaky, undisclosed charges. You don’t want any unwelcome surprises lurking in the shadows of your loan agreement.

Stay far away from any lender that asks for a large sum of money upfront to process your application. If they demand cash before releasing your funds, run the other way. In the banking world, this is a massive warning sign that something is quite wrong.

While these options are convenient, remember that skipping a credit check doesn’t make the debt vanish into thin air. A soft inquiry might protect your score initially, but the actual obligation will eventually land on your credit report. Debt is still debt, regardless of how it was acquired.

When weighing your options, don’t just focus on whether the monthly installments fit your budget. A small monthly bill often masks a much longer repayment period. This can result in paying thousands of extra dollars in interest over many years.

Grab a calculator and crunch the numbers to find the true price of the borrowing. You need to see the grand total, not just the immediate cost. Once you sign that contract, there is no turning back, so be absolutely certain first.

Top-Rated Loans for Independent Contractors to Fund Your Business

By Uncategorized
Loans for independent contractors

Top-Rated Loans for Independent Contractors to Fund Your Business

Last updated: 2026-10-16

For those navigating the 1099 life, chasing a loan can feel like trying to catch lightning in a bottle. Conventional banking institutions typically demand a mountain of steady, long-term employment history before they even glance at your application. They want stability that the gig economy simply doesn’t offer.

Yet, today’s economic landscape is fueled by the grit of solo operators and freelance specialists. Success in this realm often hinges on finding a financial ally who understands your unique cash flow. Whether you are expanding your empire or just plugging a temporary hole, the right lender makes all the difference.

Selecting a provider involves more than just a simple comparison of interest percentages. You must weigh how quickly the funds actually land in your bank account when things get urgent. Speed is often the name of the game when you’re playing catch-up with your bills.

Don’t forget to investigate whether they prioritize your individual credit rating or the raw earnings of your company. This guide dissects the leading options to ensure you find a fit that matches your specific financial personality. We want you to find a partner that fits your rhythm.

  1. Swoop US
  2. Acorn Finance
  3. FastLendGo
  4. Giggle Finance
  5. Lendesca
  6. Greenbox Capital
  7. Discover

Our Selection Methodology

Our team set out to pinpoint lenders that truly grasp the uphill battles self-employed professionals endure. We didn’t just look at the surface; we dug deep into financing tools like merchant cash advances, factoring for invoices, and SBA-backed programs.

Securing a massive windfall isn’t the only goal when you’re flying solo. For a freelancer lacking a traditional paycheck, simply being able to get a “yes” is the real prize. We prioritized lenders that don’t turn their backs on those without a standard W-2.

We weighed how fast a company can wire funds alongside their willingness to work with imperfect credit histories. If your work is seasonal, a sluggish lender is a liability, no matter how low their interest rates might seem on paper.

Speed is king in the gig economy. A provider that can cut a check in minutes often outweighs a cheaper option that leaves you waiting for weeks. We scrutinized every company to ensure they could support everyone, from those with pristine scores to those rebuilding from bad credit.

Provider Funding Limits Processing Time Eligibility Standards Unique Benefits
Swoop US Refer to website Minutes Variable Ways to save money
Acorn Finance Refer to website Refer to website Good or Bad Credit Soft inquiries for rates
FastLendGo $500 – Refer to website Rapid delivery All credit tiers General and niche loans
Giggle Finance Maximum $15,000 Minutes 1099 workers & Side hustles Loyalty increases up to $20k
Lendesca Maximum $1,250,000 Weeks Freelancers & SBA focus Specialists in SBA
Greenbox Capital $3,000 – $500,000 1 day minimum Low or Bad Credit Merchant Cash Advances
Discover Refer to website Refer to website Refer to website Perks via credit cards

Top-Tier Lending Solutions for Independent Professionals

1. Swoop US

Swoop US – swoopfunding.com

Think of Swoop US as a financial matchmaking service. Instead of a one-size-fits-all approach, this platform bridges the gap between your entrepreneurial goals and a massive pool of lenders. It isn’t just about standard bank loans; you can explore everything from equity stakes to specialized grants or commercial real estate financing.

Searching for capital can feel like wandering through a dark forest. This service acts as a compass, allowing you to scout various options to slash overhead costs and fuel your expansion. It is an ideal ecosystem for established companies that require a multifaceted financial toolkit rather than a simple loan.

Advantages:

  • A wide spectrum of options, including tax credits and grants.
  • Opportunities to reduce your overall business outlays.
  • A rapid matching mechanism to get things moving.

Disadvantages:

  • Borrowers with poor credit may encounter steeper interest rates.
  • Loan ceilings might be restricted for certain credit levels.

2. Acorn Finance

Acorn Finance – acornfinance.com

If your livelihood depends on home renovation contracts, Acorn Finance is your best friend. They realize that a client’s desire for a new kitchen or a backyard pool often requires a significant financial boost. This platform helps you provide financing to your patrons without the administrative headache.

The real magic lies in their “soft” inquiry feature. You can peek at personalized interest rates without leaving a dent in your credit score. It’s a transparent way to offer value to homeowners, ensuring your services remain affordable for them while keeping your reputation pristine.

Advantages:

  • Contractors are never charged any dealer fees.
  • Checking rates won’t impact your credit standing.
  • Accommodates both stellar and challenged credit histories.

Disadvantages:

  • The service is tailored specifically to the home improvement niche.
  • The responsibility for completing the financing lies with the client.

3. FastLendGo

FastLendGo – fastlendgo.com

Life happens fast, and sometimes you just need cash in hand. FastLendGo provides a diverse array of personal financing paths for those sudden moments. Their scope is broad, covering everything from fixing a broken car to paying for dental work or even financing a new motorcycle.
The platform functions as a rapid comparison engine for local personal loans. It doesn’t matter if your credit is pristine or if you are currently wrestling with a low score; they have a product designed to meet you exactly where you stand. It is an uncomplicated way to boost your liquidity.

Advantages:

  • Versatile usage, ranging from automotive to medical needs.
  • Solutions available for numerous credit tiers.
  • A streamlined online comparison experience.

Disadvantages:

  • Primarily geared toward personal needs rather than scaling a business.
  • Upfront details on specific rates and terms are not always visible.

4. Giggle Finance

Giggle Finance – gigglefinance.com

The traditional banking world often feels like a closed club for the 1099 workforce. Giggle Finance was built to break those doors down. They focus on the side-hustlers and gig workers who are the lifeblood of the modern economy, offering a friendly alternative to the big, impersonal institutions.

When a sudden opportunity or an unexpected bill hits, speed is king. You could potentially secure up to $15,000 in a mere few minutes. If you become a regular user, that ceiling can rise to $20,000. It is a lightning-fast solution for those who cannot afford to wait.

Advantages:

  • Rapid disbursements that can happen in minutes.
  • Purpose-built for the self-employed and gig economy workers.
  • Higher borrowing limits for loyal, returning clients.
Disadvantages:

  • Total loan amounts are generally lower than commercial loans.
  • The high speed of funding often results in higher interest costs.
5. Lendesca

Lendesca – lendesca.com

Navigating the world of SBA loans can feel like trying to walk through quicksand due to the endless paperwork. Lendesca has revamped this archaic process. They help owners transition from the initial application to receiving funds in weeks, bypassing the months of waiting usually required by traditional lenders.
They also offer specialized products, such as cash advances specifically for freelancers. These tools look at your actual cash flow to determine eligibility, rather than just relying on a rigid corporate credit history. For those aiming for massive growth through government-backed channels, they are a powerhouse.

Advantages:

  • Deep expertise in managing the complex SBA landscape.
  • A much faster turnaround than standard SBA lenders.
  • Freelance cash advances that prioritize your real-time cash flow.

Disadvantages:

  • SBA products typically necessitate a credit score around 680.
  • The application process remains more involved than simple cash advances.

6. Greenbox Capital

Greenbox Capital – greenboxcapital.com

When your business needs a sudden infusion of working capital, Greenbox Capital steps into the ring. They specialize in alternative methods like Merchant Cash Advances. This allows you to repay the funds using a small slice of your daily or weekly sales, making the cost feel much more manageable.

Their reach is vast, serving various industries across Canada, Puerto Rico, and the United States. Because they can provide funding in as little as a single business day, they are the ideal partner for grabbing a sudden market opportunity or covering an unexpected inventory shortage.

Advantages:

  • Incredibly fast turnaround, sometimes within one business day.
  • A wide lending spectrum from $3,000 to $500,000.
  • Repayment terms that adapt via Merchant Cash Advances.

Disadvantages:

  • Merchant Cash Advances can carry higher costs than standard loans.
  • Repayment amounts fluctuate based on your varying sales volume.

7. Discover

Discover – discover.com

Discover stands as a massive pillar in the consumer finance landscape. They bring a sense of permanence and wide-scale acceptance that small, niche lenders simply cannot provide. With their cards accepted by 99% of merchants, they are a seamless choice for both your personal life and daily business expenses.

Their product line is diverse, offering everything from credit cards with great cashback to various personal loan options. For a contractor looking for a mainstream partner that provides top-tier security and stellar customer support, they are a rock-solid choice.

Advantages:

  • Near-universal acceptance of their credit products.
  • Robust financial insights and high-end security features.
  • Generous cashback rewards on specific spending categories.

Disadvantages:

  • Lacks the specialized nuances required by 1099 contractors.
  • Requires meeting standard credit eligibility requirements.

Sizing Up Your Financing Options

Don’t let a small monthly installment fool you into a bad deal. It’s a common pitfall where a seemingly cheap payment structure actually hides a massive total debt burden. You might find yourself paying a king’s ransom once the entire term concludes.

Before you sign anything, demand to see the grand total of every dollar you will return to the lender. This number reveals the genuine price of the cash you are borrowing. Seeing the full picture prevents nasty surprises when the final payments come due.

Matching your debt to your cash flow is the secret sauce of successful borrowing. Many freelancers stumble by picking a loan that doesn’t dance to the beat of their specific business rhythm. You need a structure that breathes with your revenue.

For those with seasonal work, a Merchant Cash Advance might seem like a lifeline because it adjusts to your sales volume. However, those “easy” terms can turn into a financial headache when business slows down. Ensure your repayment schedule mirrors the natural ebbs and flows of your income.

Best Ways to Secure Fence Financing for Your Next Backyard Upgrade

By Uncategorized
Fence financing

Best Ways to Secure Fence Financing for Your Next Backyard Upgrade

Last updated: 2026-10-17

Dreaming of a fresh landscape makeover can feel like chasing a ghost. You see the perfect boundary in your mind, yet that sudden, heavy invoice is a tough pill to swallow. It is common to stare at decaying timber and question if your savings can handle the blow today.

The mismatch between a craving for seclusion and a modest bank statement is where many dreams go to die. Finding capital isn’t merely about hunting down the smallest interest percentage. You must weigh how fast cash arrives against the risk of your credit score taking a massive hit during the hunt.

If the money doesn’t arrive soon, your builder might vanish to another site. This leaves your property feeling naked and vulnerable for another long year. We aim to clear the fog so you can choose the smartest path to pay for your new barrier.

  1. Guerrero Fences
  2. FenceUSA
  3. JetzLoan
  4. Allied Fence
  5. Perimtec

Finding the Right Funding Strategy for Your Property Boundary

Pinpointing the top-tier lenders in 2026 required a heavy emphasis on how quickly money hits your account and how easy it is to apply. If a company forces you to wade through a thicket of bureaucracy, they aren’t the right fit when a fallen tree is leaning against your old fence. We sought out entities that streamline the approval journey, whether they handle the money themselves or work through external loan facilitators.

Our team scrutinized the specific hurdles within the signup experience. We measured the interval between the initial click and actual liquidity, alongside the intensity of the credit check. It is vital to understand how these moves affect your financial standing. In a digital age where keeping your data private is a top priority, having the option to check your eligibility via a “soft pull” is a game-changer.

This non-binding check lets you glimpse your estimated monthly installments and interest percentages without a formal inquiry that might ding your score. We placed a premium on lenders that let you window-shop for deals without causing a sudden drop in your credit rating. It’s better to be safe than sorry when dealing with the banking giants.

As you weigh your various financial paths, keep these core concepts in mind:

  • Savings vs. Debt: Are you dipping into your cash reserves (liquidity) or using your upcoming wages to cover the cost (leverage)?
  • Security and Collateral: Many fencing loans are unsecured, meaning your house stays off the table, unlike the risks associated with a HELOC.
  • The Hidden Price of Interest: A promotional 0% rate is a gift, but only if the debt is wiped out before the grace period ends. Missing that deadline can trigger “back-dated” interest, which can feel like a gut punch to your wallet.

Provider Maximum Limit Speed of Funds Credit Effect Loan Specifics
Guerrero Fences see site see site Pre-qualify available 0% interest for 6 months
FenceUSA $500+ see site see site Flexible plans available
JetzLoan $50,000 24 hours No hard credit pull Personal loans
Allied Fence see site Varies by project Varies by project Custom financing options
Perimtec see site see site No credit impact check Through Wisetack

Leading Fence Financing Solutions for 2026

GUERRERO FENCES

Guerrero Fences – guerrerofences.com

Navigating the Texas terrain requires a local touch, and Guerrero Fences delivers exactly that. From the bustling San Antonio area down to the Rio Grande Valley, they truly know the soil. They provide everything from standard chain link to elegant wrought iron and classic wood setups.

Their financial strategies are tailored specifically for the unique lifestyle of Texans. If you are dreaming of a sturdy security barrier or a rustic cedar privacy screen, they make it happen. It is a breath of fresh air for those wanting top-tier work without a massive, immediate financial blow.

Rather than breaking the bank all at once, you can spread out the investment. For example, their 0% interest plan for 6 months is a lifesaver if you just got a tax refund or a seasonal bonus. It keeps your cash liquid while your new fence goes up without delay.

Advantages:

  • Six-month window with 0% interest available.
  • A diverse inventory, featuring hurricane-grade chain link.
  • Extensive service coverage across major Texas hubs.

Disadvantages:

  • Accessing the 0% promotional rates likely requires specific credit standing.

FENCEUSA

FenceUSA – fenceusa.com

With more than 45 years of experience under their belt, FenceUSA is a true industry veteran. They serve the tri-state area, covering Pennsylvania, Delaware, and Southern New Jersey. Because they handle the entire lifecycle—from installing decks to fitting railings—they are a comprehensive, one-stop shop.

In an era of “fly-by-night” contractors, their long history is a badge of honor. When you choose a company with four decades of stability, you aren’t just buying a perimeter; you are buying the peace of mind that your warranty will actually be honored years down the road.

They offer several manageable payment schedules that won’t break your budget. Whether your heart is set on vinyl, aluminum, or chain link, the financing remains predictable. They even allow for milestone-based payments, meaning you pay as construction reaches specific phases.

Advantages:

  • Decades of proven, reliable industry history.
  • Adaptable payment plans for various fence styles.
  • Wide service area across the tri-state region.

Disadvantages:

  • Availability of financing may depend on the specific type of project.

JETZLOAN

JetzLoan – jetzloan.com

JetzLoan serves as a high-speed conduit connecting consumers with premier personal loan lenders. Unlike a traditional bank that might leave you waiting weeks for manual underwriting, this platform is built for speed. It is perfect for those who need funds yesterday before the weather turns or your preferred installer gets busy. (jetzloan.com)

The platform is incredibly user-friendly, helping you weigh local options in just a few minutes. A major advantage here is the “no hard credit pull” policy during the initial browsing stage. You can hunt for the best deals without worrying about a sudden dip in your credit score.

In fact, you can evaluate up to five different loan scenarios without any impact on your report. Your credit remains untouched until the very moment you decide to commit to an offer. This gives you the freedom to shop around aggressively for the best terms.

Advantages:

  • Rapid funding, often arriving within a single 24-hour period.
  • Generous loan ceilings reaching up to $50,000.
  • No credit score penalty during the initial rate comparison.

Disadvantages:

  • As an intermediary, final rates are heavily tied to your personal credit profile.

ALLIED FENCE

Allied Fence – alliedfence.com

Since 1953, Allied Fence has been a powerhouse in the Georgia market. With a massive portfolio of over 100,000 successful installations, they are the real deal. They specialize in elevating curb appeal and security through bespoke designs that are built to withstand the test of time.

For homeowners craving a high-end, custom aesthetic but needing to manage monthly cash flow, they offer professional financing. Their deep-rooted history provides a level of stability that makes long-term payment plans feel much safer and more secure.

If your project involves intricate wrought iron or heavy stone pillars, they can integrate financing directly into your custom design. They understand that a complex, large-scale build requires a similarly sophisticated financial strategy to keep things running smoothly.

Advantages:

  • Over 70 years of established professional skill.
  • A massive track record exceeding 100,000 completed jobs.
  • Specialists in high-end security and custom architectural designs.

Disadvantages:

  • The focus on custom work might lead to higher initial project costs.

PERIMTEC

Perimtec – perimtec.com

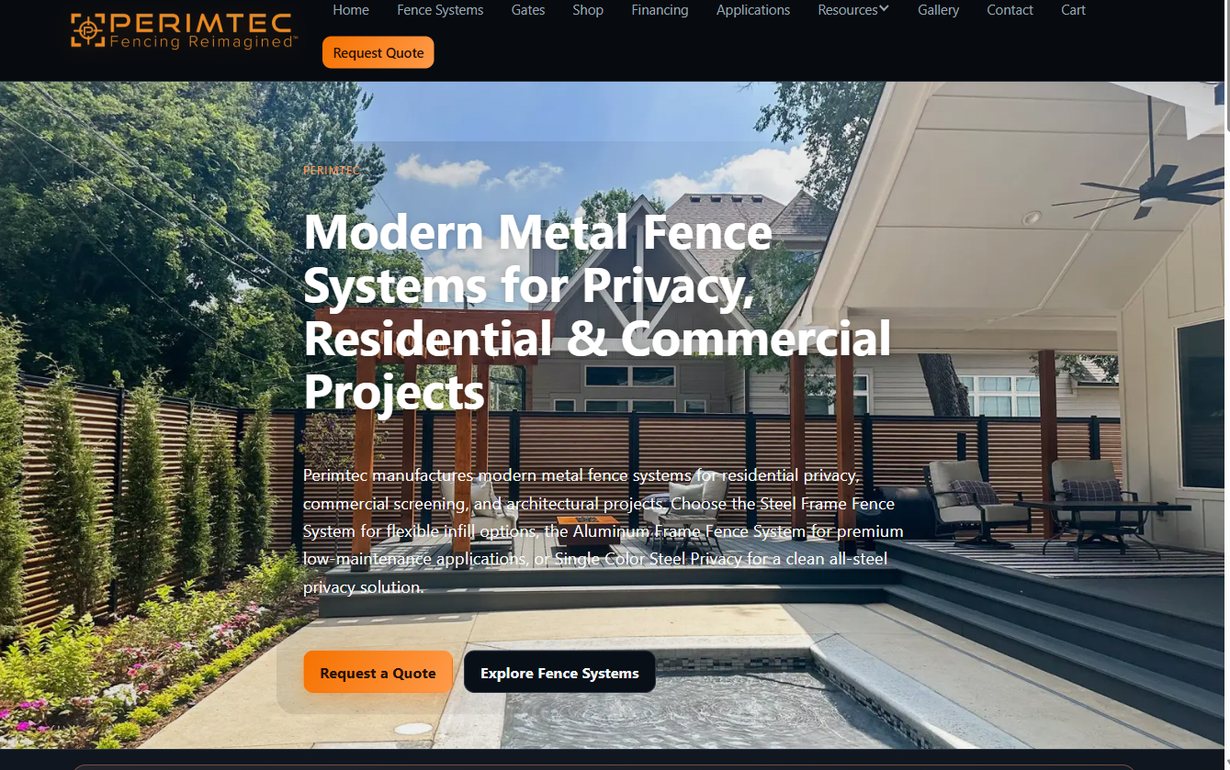
Perimtec is the premier choice for those who want their property to make a modern architectural statement. They specialize in luxury metal systems, including aluminum and steel frame options. These aren’t just boundaries; they are intentional design elements that complement a home’s aesthetic.

This is particularly popular for contemporary builds or luxury renovations where a standard wooden fence might look out of place. To make things easy, they have partnered with Wisetack. This allows you to pre-qualify for your metal system financing without any risk to your credit score.

Securing a premium installation is incredibly straightforward. The process is seamless; you can often receive a digital link on your smartphone during your initial consultation, allowing you to pick your terms right then and there.

Advantages:

  • Expertise in high-end, contemporary metal fencing.
  • Integrated Wisetack technology for credit-safe pre-qualification.
  • Excellent for both commercial sites and residential privacy.

Disadvantages:

  • Custom metal designs often come with a higher price tag than wood.

Step-by-Step: How to Secure Your Fence Financing

Navigating the financial side of a renovation requires a methodical approach to avoid unnecessary debt or delays. Follow these steps to ensure you are prepared before the first post is even dug:

  1. Calculate the Total Project Cost: Do not just look at the material price. Include tax, delivery fees, and labor. If you are adding a gate or a custom entryway, factor those in separately as they often carry higher premiums.
  2. Check Your “Soft” Score: Before applying for anything, check your credit score through a free service. This gives you a baseline. If your score is below 650, you may want to focus on lenders like JetzLoan or specialized contractor financing rather than traditional bank loans.
  3. Request Multiple Quotes: A fence is a physical product, but the price is often negotiable based on the payment method. Ask installers if they offer a discount for cash/check versus financing, or if they have a preferred lender that offers better rates.
  4. Review the “Fine Print” on Interest: Look specifically for “deferred interest” clauses. If you choose a 0% interest plan but fail to pay the balance in full by the deadline, you might be charged interest on the entire original amount from day one.

Steering Clear of Loan Traps

Finding the right financier is a bit like finding a good pair of boots; it depends entirely on where you are walking. If your main goal is keeping your monthly bills as slim as possible, you might be tempted by a 0% interest deal that lasts a few months.

However, these short-term perks aren’t for everyone. If you are tackling a massive commercial installation that requires a mountain of cash, a standard personal loan might actually be your best friend. It’s all about matching the tool to the task at hand.

Don’t let a tiny monthly installment blindside you. A payment that looks easy on paper can become a heavy burden if the term stretches to 72 months rather than 24. You might find yourself paying way more for that cedar or chain-link than the initial estimate implied.

It is a classic blunder to ignore the grand total of the debt. Always hunt down the “total amount payable” figure before signing anything. A $5,000 fence project with a $50 monthly payment sounds like a dream, until you realize you’re still paying for it a decade from now.

You also need to know who is actually holding the bag when it comes to your money. It is vital to distinguish whether your credit is tied directly to the fence installer or an external entity.

External providers like Wisetack or JetzLoan often bring more versatility to the table. On the other hand, direct financing is usually woven tightly into your specific service agreement. This distinction is vital for your peace of mind.

Imagine this: your contractor vanishes overnight, but the lender still wants their cut. If you use a third party, they will still demand payment even if the company folds. Understanding this nuance will save you from massive headaches during the build or when dealing with future warranty issues.

The Best Options for Plumbing Financing and Repair Loans in 2026

By Uncategorized
Plumbing financing work repairs

The Best Options for Plumbing Financing and Repair Loans in 2026

Last updated: 2026-10-17

When a pipe bursts in the middle of a Tuesday night, the last thing a homeowner wants to contemplate is the sudden weight of a massive repair bill. Financial stress often compounds the physical mess left behind by a leaking water heater or a collapsed sewer line. Finding a way to spread those costs out can be a lifesaver.

A sudden emergency doesn’t just damage your drywall; it disrupts your emergency fund. You might find yourself dipping into retirement accounts or high-interest credit cards if you aren’t prepared. Dealing with water damage is hard enough without having to worry about how you will pay for the cleanup and the repairs.

Choosing a financing route for home repairs requires looking beyond just the monthly payment. You should consider how quickly the funds arrive and what kind of credit scrutiny is required. It is also worth checking whether the lender is a specialized service or a broad financial institution.

For example, a specialized plumbing lender might offer “no interest” terms to encourage immediate repairs. Conversely, a traditional bank might offer a lower APR but require a mountain of paperwork and a much longer approval window. This guide breaks down the top four contenders for your plumbing project needs.

  1. Team Austin
  2. FastLendGo
  3. Fort Worth Repipe
  4. First Bank

How These Repair Financing Providers Were Evaluated

The selection process focused heavily on the intersection of immediate accessibility and specialized service. For plumbing emergencies, speed is often the most critical variable. A lender that takes a week to process a request is useless when your basement is currently turning into a swimming pool.

We prioritized providers that offer clear pathways to quick approval. The goal was to focus on those that minimize the “time-to-cash” metric during a crisis. If you are staring at a flood, you need a solution that moves as fast as the water is rising.

We also looked at the diversity of the offerings. Some providers focus on the specific needs of homeowners facing large-scale replacements, like a full repiping of a 2,500-square-foot home. Others are better suited for smaller, urgent repairs like a clogged main line or a faulty shut-off valve.

The aim was to identify which entities provide the most transparent and flexible options for various credit profiles and project scales across the country, from the Midwest to the Sun Belt. We wanted to see who actually delivers when the pressure is on.

Provider Loan Amounts Funding Speed Credit Requirements Terms/Features
Team Austin See site See site See site Comfort now, pay over time
FastLendGo $500 – $5,000+ Fast access Varies (Bad to Great) Personal loans available
Fort Worth Repipe See site See site See site 18 months no interest if paid in full
First Bank See site See site See site Business and Personal options

Understanding the Different Types of Repair Financing

Before selecting a provider, it is vital to understand the mechanics of how these funds are delivered. Not all financing is created equal. The structure of the loan can impact your long-term financial health just as much as the interest rate.

Unsecured Personal Loans

These are common with providers like FastLendGo. Because the loan is not backed by an asset like your house, the approval process is significantly faster. You won’t have to deal with a home appraisal or a title search, which makes this ideal for a sudden leak.

However, because the lender takes on more risk, the interest rates may be higher than a secured loan. This is especially true if your credit score is in the “Fair” or “Poor” range. You are essentially paying a premium for the convenience and speed of the cash.

Deferred Interest Promotions

Often seen in specialized service offers like those from Fort Worth Repipe, these are “buy now, pay later” models. They are incredibly powerful tools for managing cash flow. If you can manage to pay the full balance within the 12, 18, or 24-month promotional window, you effectively receive an interest-free loan.

This is the most cost-effective way to finance a major repair, provided you have the discipline to meet every single monthly payment on time. If you miss a deadline, the savings vanish, often replaced by heavy interest charges applied retroactively.

Home Equity-Based Financing

For massive renovations—such as a complete overhaul of a home’s water heating system and main lines—homeowners often look toward traditional banking institutions or lines of credit. These are secured by your property. The primary advantage is the extremely low interest rate.

The drawback is the risk: if you cannot repay the loan, your home is the collateral. This is generally a “planned” financing route rather than an “emergency” route. It requires patience, documentation, and a clear long-term plan for repayment.

Top-Rated Plumbing Financing Ranking

1. Team Austin

Team Austin – teamaustin.com

Serving the Southeastern Wisconsin area, this provider specializes in high-stakes home comfort. They tackle everything from plumbing to electrical work, ensuring that their financing options match the scale of the job. It is a comprehensive approach for those who need a full system overhaul rather than just a quick fix.

For example, if a homeowner is dealing with a failing furnace and a leaking water heater simultaneously, Team Austin’s ability to bundle these services with integrated financing provides a streamlined experience that a solo plumber might not offer. It keeps the headache to a minimum.

Their philosophy centers on making big, expensive fixes easy on a household budget. They focus on craftsmanship and integrity, which suggests a high level of professional accountability. This is an ideal choice for Wisconsin homeowners who want a single point of contact for both the work and the payment.

Pros:

  • Comprehensive service covering HVAC, plumbing, and electrical
  • Established presence with a massive library of five-star reviews
  • Flexible plans designed for large-scale home improvements

Cons:

  • Geographically limited to the Southeastern Wisconsin region

2. FastLendGo

FastLendGo – fastlendgo.com

For those who need cash in hand to solve a plumbing crisis, FastLendGo acts as a versatile financial partner. They offer a wide range of personal loans that can be tailored to the specific amount required for a repair. It is a digital-forward solution for the modern homeowner.

Instead of waiting for a banker to review a physical file, the digital application process allows you to secure funds often within the same or next business day. This speed is vital when you are dealing with a crisis that cannot wait for a scheduled appointment.

This provider is particularly useful if your credit history isn’t pristine. They offer pathways for individuals with bad credit, as well as options for those with high incomes. Whether you need $500 for a minor leak or $5,000 for a more significant issue, they provide a streamlined comparison process.

Pros:

  • Broad range of loan amounts from $500 upwards
  • Options available for various credit scores, including bad credit
  • Quick online comparison of local personal loan options

Cons:

  • Primarily a loan facilitator rather than a direct service provider

3. Fort Worth Repipe

Fort Worth Repipe – fort-worth.repipe.com

This specialist is the heavy hitter for homeowners in the Texas region facing major repiping needs. They focus on the long-term health of the home, tackling issues like low water pressure, rusty water, and pinhole leaks in older copper piping. Their service is designed to be efficient.

They often complete whole-home projects in just one or two days. This minimizes the disruption to your daily life and business operations. It is a fast way to fix a problem that could otherwise haunt your home for years.

They offer specific seasonal incentives that can make a massive project much more palatable. For instance, their 18-month interest-free window provides a significant cushion for families. If a repiping job costs $6,000, a homeowner can break that down into manageable monthly chunks without the compounding weight of interest.

Pros:

  • Specialized 18-month interest-free period if paid in full
  • Rapid deployment with 1-2 day project completions
  • High customer satisfaction regarding crew punctuality and quality

Cons:

  • Highly localized to the North Texas area

4. First Bank

First Bank – firstbank.com

When a plumbing issue is tied to a larger commercial enterprise or a complex real estate situation, a traditional banking structure often provides the necessary depth. This institution offers a wide spectrum of services, from personal loans to complex agricultural and business financing.

This makes them a unique player compared to the specialized “quick-fix” lenders mentioned above. They are best suited for individuals who prefer the stability of a formal banking relationship. Their platform is built to handle diverse needs, including wealth management and business banking.

It is less about the “emergency repair” and more about structured, long-term financial management. If you are a landlord needing to finance a major plumbing overhaul across an entire apartment complex, a traditional institution like First Bank offers the scale and professional oversight required for such high-value transactions.

Pros:

  • Extensive range of financial products including mortgage and business
  • Robust online banking and security features
  • Established institutional stability for large-scale financing

Cons:

  • Likely requires more rigorous documentation and longer approval times

Step-by-Step: How to Secure Your Repair Financing

Navigating the paperwork during a plumbing emergency can be overwhelming. To ensure you get the best deal and avoid unnecessary delays, follow this structured approach:

  1. Get a Detailed Written Estimate: Before applying for a loan, ensure the plumber provides a line-itemed estimate. You need to know exactly what you are borrowing for. Is it just the parts, or does it include labor, disposal fees, and permit costs? A vague estimate can lead to a loan that is too small to cover the actual cost.

  2. Check Your Credit Score: Even if you intend to use a provider that accepts bad credit, knowing your score allows you to compare offers accurately. A high score might unlock a 7% APR, while a lower score might jump to 25%. Knowing this difference helps you decide if the “speed” of a quick loan is worth the extra cost.

  3. Compare the APR, Not Just the Monthly Payment: Lenders love to highlight a low monthly payment. However, if that payment is spread over 72 months, you might end up paying double the original cost of the repair. Always ask for the Annual Percentage Rate (APR) to see the true cost of the debt.

  4. Verify the Warranty: Never finance a repair unless the contractor offers a written warranty on both parts and labor. There is nothing worse than paying off a loan for a new water heater only to have it leak again three months later, leaving you with debt and no working appliance.

Avoiding Common Financing Pitfalls

The most common mistake people make is ignoring the fine print regarding interest rates. A “no interest” period sounds like a dream, but if you miss a single deadline, the interest can skyrocket. In many deferred interest contracts, if you fail to pay the full balance, the lender can back-charge you interest from the original purchase date.

Always ensure you have a clear understanding of the repayment schedule before signing anything. Another trap is choosing a lender based solely on the speed of approval without checking their reputation. A quick loan is only helpful if the money is used effectively.

It is vital to verify that the plumber’s work is covered by a warranty, so you aren’t financing a repair that fails a month later. A cheap, fast repair that needs to be redone is a double financial blow. Finally, do not feel pressured to take the maximum amount offered. You should only borrow what is strictly necessary for the job at hand.

Best Mortgage Rates for illinoischicago illinois Homebuyers in 2026

By Uncategorized
Illinoischicago illinois

Best Mortgage Rates for illinoischicago illinois Homebuyers in 2026

Last updated: 2026-10-16

Navigating the financial landscape of Chicago often feels like battling a sudden Lake Michigan gale without any proper protection. Whether you’re facing a sudden mechanical failure while cruising down Lake Shore Drive or struggling to merge several high-interest debts, the goal isn’t just obtaining liquidity. It’s about securing your mental well-being and emotional stability.

In a metropolis where expenses fluctuate wildly between the dense skyscrapers of the Loop and the vibrant North Side, having liquid assets is vital. You require this agility to manage monthly bills and simultaneously foster your long-term wealth. Locating a provider that truly grasps your unique circumstances is the vital initial move toward stabilizing your economic future.

Selecting a creditor requires much more than just eyeing the immediate lump sum hitting your bank account. You must carefully balance interest costs, the eventual influence on your credit rating, and the actual speed of fund disbursement. A quick fix for today’s crisis could easily trigger a tomorrow’s headache if you fail to scrutinize the fine print.

This guide streamlines the selection procedure for residents throughout the greater Chicago metropolitan region. We explore various avenues, from brief credit options to extended financing solutions, along with clever tactics for constructing a robust credit history from scratch.

  1. GoCredit
  2. OppLoans
  3. IllinoisLoansToday
  4. SAIL Loans
  5. SoFi

Evaluating Your Lending Options in the Windy City

Our team crafted this comparison by gauging how easily Illinois locals can access capital. We scrutinized how each firm interacts with various credit backgrounds. This includes individuals seeking a clean slate and those in desperate need of immediate cash. It wasn’t simply a matter of how many people get a “yes.”

We poked and prodded the entire digital journey, from the first click on a smartphone to the moment money lands in your pocket. Our primary focus fell on honesty and velocity. In a bustling metropolis like Chicago, nobody has the luxury of sitting around for weeks waiting for a verdict.

Think about a commuter facing a sudden train fare crisis or a shopkeeper whose machinery just gave out. Time is of the essence. We gave top marks to providers offering straightforward contracts and niche tools like credit enhancement or larger personal loans. We also hunted for sneaky fees, such as the way a hard credit check might momentarily nudge your FICO score downward.

We also investigated if companies use “soft pulls” when you check rates. This method lets you scout possibilities without any danger to your financial reputation. Mastering these tiny nuances can prevent a massive headache down the road.

Provider Loan Range Credit Influence Transfer Speed Ideal Use Case
GoCredit $4,000 maximum Improves Score Rapid Decision Score Improvement
OppLoans $500 to $5,000 Zero FICO Change Same-day service Low Credit Scores
IllinoisLoansToday $500 to $50,000 No Credit Effect Instant Results Finding Matches
SAIL Loans $4,000 maximum Improves Score Rapid Decision Score Improvement
SoFi Check website Check website Check website Full Banking Services

Navigating the Financial Regulations in Illinois

Before ink touches paper on a contract, you must grasp the legalities governing your specific region. Our state maintains strict statutes designed to shield consumers, particularly concerning the ways creditors function and the rates they charge. Navigating the digital marketplace often feels like wandering through a fog when complex jargon like the Annual Percentage Rate (APR) starts appearing on every screen.

It is vital to realize that APR differs significantly from a standard interest rate. While the base rate merely dictates the cost of your principal sum, the APR incorporates various service fees and extra charges. Think of it as the full truth, painting a much clearer image of the actual expense you will incur throughout the life of the loan.

If a quick cash injection is needed for a sudden crisis, a steep APR might feel manageable if the repayment window spans only 30 days. However, should you finance a big-ticket item, such as a pre-owned car from a Naperville dealership, those high rates can quickly turn into a crushing weight. Always pose this question: “What is the total dollar amount I will have paid back by the end of this term?”

That particular inquiry carries more weight than any monthly installment figure a dealer might highlight. Getting caught up in the small monthly cost is a classic trap that frequently leads people to shell out far more capital than they ever planned.

Mistakes to Steer Clear of During the Loan Process

Even the most cautious residents living in Chicago can stumble when hunting for fast cash. Slipping into these financial traps can cost you a fortune in the long run.

A wise borrower knows that a small oversight today might lead to a massive hole in their pocket tomorrow. It is better to be safe than sorry when navigating the complex waters of personal finance.

  • The Cycle of Debt: You might find yourself trying to settle old obligations using high-interest, short-term credit. If that new monthly installment is too steep, you are essentially robbing Peter to pay Paul. Always ensure any borrowed funds fit snugly within your existing monthly budget.
  • Overlooking the “Full Cost of Borrowing”: Banks often market their services using “low monthly payments” to sweeten the deal. For example, a $1,000 loan with $50 monthly payments seems manageable until you realize the two-year term brings the total to nearly $1,200. Always weigh the total repayment amounts between different lenders.
  • Trusting “No Credit Check” Promises Blindly: Many companies claim they won’t check your credit when providing an initial quote. While this prevents a temporary dip in your score during your research, most legitimate lenders will still execute a hard credit inquiry when you officially apply to finalize your contract.

Top-Rated Lending Options for Illinois Borrowers in 2026

1. GoCredit

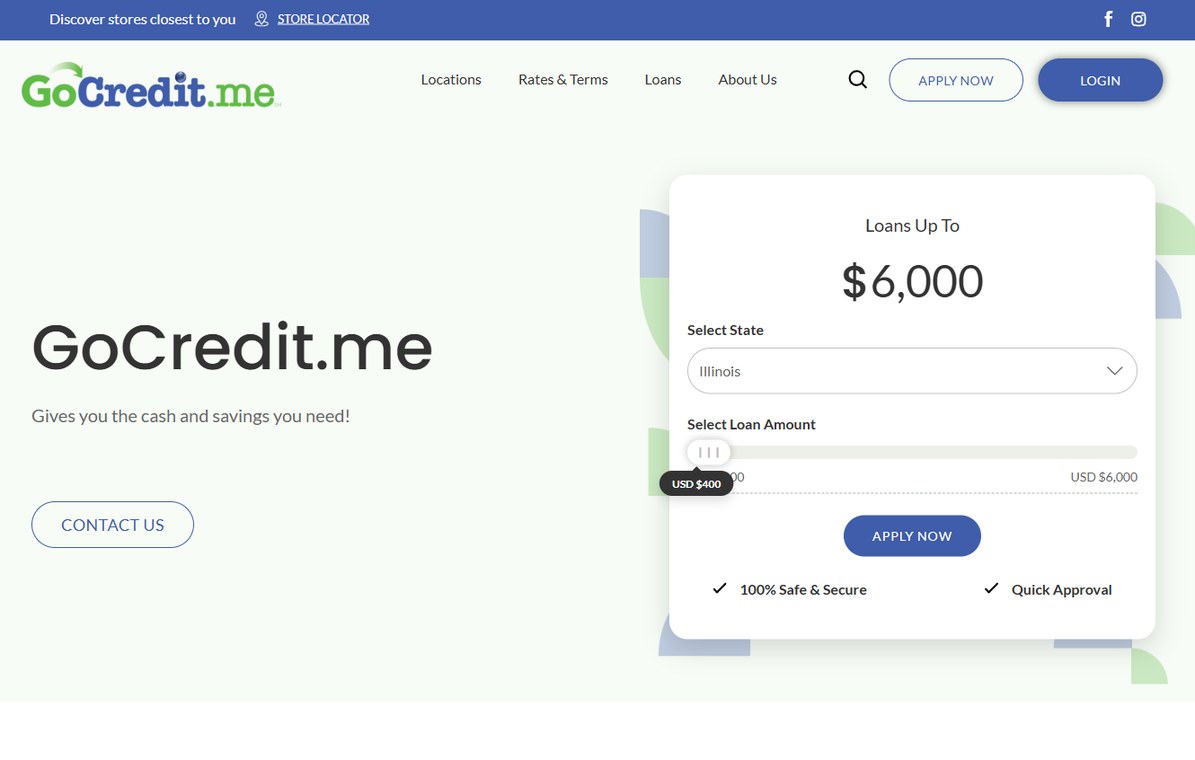
GoCredit – gocredit.me

GoCredit operates with a very particular strategy within the Illinois market. Rather than providing a simple cash injection, they provide installment loans meant to boost your credit profile while simultaneously helping you set aside money. They utilize a “forced savings” method, where a slice of your loan stays in a dedicated account, only to be handed back to you once you have fully cleared the debt.

If you feel like you are treading water financially, this path might be a lifesaver. Utilizing these credit-building loans is like planting a seed for your future self. You are building a cushion that will be waiting for you when life inevitably throws a curveball. This is a perfect fit for downtown Chicago students or tech professionals with steady paychecks but thin credit files.

Pros:

  • Simultaneously improves credit standing and personal savings.
  • Rapid approval makes getting money easy.
  • Borrowers can access up to $4,000.

Cons:

  • Funding is capped at a modest $4,000.

2. OppLoans

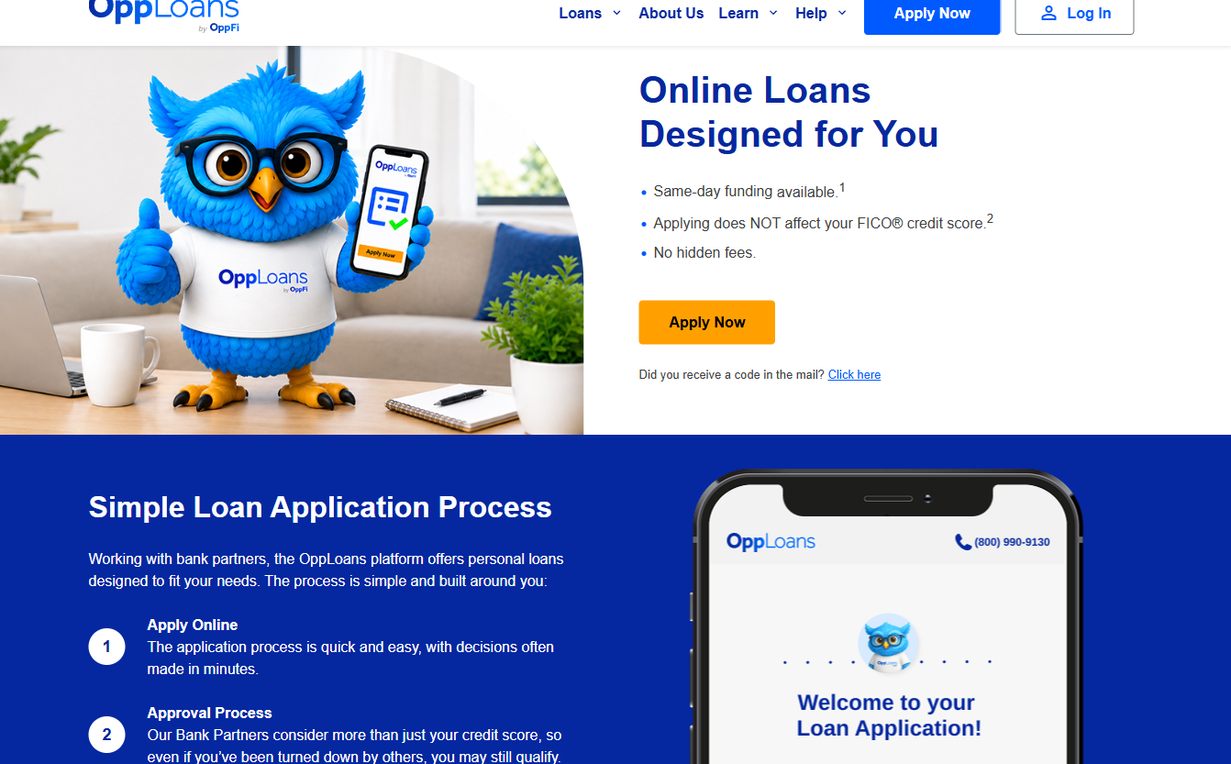
OppLoans – opploans.com

When an unexpected invoice arrives and your FICO score isn’t looking particularly bright, OppLoans can help. Their application is straightforward and looks at more than just a single credit number. By reviewing your employment stability and banking patterns, they act as a safety net for those struggling with low scores due to unemployment or medical expenses.

Speed is the name of the game here. If you find yourself in a jam—maybe your car’s transmission fails while cruising on the Kennedy Expressway—the prospect of receiving funds in your bank account the very same day can be a total lifesaver. It is a streamlined method to get capital without the mountain of paperwork usually demanded by big national banks.

Pros:

  • Checking rates won’t hurt your FICO score.
  • Possibility of getting funds the same day.
  • You won’t encounter any hidden fees.

Cons:

  • Might not work for those needing massive loans.

3. IllinoisLoansToday

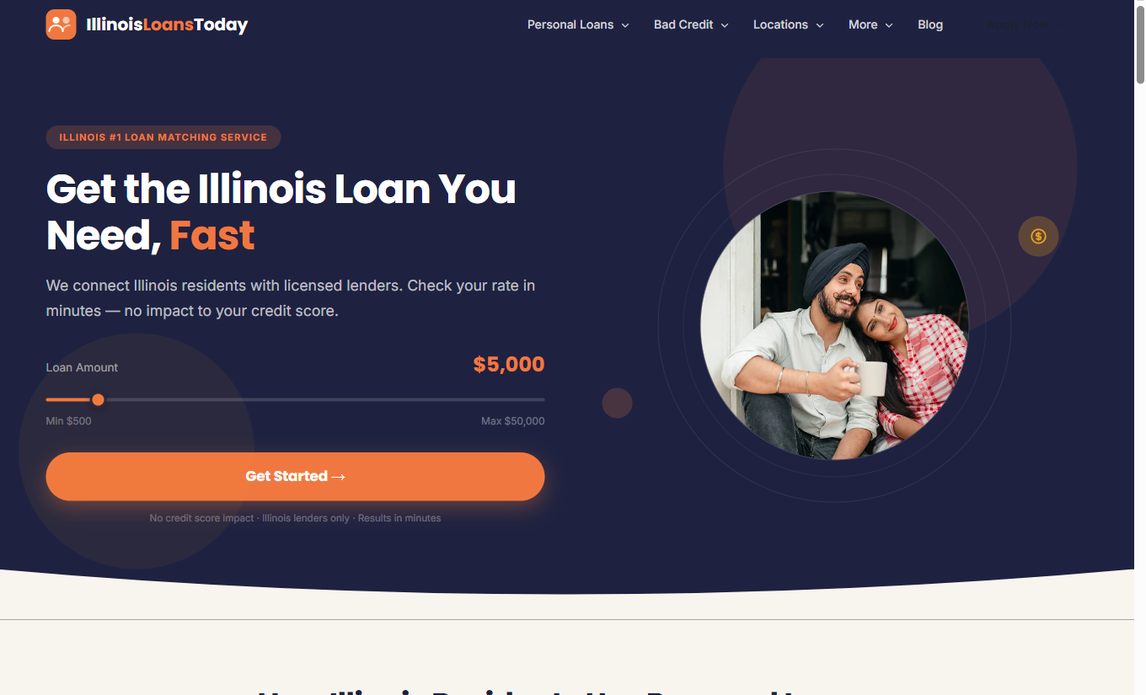
IllinoisLoansToday – illinoisloanstoday.com

Think of this service as a massive bridge connecting Illinois locals to a vast web of licensed lenders. Instead of being a lender itself, it acts as a matchmaking tool to find the perfect fit for your specific circumstances. It functions like a digital concierge, scanning through various lending requirements to find the easiest route for your personal profile. (illinoisloanstoday.com)

The variety available is quite striking, moving from a small $500 up to $50,000. Whether you are renovating a bungalow in Berwyn or paying off a sudden hospital bill, this platform seeks to pair you with a lender that meets those exact demands. Since they match you with existing providers, you can often secure much better rates than if you were to blindly approach one specific lender.

Pros:

  • Huge range of funding from $500 to $50,000.
  • Checking your rates won’t impact your credit score.
  • Designed specifically for the Illinois community.

Cons:

  • You are being connected to a third party, not a direct lender.

4. SAIL Loans

SAIL Loans – sailloans.com

SAIL Loans operates on a philosophy very much like GoCredit, prioritizing long-term financial health. Their installment loans are structured so that you can grow both your savings and your credit score at the same time. They understand that many people aren’t just missing cash; they are missing a structured system to build a financial cushion.

They won’t just hand you cash and disappear into the night. Instead, they offer support and financial literacy tools to help guide you along the way. This educational aspect is vital for anyone trying to take their first real steps toward stability. Once you grasp the “why” behind your loan, you will be much more prepared to manage your money later.

Pros:

  • Provides tools to improve financial literacy.
  • Focuses on simultaneous credit and savings growth.
  • Simple, three-step application process.

Cons:

  • The $4,000 cap may feel small for big projects.

5. SoFi

SoFi – sofi.com

SoFi is a heavy hitter offering a massive array of financial options. They are a true one-stop shop, providing everything from checking and high-yield savings to investing and mortgages. While other lenders on this list are specialists for specific problems, SoFi is a generalist meant to support an entire financial lifestyle.

This is the perfect choice for a borrower who wants to keep their whole financial life under one roof. If you have a steady paycheck and a strong credit history, and you want to move from “getting by” to “building wealth,” SoFi is a major player. They are particularly excellent at debt consolidation, helping you swap several high-interest credit card bills for one single loan.

Pros:

  • A full ecosystem of banking and investing.
  • Features high-yield savings and smart cards.
  • Access to many financial calculators and tools.

Cons:

  • Usually requires much better credit than specialized builders.

Choosing the Right Financing Path

Take a moment to pause and scrutinize the details before you ever click that application button. It is incredibly easy to get swept up in low monthly installments, but ignoring the cumulative interest is a recipe for disaster. Many borrowers find themselves staring at a mountain of debt because they prioritized immediate affordability over long-term stability.

A 36-month loan might look like a breeze on paper, yet high interest rates can effectively force you to pay back twice your original principal. You must grasp the nuances of your repayment timeline and the penalties for late payments. In a city like Chicago, where property taxes and winter heating bills can throw a wrench in your budget, financial flexibility is essential.

Don’t fall for those flashy advertisements promising “guaranteed approval” without laying out specific terms. Such vague marketing often masks predatory interest rates or sneaky administrative fees that bite you later. A reputable lender will lay all the cards on the table, providing a transparent breakdown of your total credit costs before any ink is dry.

Remember, constructing a solid credit score is more like a marathon than a sudden sprint. Utilizing services such as GoCredit or SAIL Loans can provide a helpful head start, but true progress requires iron-clad spending discipline. Think of credit as a double-edged sword: it can help you build a sturdy foundation or, if handled poorly, dig a hole you can’t escape.

Top-Rated Personal Loans in Illinois for Quick Cash in 2026

By Uncategorized
Personal loans in illinois

Top-Rated Personal Loans in Illinois for Quick Cash in 2026

Last updated: 2026-10-17

Navigating your finances in Illinois can often feel like steering through a Chicago whiteout with nothing but a dim headlight. You might know exactly where you want to go, but the path ahead is cluttered with unexpected bumps and poor visibility. Simply typing a query into a search engine isn’t enough to find a reliable lender.

Instead, you must take a hard, honest look at your immediate financial requirements. This state is a massive tapestry, stretching from the bustling metropolitan hubs of Cook County all the way to the quiet, sprawling agricultural stretches of the southern regions. Because of this diversity, your available financial products are not one-size-fits-all.

Your specific zip code and your current credit standing act as the compass for your options. What works for someone navigating the urban jungle of Chicago might not be the right fit for someone living in a rural township. Your physical location plays a massive role in determining which doors will actually open for you.

Whether you are tackling an urgent home repair in Springfield or attempting to break free from the crushing weight of expensive credit card interest, the lender you choose will dictate how bumpy your journey feels. This guide is designed to provide a sense of direction when the market becomes overwhelming. Selecting an unsuitable provider can bring your financial recovery to a grinding halt before it even begins.

Consider your financial needs like a toolbox. Using a sledgehammer to hang a picture frame is a recipe for disaster, just as a high-cost payday loan is often overkill for a small, manageable debt. Conversely, a traditional personal loan might lack the flexibility required if you are working specifically to mend a bruised credit history. You must ensure the instrument fits the task at hand.

  1. Tower Loan
  2. IllinoisLoansToday
  3. OppLoans
  4. SAIL Loans
  5. MaxCash

Comparing Local Lending Services

Our team curated this selection by observing how these financial institutions serve the residents of the Prairie State. While getting cash quickly is a major plus, speed is only one piece of the puzzle. The sweet spot is finding a provider that offers manageable loan limits and approachable terms for various credit backgrounds.

We carefully analyzed how each firm navigates the unique landscape of the Illinois economy. This involved digging into specific state-level mandates and the financial hurdles our neighbors face daily. A loan can be a total godsend during a sudden engine failure, but it can quickly turn into a millstone around your neck if the contract is confusing.

This breakdown highlights the genuine opportunities currently available to those living in Illinois. We scrutinized their credit check processes, the actual velocity of fund transfers, and whether their maximum borrowing limits serve practical needs. We essentially wanted to see how these digital applications perform when faced with real human situations.

Provider Borrowing Limits Eligibility Criteria Time to Funds
Tower Loan $2,500 – $20,000 see site see site
IllinoisLoansToday $500 – $50,000 No credit score impact to check Results in minutes
OppLoans $500 – $5,000 Considers more than just FICO Same-day funding available
SAIL Loans Up to $4,000 No, bad, or good credit Quick Approval
MaxCash $250 – $10,000+ Bad Credit Loans available Minutes

Crunching the Numbers: Deciphering APR and Interest Totals

Before signing on the dotted line, you must get a grip on the underlying arithmetic. It is incredibly easy to get blinded by a low monthly installment. A fifty-dollar bill each month might feel like a walk in the park, but if that cycle drags on for 36 months due to steep rates, you could end up paying back twice your original principal. That is exactly how people fall into the teeth of a debt trap.

When you weigh your options across different providers, focus your eyes on the Annual Percentage Rate (APR). This specific figure offers much more transparency than a basic interest rate. It bundles the interest charges along with any compulsory fees required to secure your funds. A company might tempt you with a bottom-tier rate, only to ambush you with a massive origination fee right at the start.

Imagine you are pulling a $2,000 loan to settle a sudden medical crisis. If there is a $200 fee tucked away in the fine print, your actual cost of capital shifts drastically. It spikes your real debt burden from day one. Always pose this question to yourself: “How much cash will have left my pocket by the time this debt is fully extinguished?” That specific number reveals the unfiltered reality.

Priming Your Loan Request for a Quick Decision

Think of your loan application like a chef preparing for a busy dinner rush; if the ingredients aren’t prepped, everything falls apart. Today’s lenders rely heavily on high-speed algorithms to vet your identity and salary. If your files look like a tangled mess of old receipts, you risk hitting a brick wall or facing annoying delays.

Getting your ducks in a row is essential. You want the machine to see a clear, professional profile rather than a puzzle with missing pieces. To keep the gears turning without a hitch, pay close attention to these specific requirements:

  • Validate Your Revenue Streams: Creditors are looking for a consistent heartbeat of income. You should have your most recent two to four pay slips sitting right at your fingertips. For those navigating the Illinois gig economy or running a solo business, ensure your 1099 forms or the past two years of tax filings are ready to go.
  • Prove You Live in the Prairie State: Because these specific providers concentrate on Illinois, your paperwork must reflect your local residency. Use utility invoices or monthly bank records to confirm your current street address. If the data on your form clashes with your official papers, automated systems will likely raise a red flag.
  • Double-Check Your Banking Info: Companies that specialize in rapid funding, such as MaxCash or OppLoans, utilize ACH transfers to move money. It is vital that your chosen account is active, contains enough capital to cover that initial installment, and bears a name that is an exact match to your application.
  • Evaluate Your Debt-to-Income (DTI) Balance: Even a lender like OppLoans needs to be certain you won’t sink under the weight of new payments. Figure out your total monthly obligations and weigh them against your gross earnings. The leaner that ratio looks, the more likely lenders are to give you the green light.

Leading Personal Loan Options Across Illinois

1. Tower Loan

Tower Loan – towerloan.com

Think of Tower Loan as a hybrid service that meets you exactly where you are. If you prefer the digital route, you can grab a mid-sized loan for something like a new washing machine or a set of tires via your smartphone. These online options generally provide between $2,500 and $6,000.

Sometimes, life’s financial puzzles are too messy for a computer to solve alone. If your situation is a bit tangled, you can walk into a physical branch to speak with a real person. This face-to-face interaction opens doors to much larger sums, allowing for borrowing limits as high as $20,000.

Whether you are looking to renovate your kitchen or consolidate a mountain of small, high-interest debts into one manageable payment, they have you covered. It is a versatile way to bridge the gap between lightning-fast internet applications and the comfort of traditional customer service.

Pros:

  • Branch visits unlock higher borrowing limits.
  • Choose between digital or in-person assistance.
  • Broad range of uses, from vacations to home projects.

Cons:

  • Digital loan caps are much smaller than branch offerings.

2. IllinoisLoansToday

IllinoisLoansToday – illinoisloanstoday.com

IllinoisLoansToday acts like a high-speed matchmaking service designed specifically for our state. Instead of you hunting down every lender, they connect Illinois residents with licensed professionals. It is a wonderful way to scout your options without the gut-punch of a credit score drop.

Because they use a “soft pull” method, checking your rates won’t hurt your credit standing at all. This makes it easy to shop around. From fixing a leaky roof to settling a sudden medical bill, their range is quite broad, spanning from $500 all the way up to $50,000.

The scale of their limits reflects the diverse needs of our local community. A resident in Peoria might only need a quick $1,200 for a sudden repair, while a neighbor in Naperville might seek $40,000 to consolidate significant debt.

Pros:

  • Checking rates won’t ding your credit score.
  • Impressive maximum limit of $50,000.
  • Exclusively serves the Illinois lending market.

Cons:

  • You are being referred to third-party lenders.

3. OppLoans

OppLoans – opploans.com

If the big banks have turned you away, OppLoans might be the lifeline you need. Their platform recognizes that real life is rarely perfect and credit histories are often messy. They look beyond just a FICO score, considering your employment stability and how you handle your existing bank accounts.

Speed is their specialty, which is vital when an unexpected car repair threatens your ability to get to work. You can often receive a decision in just a few minutes, and same-day funding is available for those in immediate need of cash.

This is especially helpful when a looming utility bill is threatening your household stability. They aim to help you keep moving forward, even when your credit isn’t exactly where you’d like it to be.

Pros:

  • Applying doesn’t impact your FICO score.
  • Fast funding may occur on the same day.
  • Flexible standards for those with imperfect credit.

Cons:

  • Maximum loan amounts are restricted to $5,000.

4. SAIL Loans

SAIL Loans – sailloans.com

SAIL Loans plays the long game by focusing on your future financial health. Their installment loans are built to help you cultivate savings while simultaneously boosting your credit profile. It is a clever, strategic move for anyone wanting to master their money over time.

You don’t need to be a computer whiz to get started, as the application involves only three simple steps. While the $4,000 cap might seem small compared to other lenders, the real value lies in credit building.

If you are planning to apply for a mortgage in a year or two, this is a smart way to strengthen your score now. It is about laying a solid foundation for your next big financial milestone.

Pros:

  • Assists with credit building and saving money.
  • The three-step application is incredibly simple.
  • Welcomes those with good, bad, or no credit.

Cons:

  • Maximum loan amounts are lower than most competitors.

5. MaxCash

MaxCash – maxcash.com

MaxCash functions as a versatile toolbox for quick liquidity. They don’t just stick to one thing; they offer everything from standard personal loans to cash advances and title loans. It is a powerhouse option if you need a very specific financial tool right away.

If you have equity in your vehicle and need money fast, a title loan might get you through the door quicker than a traditional bank loan. Their amounts are incredibly flexible, starting as low as $250 and climbing to over $10,000.

They strive to get you connected to your funds within minutes. This makes them a highly adaptable resource for plugging urgent holes in your monthly budget when you just need a quick fix.

Pros:

  • Extensive range of funding ($250 to $10,000+).
  • Rapid processing, often within minutes.
  • Includes diverse products like title loans.

Cons:

  • The variety of options might feel overwhelming.

Making the Right Choice for Your Debt

Selecting a financial partner is much like picking out a sturdy pair of hiking boots; your specific destination dictates the perfect fit. If your upcoming kitchen remodel demands a heavy-duty $15,000, you should look toward robust options such as the branch services offered by Tower Loan. Conversely, a quick fix for a dented fender might only necessitate the lightning-fast delivery of MaxCash.

It is vital not to dive headlong into a predatory interest rate simply to patch up a momentary crisis. You must scrutinize the complete price tag rather than focusing solely on what leaves your wallet each month. While a low monthly installment might seem tempting, stretching out the repayment timeline can significantly inflate the ultimate cost of your debt.

Consider a scenario where you borrow $1,000. If the terms span 24 months at a steep interest rate, that initial loan could balloon into a $1,500 total obligation by the time you finish. Always keep your eyes on the finish line to avoid being blindsided by long-term expenses.

Lastly, clearly define your objective before you click that “Apply Now” button. Are you aiming to repair your credit score via SAIL Loans, or do you need liquid cash by tomorrow using OppLoans? Perhaps you require a massive lump sum through IllinoisLoansToday or Tower Loan.

Walking into a lending scenario with a clear roadmap ensures that the funds you secure today won’t transform into a heavy anchor of anxiety tomorrow. Being prepared is your best defense against financial turbulence.

illinoisloanstoday.com

Find the Best Flooring Financing Deals for Your Home Remodel

By Uncategorized
Flooring financing

Find the Best Flooring Financing Deals for Your Home Remodel

Last updated: 2026-10-16

Tackling a home makeover is a heavy lift that frequently feels like you are taking on another mortgage. When your hardwood loses its luster or linoleum begins to curl at the edges, the impulse to overhaul the space is overwhelming. You might feel a sudden rush to fix the damage immediately.

Yet, looking at a steep bill for luxury laminate or tile can be a cold bucket of water for your bank account. The price of raw materials, ranging from elite porcelain tile to top-tier engineered hardwood, can skyrocket. You must also account for the hidden costs of underlayment, subfloor prep, and various transitions.

Securing the right payment method for these improvements is just as vital as picking out a specific hue. You might need a quick injection of cash for minor fixes or a multi-year strategy to overhaul your entire residence. In 2026, the landscape of lending offers a multitude of various routes.

The path you choose to take right now determines your future peace of mind. Will this renovation stay a beautiful vision, or will it turn into a bitter weight on your shoulders? Making a smart choice ensures your project doesn’t become a source of lasting financial resentment.

Leading Providers for Flooring Loans in 2026

Selecting a lender is a bit like picking the right foundation for your new floors. If you choose poorly, the whole structure of your budget might shift unexpectedly. You want a partner that offers clarity rather than confusing fine print.

Market experts have evaluated several providers to see who truly delivers on their promises. Some focus on lightning-fast approvals, while others provide more flexible repayment structures for those on a tighter budget. It is all about finding the perfect fit for your specific project scale.

The following list represents our curated selection of the most reliable financing avenues currently available. We have looked at how these companies stack up against one another in the current economic climate. Use this ranking to help navigate your upcoming home improvement journey.

  1. FastLendGo
  2. HFS Financial
  3. Acorn Finance
  4. Wisetack
  5. Affirm
  6. Floor Daddy

Comparing the Leading Financing Providers

Hunting for the right lender involves more than just glancing at the lowest interest rate displayed on a webpage. You have to consider how quickly cash reaches your pocket and whether the paperwork will turn into a massive headache. A low rate might look enticing on paper, but the total cost can skyrocket depending on the loan term.

Consider this scenario: taking out a $10,000 loan at 10% interest over 3 years will result in roughly $1,750 in interest payments. However, if you stretch that same $10,000 loan out to 7 years, the interest climbs to nearly $4,000. It is a delicate balancing act between immediate monthly affordability and the ultimate price of the debt.

Our review process prioritized speed, ease of use, and how much a lender impacts your credit profile. We looked for transparency, favoring companies that lay their cards on the table instead of hiding sneaky fees in the fine print. Every company was measured by its ability to help everyone, from those with perfect credit to those just trying to keep their heads above water.

Provider Funding Range Credit Profile Primary Benefit
FastLendGo $500 – $5,000+ Good to Bad Credit Rapid cash delivery
HFS Financial see site No equity required Fixed low rates
Acorn Finance see site Good and Bad Credit Zero fees for dealers
Wisetack see site Soft credit check Up to 24-month 0% APR
Affirm see site No credit check options Versatile payment schedules
Floor Daddy see site see site 48 Months 0% Financing

1. FastLendGo

FastLendGo – fastlendgo.com

When life throws a curveball, FastLendGo acts as a versatile financial bridge for various needs, including sudden home repairs. It is a lifesaver for those in a pinch who need to weigh different personal loan options without enduring an endless marathon of applications. This is the go-to choice for “emergency” situations.

Imagine you discover a sudden leak beneath your new flooring or a broken stair tread. In these moments, getting the funds quickly matters far more than chasing the absolute lowest interest rate on the market. fastlendgo.com serves as a fast-track solution for these urgent scenarios.

The platform is built to accommodate a massive range of financial backgrounds. Whether you are looking for a $500 quick fix or a $5,000 overhaul, the system is designed to pair high-income earners and those with less-than-perfect credit with suitable lenders. Their matching algorithm works hard to close the gap between your current credit score and what a lender requires.

Pros:

  • Offers loan amounts ranging from $500 to $5,000 and up.
  • Accepts a broad spectrum of credit scores, including fair or bad.
  • Provides an efficient way to compare personal loans online.

Cons:

  • Rates may not be the most competitive for individuals with excellent credit.

2. HFS Financial

HFS Financial – hfsfinancial.com

HFS Financial has carved out a niche for homeowners who want to skip the nightmare of traditional equity-based lending. They are a fantastic choice for those looking to upgrade their floors without putting their primary residence up as collateral. Traditional Home Equity Lines of Credit (HELOCs) often feel intimidating because your house is the security.

If you default on a HELOC, your home is effectively on the line. HFS Financial provides a refreshing alternative that keeps the loan completely separate from your property title. It is a way to borrow money for home improvements without the heavy weight of a mortgage-backed debt hanging over your head.

The biggest selling point here is how fast the approval process moves. They focus on quick decisions, helping you transition from the “dreaming” stage to the “installing” stage without waiting weeks for a bank to digest your paperwork. This is a godsend when a contractor is ready to work but you are waiting for your funds to clear.

Pros:

  • No requirement to use home equity for the loan.
  • Provides stable, low-fixed interest rates.
  • Rapid approval speeds help get projects moving.

Cons:

  • Fixed rates might lack the flexibility of variable options in certain economic climates.

3. Acorn Finance

Acorn Finance – acornfinance.com

Acorn Finance is a heavy hitter for customers looking to dodge the “hidden costs” that often pop up with contractor financing. They specialize in linking borrowers with various lenders to ensure that dealer fees don’t quietly swallow your renovation budget. Many contractors try to add a 10-20% “financing fee” to your bill if you use their preferred lender.

Acorn Finance works to stop that leak by connecting you directly to lenders. One of their most valuable features is the ability to view personalized rates using only a soft credit check. This is a massive relief for anyone terrified of seeing their credit score dip before they even know if the project is financially viable.

You can use their tools to establish a realistic “budget range” before you even pick up the phone to call a contractor. This approach puts you in a much stronger position during the negotiation phase of your project. It is about entering the room with knowledge rather than just a hopeful guess.

Pros:

  • Consumers are not burdened by dealer fees.
  • Soft credit checks allow for rate shopping without affecting your score.
  • Earning high marks for overall customer experience.

Cons:

  • Because they use many lenders, rates can vary wildly between different offers.

4. Wisetack

Wisetack – wisetack.com

Wisetack is a favorite among service pros because it weaves itself seamlessly into their existing payment systems. This isn’t a traditional bank-focused product; it is more about streamlining the transaction between a homeowner and a professional. For the client, this means much less paperwork and a much more direct experience.

You won’t have to go out on a hunt for a loan. Most likely, your contractor is already set up to offer Wisetack as a standard payment method. If you want to settle your flooring bill via a simple invoice link or a text message, this is the path of least resistance.

For medium-sized renovations, such as a master bathroom or a single large room, their 24-month 0% APR option is a real lifesaver. It allows you to spread out your payments and manage your cash flow without adding any interest to the total cost of the work.

Pros:

  • Approvals can happen incredibly fast, often in just 60 seconds.
  • Offers 0% APR options for terms reaching up to 24 months.
  • Consistently high ratings for customer satisfaction.

Cons:

  • Availability and specific terms depend on your contractor’s specific setup.

5. Affirm

Affirm – affirm.com

Affirm has become a massive name in the “Buy Now, Pay Later” world. It is an incredibly convenient tool for smaller projects or for buying raw materials from big-box home improvement retailers. If you are a DIY enthusiast who just needs $2,000 for luxury vinyl plank, Affirm is often the simplest route.

The flexibility they offer is truly in a league of its own. You can choose between short-term interest-free plans or longer-term monthly payments that are much easier on your wallet. It is a very honest way to shop because you see the exact total you will pay right at the start.

There are no “gotcha” moments or sudden interest rate spikes halfway through your payment schedule. Once the terms are set at the point of sale, they stay locked in. This transparency takes the guesswork out of your household budgeting.

Pros:

  • High transparency with no hidden fees or shifting interest.
  • Flexible plans, including interest-free options for specific items.
  • Very user-friendly through an app or via the web.

Cons:

  • Not every flooring professional is set up to accept Affirm.

6. Floor Daddy

Floor Daddy – floordaddy.com

Floor Daddy is a specialized local player that treats financing and installation as two sides of the same coin. This is the perfect setup for someone wanting a “one-stop shop” where your labor and your payment plan are inextricably linked. It removes the fear of paying for materials but running out of cash for the actual installer.

They provide a massive 48-month 0% financing option, which is a rare find in this industry. This allows families to spread the cost of a major renovation over four years without being eaten alive by interest. It makes large-scale home improvements much more attainable for the average family budget.

For a $10,000 renovation, paying $208 every month for four years is a much easier pill to swallow than a massive lump sum. It is a far more manageable way to handle a project than using a high-interest credit card or draining your entire savings account at once.

Pros:

  • Long-term 0% financing available for up to 48 months.
  • Covers everything from professional floor prep to dustless removal.
  • Maintains an impressive 5.0 star reputation.

Cons:

  • The financing is generally tied to using their specific installation services.

Evaluating Your Borrowing Options

Before you sign any paperwork, you must grasp the fundamental mechanics of the credit options available to you. Picking an unsuitable lending model can lead to a mountain of debt or even messy tax headaches down the road. Think of it as picking the right tool for a renovation; the wrong one might damage the very house you are trying to beautify.

Each financial path offers a different way to handle your renovation budget. Some move fast like a lightning strike, while others take a slow, methodical approach. It is vital to weigh the pros and cons carefully before you dive into the deep end. Use the breakdown provided below to see which avenue aligns with the scope of your upcoming flooring installation.

Method of Funding Ideal Use Case Primary Danger Access to Cash
Personal Loan Managing funds yourself for DIY tasks or various subcontractors Elevated interest costs for those with lower credit scores 1–3 Business Days
0% APR Financing Mid-sized projects utilizing premium, high-end materials Requires full repayment before the promotional window expires Instant (at checkout)
Home Equity Loan Extensive, whole-home renovation endeavors Your physical property serves as collateral for the debt Weeks to Months
Buy Now, Pay Later Small repairs and individual material purchases It is quite easy to overspend on minor items Immediate

As you weigh these choices, always keep your “exit strategy” in the back of your mind. If you are planning to move out of your house in two years, avoiding a long-term home equity loan is a wise move. These loans attach a lien to your property title, creating a hurdle that must be cleared during the closing process.

On the flip side, if you intend to live in your residence for the next decade, a fixed-rate personal loan might be your best friend. Such a loan offers a predictable, stable method to boost your home’s market value. You won’t have to worry about the stomach-churning volatility often associated with variable interest rates.

Decoding Your Payment Options

Don’t let a tiny monthly bill fool you into a bad deal. You might think a five-year plan looks easy on the wallet, but those extended terms can actually inflate the final price tag. It is easy to get lost in the weeds of small installments while ignoring the bigger picture.

Before you put pen to paper, demand to see the “Total Cost of Borrowing.” This specific figure reveals the true weight of your debt. When you are standing between two different banks, this is the only metric that actually matters for your bank account.

Think of it like buying a car; a low monthly rate might just mean you are paying for the metal for a much longer time. Always prioritize the total sum over the immediate ease of a small payment. It is the difference between a smart investment and a lifelong debt trap.

Many homeowners fall into the trap of believing “no credit check” means zero impact on their rating. While it is true that looking at your rates might not hurt, the actual application usually triggers a formal check. You have to dance with the credit bureaus eventually.

I always tell my clients to hunt for soft-pull options first. This allows you to shop around like a savvy consumer without risking your reputation. If you go too heavy on hard inquiries in a single month, banks might think you are desperate for cash.

That “credit hunger” can cause your interest rates to skyrocket instantly. A single inquiry might only nudge your score down by 5 points, but a flurry of them looks suspicious to lenders. Protect your score by being methodical rather than impulsive during your search.

Once you start ripping up old carpet, the ghosts in your subfloor might appear. Contractors often find rot or crooked joists hidden beneath the surface. If your budget is razor-thin, these little surprises will turn into massive financial headaches very quickly.

It is much simpler to secure a larger sum upfront than to ask for more mid-project. Trying to expand a loan while the tile is being laid is a recipe for stress. You want to have your budget locked in before the first hammer swings.

I recommend adding a 15-20% “contingency buffer” to your initial request. This extra cushion acts as a safety net for those inevitable construction hiccups. Planning for the worst-case scenario ensures your home renovation stays on track and within your means.

Best Rates for a 12 year personal loan: Compare Top Lenders Today

By Uncategorized
12 year personal loan

Best Rates for a 12 year personal loan: Compare Top Lenders Today

Last updated: 2026-10-17

Searching for a bank that permits a 12-year repayment timeline feels like trying to find a unicorn in a crowded city. Most mainstream lenders cap their terms at seven years. This leaves those craving extended flexibility in a real bind. To keep your monthly outlays low, you’ll need to look past standard “quick cash” outfits.

You’ll probably require a firm comfortable with large-scale asset financing or complex debt restructuring. Finding the perfect match isn’t just about spotting a low APR. You must balance the speed of funding against the cumulative interest accrued over twelve years.

A 144-month plan might seem like a dream due to the small monthly chunks. But, do the math carefully. You might discover that your interest costs nearly double what you originally borrowed. This selection highlights the best options to navigate long-term borrowing without drowning in debt.

  1. U.S. Bank
  2. Wells Fargo
  3. JetzLoan
  4. Citi
  5. OneMain Financial
  6. Alliant Credit Union

Our Selection Criteria for Borrowing Options

Our team went on a hunt to find lenders that actually offer flexibility and long-term options. Since many old-school banks pull the plug at 84 months, we steered clear of those rigid limitations. Instead, we prioritized companies that can handle longer timelines without breaking a sweat.

We dissected every step of the application journey to see how fast the money actually hits your bank account. It is not just about the speed of cash delivery, though. We also scrutinized whether these lenders play fair or hide sneaky costs in the fine print.

We dug deep into how these firms communicate their fee structures to the public. Transparency is the name of the game when you are looking at a massive financial commitment. If a company makes the math feel like a riddle, they didn’t make our final cut.

One non-negotiable for us was the ability to pay off your debt early without getting slapped with penalties. Making extra payments is a lifesaver for slashing the interest you pay over many years. If a lender punishes your proactive behavior, they simply aren’t the right fit.

Reliability is the backbone of any good financial partner. A rock-solid interest rate doesn’t mean much if the process feels like a marathon of paperwork. We wanted to ensure that our list included lenders who respect your time as much as your wallet.

Finding that sweet spot between established institutions and slick, digital-native apps was essential. We wanted to provide a toolkit for every type of borrower out there. Whether you want a big name or a fast app, we had you covered.

Finally, we looked past the surface-level interest rates to find the true cost of borrowing. We weighed the APR against the base rate to ensure our readers aren’t caught off guard. We wanted the real story, not just the marketing pitch.

Lender Name Maximum Borrowing Length of Term Time to Fund Credit Check Method
U.S. Bank see site see site see site see site
Wells Fargo $100,000 12-84 months see site see site
JetzLoan $50,000 see site 24 hours No hard pull
Citi $30,000 12-60 months see site see site
OneMain Financial $30,000 24-60 months 1 hour see site
Alliant Credit Union see site see site see site see site

Leading Providers for Extended-Term Financing

1. U.S. Bank

U.S. Bank – usbank.com

Think of this institution as a cornerstone of the American financial landscape. They offer a vast array of tools that make life much easier for the organized borrower. Instead of jumping between apps, you can keep your savings, checking, and personal loans all tucked away in one tidy, centralized home.

For the seasoned planner who prefers a traditional approach, their setup is a dream. They prioritize stability, which is a lifesaver when you are committing to a long-term debt cycle. Having your entire financial life under one roof makes monthly budgeting feel like a walk in the park rather than a mountain to climb.

Imagine the relief of setting up an automatic transfer to cover your monthly installment. It’s a simple trick that guards you against those pesky late fees that can snowball over a decade. If you desire a one-stop shop for all your fiscal needs, you’ll feel right at home here.

Pros:

  • A seamless banking environment for effortless management.
  • A diverse selection of services, including investment options.
  • A storied and reliable institutional background.

Cons:

  • Application processes might demand more paperwork than online-only startups.

2. Wells Fargo

Wells Fargo – wellsfargo.com

When the stakes are high, Wells Fargo steps up to the plate. If you are eyeing a massive project like a kitchen remodel or need to consolidate a mountain of debt, their ability to hand out up to $100,000 is a major selling point. They entice serious players with very competitive introductory rates, especially for those with a solid credit history.

This makes them a heavy hitter for anyone needing a large injection of capital right away. Their fixed interest rates provide a steady hand in an unpredictable economy. You won’t have to lose sleep worrying about your monthly payment suddenly ballooning because of market shifts.

That predictability is worth its weight in gold. While a variable-rate lender might offer a slightly lower starting rate, the peace of mind provided by a fixed payment often wins the day. It’s about knowing exactly where your money is going every single month without any surprises.

Pros:

  • Massive borrowing ceilings reaching $100,000.
  • Fixed rates that ensure your budget stays predictable.
  • A vast network of physical branches for face-to-face help.

Cons:

  • Securing the highest amounts usually requires top-tier credit.

3. JetzLoan

JetzLoan – jetzloan.com

In the world of JetzLoan, time is the most precious commodity. If you find yourself in a financial pinch and need cash yesterday, JetzLoan is your fastest route to relief. They are built for speed, often getting funds into your pocket in as little as 24 hours.

This is the perfect solution for those sudden, “oh no” moments—like an emergency car repair or an unexpected medical bill. Sometimes, paying a slightly higher interest rate is a small price to pay for the speed you receive. Best of all, you can scout your rates through a soft credit pull, which keeps your score perfectly safe.

This “soft pull” approach is a breath of fresh air for anyone tired of playing the guessing game. It lets you weigh your options and compare different lenders without any risk to your credit profile. You get the raw facts without any lasting damage to your standing.

Pros:

  • Lightning-fast funding, sometimes within a single day.
  • No impact on your credit score when checking rates.
  • Highly rated customers love the streamlined digital process.

Cons:

  • Loan amounts are capped at a maximum of $50,000.

4. Citi

Citi – citi.com

Citi has mastered the art of the digital-first experience, catering perfectly to the tech-savvy borrower. Their personal loans are a smooth ride, making the application process feel almost effortless. With terms stretching up to 60 months, they provide a perfect middle ground for various mid-range financial goals.

Their mobile app is often the gold standard for usability. It makes tracking how much principal you’ve knocked off or how much interest you’ve paid a total breeze. This is a premier choice for those who want to run their finances through a sleek, modern interface rather than wading through paperwork.

If your goal is to sweep up high-interest credit card debt and roll it into a neat 5-year plan, Citi is a top contender. It is an ideal fit for someone wanting a streamlined digital life without needing a decade-long commitment. The numbers on their interface are incredibly easy to read.

Pros:

  • A world-class digital banking and user experience.
  • Repayment windows structured up to 60 months.
  • A strong reputation for handling significant credit limits.

Cons:

  • Term limits cap out at 60 months, not 12 years.

5. OneMain Financial

OneMain Financial – onemainfinancial.com

If the big-box banks have left you out in the cold, OneMain Financial might be your way back in. They specialize in helping folks who might not have a spotless credit history. Their ability to deliver funds sometimes just one hour after the paperwork is signed is nothing short of legendary.

Rather than just staring at a frozen credit score, they look at your actual ability to pay the money back. This makes them a lifesaver for people navigating life’s transitions. They also keep a heavy human touch, boasting a massive footprint of over 1,300 physical branches across the country.

It’s a lot better than arguing with an unhelpful chatbot when things get messy. Having a real person to look you in the eye provides a level of accountability that pure fintech companies just can’t match. It offers a sense of stability when you feel like you’re on shaky ground.

Pros:

  • Rapid funding that can happen in as little as an hour.
  • Massive physical presence with over 1,300 locations.
  • Accessible for borrowers with non-traditional credit profiles.

Cons:

  • Interest rates might climb higher for certain borrowers.

6. Alliant Credit Union

Alliant Credit Union – alliantcreditunion.org

Credit unions bring a unique flavor to the table, and Alliant is a standout in the crowd. Because they belong to their members, their mission often centers on providing better perks and better rates. Their high-yield accounts are an excellent place to let your savings grow.

This member-focused philosophy often leads to much lower fees than the massive national banks. While they are titans in the savings and certificate sectors, their loans are part of a much larger, integrated system. They are perfect for those wanting their money to work a little harder for them.

For the borrower aiming to build wealth while tackling existing debt, Alliant offers a holistic financial path. It is a savvy move for those who want to stay within a community-focused environment. You get top-notch credit tools alongside some of the best savings options available.

Pros:

  • A member-owned model that often yields better rates.
  • Attractive high-yield checking and savings accounts.
  • Top-tier improvements to their digital banking tools.

Cons:

  • You may need to meet specific membership requirements.

The Price of Extending Your Repayment Period

Choosing to stretch your debt over a decade or more is like trading your future wealth for immediate breathing room. While your monthly budget might feel lighter, the long-term mathematical toll is significant. You aren’t just paying back what you borrowed; you are essentially buying time with very expensive currency.

Let’s look at a practical scenario involving a $20,000 loan. If you opt for a 5-year timeline at a 10% interest rate, the total interest cost settles at around $5,500. It is a straightforward transaction where the cost of the money is clearly defined and manageable.

However, if you decide to push that same $20,000 debt out to a 10-year horizon at that same 10% rate, the math changes drastically. You end up shelling out roughly $11,700 in interest. You have doubled your monthly liquidity, yet the total expense has more than doubled as well.

It is crucial to grasp the “Effective Cost of Borrowing” before signing the dotted line. Without this perspective, you might find yourself blindsided by the sheer scale of what you owe. Many borrowers realize too late that their “affordable” loan is actually an expensive trap.

Keep a sharp eye on these specific financial pitfalls:

  • Setup Charges: Many institutions deduct a percentage—usually between 1% and 8%—directly from your loan disbursement to cover administrative costs. This means if you borrow $10,000, you might only see $9,500 in your bank account, despite owing the full amount.
  • Early Settlement Fees: Some contracts contain sneaky clauses that penalize you for being responsible. If you try to pay the debt off ahead of schedule, lenders may charge a fee to recoup the interest they expected to earn from you. Seek out “penalty-free” options instead.
  • Delayed Payments and Interest Cycles: Over a long 12-year window, life happens. If you miss a payment, you might trigger compounding interest, where you are effectively paying interest on top of interest. This can cause your principal balance to stagnate or even climb higher.

How to Navigate Long-Term Borrowing

Before you sign on the dotted line, you must realize that a twelve-year loan is a massive commitment. While the monthly payments might look tiny, the total interest you pay over a decade can be staggering. It is like a marathon; you need to ensure you have the stamina to keep running for the full duration.

Your income, career stability, and cost of living will all change over twelve years, and you must plan for that volatility. Avoid the temptation to take the longest term just because you can. A longer term reduces your immediate monthly burden, but it increases the total cost of the loan significantly. If you can afford to pay more each month, you will save thousands of dollars in the long run.

A common strategy is to take the long term to ensure you can always meet the minimum payment, but to aggressively pay extra whenever you receive a bonus, tax refund, or raise. This gives you the “safety net” of a low monthly requirement with the “wealth-building” benefit of a short-term loan. It is about having flexibility when things are tight and speed when you have extra cash.

Watch out for hidden fees that can sneak into the contract. Always ask about prepayment penalties. If you come into some extra cash and want to pay off the loan early, you don’t want the bank to punish you for being responsible. Always read the fine print before you let anyone access your bank account.

Specifically, look for the phrase “all payments are applied first to interest and then to principal”—this is standard, but you want to ensure you can make extra payments that go directly toward the principal balance. This is the fastest way to accelerate your path to debt freedom and stop the interest from eating your income.

Top-Rated Vacation Loans for Bad Credit to Fund Your Dream Getaway

By Uncategorized
Vacation loans for bad credit

Top-Rated Vacation Loans for Bad Credit to Fund Your Dream Getaway

Last updated: 2026-10-16

Picturing yourself lounging on a sun-drenched beach or hiking through misty mountain trails can feel like a pipe dream if your funds are running low. Life has a way of throwing curveballs when you least expect them. Perhaps a sudden medical bill or a stint without a paycheck has bruised your credit score, making standard bank loans seem impossible.

Financial hiccups are as common as rain in April, but they shouldn’t act as a permanent barrier to your wanderlust. Many people struggle to bridge the gap between their savings and their travel dreams. However, a low credit score doesn’t have to be the final nail in the coffin for your holiday plans.

Specialized lenders often peer past that solitary numerical rating to assess your actual reliability as a borrower. When you are hunting for travel funding, you are essentially walking a tightrope between ease of access and the total cost of borrowing. You need a partner that recognizes your struggles without shackling you to crushing interest rates.

It is a tricky balancing act between satisfying your current craving for adventure and maintaining your future financial health. For instance, chasing a quick payday loan just to snag a flight deal might seem like a shortcut. In reality, those predatory rates can create a debt trap that keeps you grounded for many years to come.

The smarter route involves seeking organized, steady financing that aligns with your wallet once you return home. You want a plan that works with your post-trip budget rather than against it. Our current evaluation highlights the premier options for travelers seeking a lift to reach their next paradise.

  1. FastLendGo
  2. Discover
  3. 60MonthLoans
  4. LightStream
  5. LoanStart

Our Selection Criteria

Our team set out to find lenders who don’t turn their noses up at travelers with bruised credit scores. We focused heavily on how approachable these companies are for people navigating a tough financial patch. It isn’t just about getting a “yes”; it is about finding a lifeline that actually works when you need it.

We took a hard look at the total sum of money offered and the velocity of the payout. After all, catching a lightning-fast deal on a flight requires swift action. If you are caught in a bureaucratic loop for weeks, that cheap seaside resort might be gone before your bank balance reflects any new cash.

Finding the right lender is a bit like hunting for a needle in a haystack. You want to avoid any pitfalls that might make your financial situation even shakier. We made sure the companies we highlighted wouldn’t leave you out in the cold when it comes to transparency or speed.

We specifically hunted for providers that allow soft credit checks during the initial quote phase. This is a game-changer for your peace of mind. It means you can window-shop for the best rates without fear of your score taking a nosedive from repeated hard inquiries.

Testing these options allows you to scout your horizon without any hidden damage to your profile. You should feel empowered to hunt for the best terms. Exploring your choices shouldn’t feel like a high-stakes gamble that leaves your credit history in tatters.

Our investigation centered on several vital indicators for every company:

  • Approval Odds: How much grace do they extend to borrowers with scores between 580 and 640?
  • Payout Velocity: Is the money ready for a sudden booking, or does manual paperwork slow things down?
  • Clarity of Terms: Are interest percentages and extra costs laid bare from the very start?
  • Usage Flexibility: Can you spend it on a cruise deposit or perhaps a train pass through Europe?
We aimed to pinpoint services that offer real freedom for vacationers who need to move quickly to lock in their dream trips.

Company Available Funding Credit Standards Time to Payout
FastLendGo $500 – $5,000 Bad/Fair Credit See site
Discover Up to $40,000 See site
60MonthLoans $2,600 – $10,000 See site
LightStream See site Excellent Credit
LoanStart Up to $40,000 See site

Top-Tier Financing Sources for Your Upcoming Trip

1. FastLendGo

FastLendGo – fastlendgo.com

When traditional banks slam the door on your loan application, FastLendGo often steps in to pick up the pieces. They focus on delivering diverse personal finance tools, specifically tailoring products for individuals navigating fair or poor credit scores. It is a versatile safety net for anyone needing a quick cash boost to cover unexpected emergencies or small getaway expenses.

Imagine stumbling upon a sudden, dirt-cheap deal for a boutique Mexican resort. If you only need $800 to grab that price, FastLendGo is built to handle those rapid, smaller transactions with ease. They act as a bridge for travelers who cannot afford to wait for lengthy approval processes.

This provider excels at meeting immediate, smaller-scale needs. Whether your weekend escape requires a few hundred dollars or a domestic road trip demands a few thousand, their framework handles various spending levels. They offer a practical route for those wanting to avoid the heavy scrutiny typically required by major institutions. Unlike big banks that demand mountains of paperwork for a mere $500 loan, these lenders prioritize speed and easy access.

Pros:

  • Focuses on borrowers with fair or bad credit.
  • Provides small personal loans starting from $500.
  • Operates across a wide range of states.

Cons:

  • The total amount borrowed is relatively small compared to other providers.

2. Discover

Discover – discover.com

Discover is a massive titan in the financial industry, bringing a level of institutional stability that smaller, niche lenders often lack. They provide personal loans suitable for covering major travel costs, such as international flights or luxury cruises. It is an excellent choice for travelers who prefer to manage their vacation funding through a household name.

Because they are a primary financial institution, their digital tools are incredibly intuitive. You can easily track and manage your repayment schedule through their dedicated mobile app. It makes the administrative side of debt feel much less overwhelming when you are trying to relax.

With borrowing limits reaching up to $40,000, this is a heavy hitter for significant milestones, like a honeymoon in the Maldives or a sweeping tour across Europe. Their streamlined application allows you to check for a pre-approval without hurting your credit score. This is a huge win for anyone carefully weighing their options without risking their ability to get a mortgage or car loan later.

Pros:

  • Large loan capacities reaching $40,000.
  • Checking pre-approval won’t damage your credit score.
  • Highly reputable and widely accepted brand.

Cons:

  • Meeting the requirements for the largest loan amounts might be tougher.

3. 60MonthLoans

60MonthLoans – 60monthloans.com

If you prefer a more orderly way to pay back what you borrowed, 60MonthLoans provides a very straightforward path. They offer personal loans between $2,600 and $10,000, with repayment terms that can extend for up to five years. This structure can make your monthly outlays much more comfortable for a tight budget.

Take a $5,000 trip as an example. By spreading that debt over 36 to 60 months, you avoid that dreaded “post-vacation hangover” where you feel financially drained for months after landing. It turns a massive one-time cost into a predictable, manageable monthly expense.

Their application is built for the modern era, taking only about ten minutes to finish on your phone. Once you get the green light, funds can arrive in your account as fast as one business day. This rapid turnaround is vital for travelers needing to lock in a reservation before prices skyrocket. It is a perfect middle ground for those seeking speed paired with long-term stability.

Pros:

  • Offers flexible terms lasting up to 5 years.
  • Quickly processes decisions.
  • Does not require collateral from applicants.

Cons:

  • The maximum loan limit is lower than what major banks offer.

4. LightStream

LightStream – lightstream.com

LightStream acts as the premium choice on this list, specifically designed for those with a very healthy financial profile. They offer low fixed interest rates, particularly if you choose the AutoPay option, which can save you a significant amount of money over the life of the loan. It is a sophisticated tool for high earners.

For a professional planning a luxury safari, LightStream offers the most economical way to borrow capital. You can avoid the sky-high interest rates usually tied to credit cards. It is a smart way to fund high-end experiences without unnecessary financial bleeding.

The service is famous for being incredibly smooth and swift, with some customers seeing funds as early as the next day. If you have been diligent about your credit, this lender offers some of the most competitive rates on the market. It is the ideal choice for those who want to fund major life events with minimal interest burdens.

Pros:

  • Extremely competitive low fixed rates.
  • Very rapid funding turnaround.
  • Digital application that is easy to use.

Cons:

  • Accessing the best rates requires excellent credit.
  • Interest rates are higher if you bypass AutoPay.

5. LoanStart

LoanStart – loanstart.com

LoanStart operates more like a gateway to a vast network of trusted affiliate lenders. Rather than adhering to just one set of rigid rules, they aim to match you with a partner that fits your specific financial DNA. This can be a true lifesaver if traditional banks have turned you away.

For instance, if your income fluctuates because of freelance work or seasonal jobs, the LoanStart network might include a lender who is much more comfortable with non-standard income. They don’t just look at you through a single lens; they look for the right fit for your unique situation.

You have the potential to borrow as much as $40,000, making this a high-capacity option for grand adventures. Since their service is free and won’t impact your credit score during the initial search, it is a zero-risk way to see what you qualify for. Think of them as a specialized financial matchmaker for your travel dreams.

Pros:

  • Provides access to a massive network of partners.
  • High borrowing potential up to $40,000.
  • Cost-free service with no initial credit score impact.

Cons:

  • You are being matched with an affiliate rather than borrowing from them directly.

The True Price of Financing Your Getaway

The thrill of booking a flight can sometimes cloud your judgment regarding the actual cost of borrowing. Think of interest as a small toll you pay for the luxury of exploring a new city right now instead of waiting until your savings catch up. You are essentially trading future income for immediate memories.

This financial tradeoff is often referred to as a convenience fee. It represents the cumulative weight of interest charges applied throughout your repayment journey. Understanding this dynamic is crucial before signing any paperwork for a vacation fund.

Let’s look at how different financial paths can impact your wallet in the long run. Consider these two distinct trajectories:

  • Scenario A: The Credit Card Route: Imagine you put a $3,000 holiday on a standard credit card. If you fall into the trap of only making minimum monthly payments while facing a 22% APR, the mountain of debt grows quickly. You might eventually pay back almost twice the original price of your trip over the course of many years.
  • Scenario B: The Structured Personal Loan: Now, suppose you opt for a set plan through 60MonthLoans for that same $3,000 journey. With a 12% APR spread over a 3-year term, your monthly obligations remain steady. This predictability ensures you aren’t hemorrhaging cash to interest, keeping your total expenditure much lower.

Opting for a fixed-term loan rather than the revolving trap of credit cards provides a clear roadmap for your finances. It allows you to master your repayment schedule and keep a tight grip on the final tally. Ultimately, this foresight makes your wanderlust far more sustainable for your future self.

Boosting Your Odds of Getting Loaned the Cash

A low credit score shouldn’t feel like a brick wall standing between you and a tropical getaway. You can still navigate the approval process successfully if you approach it with a meticulous mindset. It is all about proving you are a safe bet through consistent financial behavior.

Think of it like a first date; you want to show off your best, most reliable self. Lenders aren’t just staring at your numbers; they are looking for signs of stability. If you can demonstrate a regular paycheck and a realistic roadmap for paying them back, you might just surprise them.

Preparation is the secret sauce that separates a rejected application from a signed contract. Don’t just wing it and hope for the best. Taking these proactive steps will help you stand on much firmer ground during the underwriting process.

Try following these strategic moves to help your application shine:

  1. Confirm Your Earnings: Gather your most recent three months of tax filings or pay slips. It is vital to prove to the bank that your take-home pay can easily absorb the new monthly installments without breaking the bank.
  2. Audit Your Debt-to-Income (DTI) Ratio: Do some quick math before you hit that submit button. Divide your total monthly debt obligations by your gross monthly earnings. If the resulting percentage looks a bit steep, it might be wise to clear out a small credit card balance first.
  3. Scrutinize Your Credit Report: An old, inaccurate late payment can act like an anchor, dragging your score down to the bottom of the ocean. Use a complimentary service to hunt down errors and fix them so your report is pristine before any lender eyes it.
  4. Be Straightforward About Your Funding Needs: Avoid the temptation to grab more cash than you actually require. If your flights and lodging only cost $2,500, do not go asking for $5,000. Smaller requests are much easier for lenders to swallow and will save you a fortune in interest.

Steering Clear of Financial Traps

Before putting pen to paper, keep in mind that every borrowed dollar is a serious obligation. You might be daydreaming about Balinese sands, but a loan with predatory interest rates can turn those tropical visions into a fiscal nightmare overnight. It is crucial to scrutinize the small print, particularly the penalty fees for late payments and the specific mechanics of interest accrual.

Not all loans are created equal when it comes to how you repay them. While some utilize simple interest, other lenders employ more convoluted systems that might actually increase your overall debt if you decide to settle the balance ahead of schedule. Always look closely at these details to ensure you aren’t paying a premium for the privilege of being debt-free.

Don’t let the allure of an immediate getaway trick you into borrowing more than your monthly budget can actually handle. It often makes more sense to delay your departure by a few months to build up a substantial down payment. This approach is much safer than drowning in high-interest debt just to catch a flight today.

Ultimately, your getaway should serve as a sanctuary from stress, not a fresh source of monetary heartache. If the weight of these payments begins to feel overwhelming, reach out to your creditor without delay. Many financial institutions offer specific hardship protocols designed to restructure your debt, helping you avoid further damage to your credit rating before things spiral out of control.