
Apply for Fast Bad Credit Loans Arizona Today
Last updated: 2026-10-17
Weathering the blistering Arizona sun is a feat in itself, but a sudden financial blow can feel like a sudden sandstorm hitting you off guard. Sometimes, a sudden hospital bill or a mechanical failure in your vehicle arrives right when your credit score is at its absolute lowest.
You deserve a financial partner that prioritizes your personal circumstances over a mere numerical rating. When a Phoenix July brings a broken air conditioner or a Tucson legal emergency strikes, liquidity becomes a matter of survival rather than a luxury.
Navigating these crises requires a roadmap that avoids the pitfalls of predatory lending practices. It is incredibly important to weigh your various alternatives before the ticking clock of a looming deadline pushes you toward a questionable agreement.
Our curated selection features lenders who truly grasp the lifestyle and struggles of Valley of the Sun residents. We prioritized lightning-fast processing times and transparent contract language above everything else during our research process.
Securing a quick $500 for an auto repair might appear trivial, yet poor calculations can easily escalate that into a $1,500 nightmare. We judged these companies by their operational speed and their transparency regarding the final price tag.
You should never be left in the dark about what a loan actually costs you in the long run. It is about getting the funds you need today without being tethered to debt for the next ten years.
- NBA Arizona
- Arizona Zip Loan
- Sun West
- Arizona Financial
- Cash Time
Our Review Process for Desert State Lenders
Our team scoured the landscape from Phoenix to Sedona to see how accessible financial aid truly is. We specifically focused on the speed of fund distribution and the variety of options tailored for those with bruised credit scores. You shouldn’t need a mountain of gold to secure a fair deal when life hits a rough patch.
It is vital to distinguish between a massive banking institution and a niche lending specialist. While traditional banks typically demand stellar FICO scores and a long history of steady employment, they can be quite stubborn. On the other hand, specialized lenders often weigh collateral or alternative repayment proof, which can open doors much quicker.
We took a deep dive into the current inventory offered by these firms. This investigation included reviewing maximum loan amounts, specific product categories—such as personal or title loans—and the overall user experience during the signup process. We searched for those annoying “friction points” that trip people up, such as endless piles of paperwork or being left on hold for days.
Our ultimate aim is to provide a reliable compass so you don’t lose your way when cash is tight. We want to save you from the migraine of convoluted documentation and the agony of waiting forever for a response.
| Company | Borrowing Limits | Time to Funds | Eligibility Criteria |
|---|---|---|---|
| NBA Arizona | See site | See site | See site |
| Arizona Zip Loan | Up to $25,000 | 24hrs Average | See site |
| Sun West | See site | See site | See site |
| Arizona Financial | See site | See site | See site |
| Cash Time | $100 – $100,000 | As fast as 15 Minutes | No Problem |
Premier Arizona Lending Institutions for Credit Struggles
1. NBA Arizona
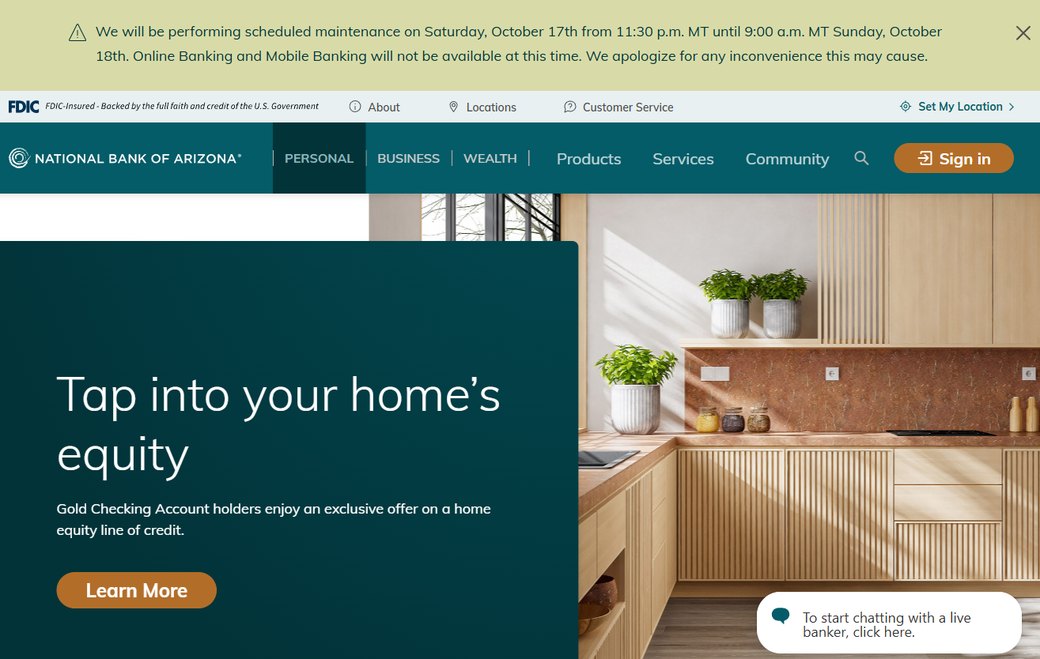
If you want a financial foundation rather than a temporary band-aid, NBA Arizona is a powerhouse. This FDIC-insured entity provides much more than just quick cash. They offer a vast spectrum of banking services designed for long-term stability and growth.
From basic everyday checking accounts to sophisticated retirement strategies and wealth management, they have it all. Because they are backed by the U.S. Government, your deposits remain safe up to the maximum legal limit. It is peace of mind you won’t find at a fly-by-night lender.
For those sitting on home equity in Mesa or Scottsdale, this institution is a goldmine. Gold Checking Account members can tap into special HELOC opportunities. Turning your living space into a financial asset can help you renovate or wipe out old debts through lower interest rates.
Pros:
- Protected by FDIC insurance and federal backing.
- Exclusive benefits for Gold Account holders.
- Extensive services for retirement and wealth building.
Cons:
- Premium products often demand superior credit scores.
- Not the ideal choice for immediate, small-dollar emergency cash.
2. Arizona Zip Loan
Life in the Grand Canyon State moves fast, and Arizona Zip Loan keeps pace. Whether you are navigating the bustle of Phoenix or enjoying the Sedona views, they bridge the gap between slow traditional banks and your urgent needs.
They are the perfect ally for sudden medical bills, urgent home repairs, or unexpected crises. Their streamlined digital and telephone application process ensures you aren’t stuck waiting weeks for a human to glance at your paperwork. It is built for pure efficiency.
Local families have given them a glowing 4.9-star rating, which speaks volumes. People turn to them during their most stressful moments because they need a hand that moves quickly and reliably.
Pros:
- Approvals often arrive within a 24-hour window.
- An impressive 4.9-star rating from local customers.
- Funding ranges from $1,000 up to $25,000.
Cons:
- Final approval depends on their internal credit standards.
- Monthly payments are fixed and may be tight for some.
3. Sun West
Sun West Credit Union operates on a different philosophy. Since they are owned by their members, they possess a deep-rooted commitment to the local community. They view your personal success as a win for the entire group.
Their menu of options is massive, featuring high-yield savings, money market accounts, and intricate mortgage products. They aim to be the only financial partner you ever need, from your first car purchase to your final forever home.
If you are currently battling a low credit score, their secured credit builder tools are a total game-changer. By providing a small cash deposit as collateral, you create a safety net for the lender while proving your reliability to credit bureaus.
This method allows you to climb out of a credit hole without the heavy risks of unsecured borrowing. It is a steady, disciplined way to boost your score over time.
Pros:
- A wide array of products from savings to mortgages.
- Specialized tools designed to repair and build credit.
- Convenient options for both digital and in-person banking.
Cons:
- You might need to meet specific membership requirements.
- Interest rates depend on your unique credit history.
4. Arizona Financial
Arizona Financial is geared toward life’s major milestones. They realize that every financial journey is unique, which is why they provide flexible paths for debt consolidation, vehicle purchases, or buying a home. Their mortgage experts specialize in navigating the complex parts of the process.
They take the mystery out of confusing terms like closing costs, points, or escrow accounts. For a first-time buyer in a growing suburb, having an expert to translate these details can prevent a total financial disaster.
Whether you are looking to refinance for a better rate or buy your first house, they offer the guidance necessary to succeed. They know the local landscape intimately, from the stability of older neighborhoods to the surging prices in Tempe.
Pros:
- Deep expertise in refinancing and home ownership.
- Tailored options for various stages of life.
- Professional mortgage officers to guide your way.
Cons:
- The heavy mortgage focus might not suit quick cash needs.
- Home loans likely require a more established credit profile.
5. Cash Time
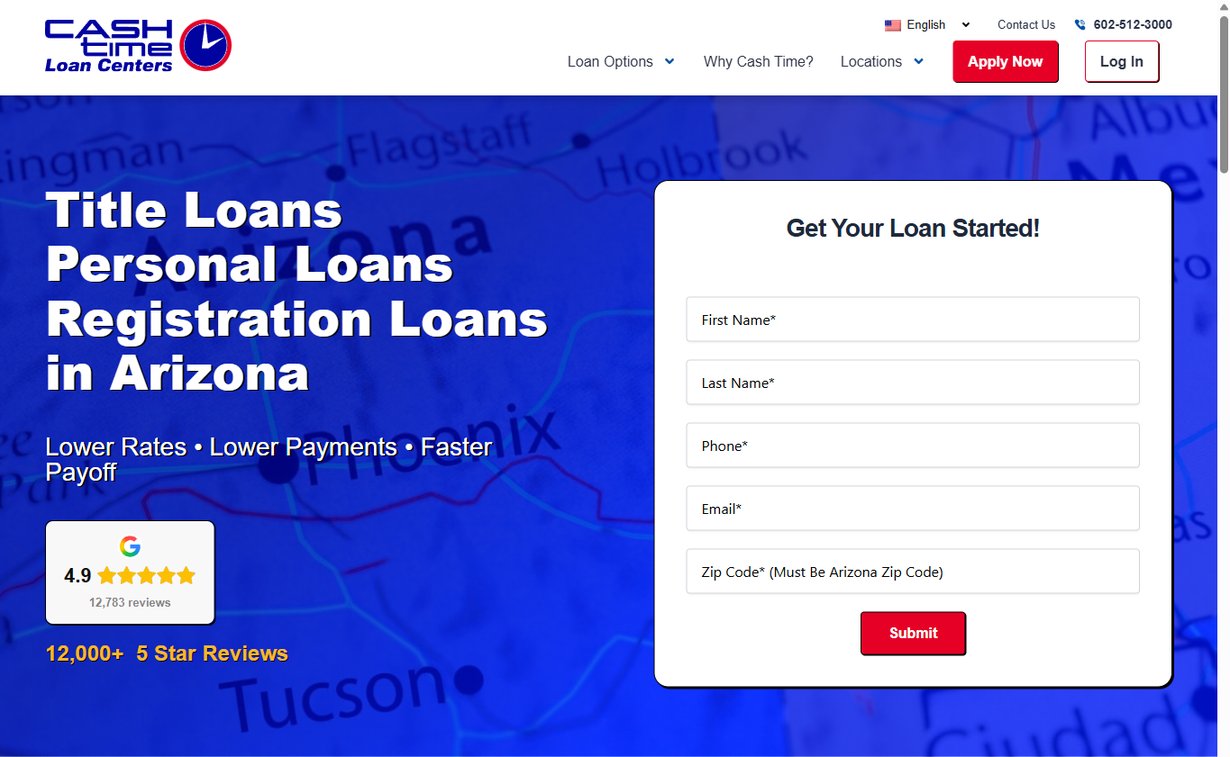
When you are in a real bind and the clock is ticking, Cash Time is a heavy hitter. They specialize in registration and title loans, which is perfect for those who cannot wait days for a bank’s decision. You get cash in hand almost instantly, but there is a catch.
Because a title loan uses your vehicle as collateral, your ride is at stake if you miss a payment. It is a lightning-fast solution, but you must tread carefully to protect your transportation.
They offer massive loan amounts, anywhere from a small $100 up to a whopping $100,000. Their “no problem” stance on bad credit makes them highly accessible for people who have been rejected everywhere else.
Just keep in mind that this level of accessibility usually comes with a higher interest rate. Always weigh that cost carefully before signing the dotted line.
Pros:
- Lightning-fast approvals, sometimes in just 15 minutes.
- Extremely high limits, reaching up to $100,000.
- Specifically designed for those with poor credit.
Cons:
- Your vehicle must be used as collateral for the loan.
- Rapid-funding options often carry very high interest rates.
The Real Price of Your Loan
It is easy to get caught up in the excitement of a low monthly bill. At first blush, a $50 installment seems like a dream compared to a $200 commitment. However, those numbers are often a double-edged sword that can cut your budget deep.
A smaller payment often means you are dancing with debt for a much longer period. While that $200 chunk might vanish in just 6 months, the $50 option could linger on your bank statement for 5 long years. This delay turns a quick fix into a long-term anchor.
When you stretch out the timeline, you end up footing the bill for a much larger sum than you originally borrowed. This figure represents the “total cost of credit.” It is the only metric that truly reflects how much money is leaving your pocket in the long run.
Don’t let the monthly figure blindside you; always keep your eyes on the horizon of the entire loan term.
To uncover the truth, you must demand the Annual Percentage Rate (APR). Think of the interest rate as the tip of the iceberg, while the APR reveals the massive weight lurking beneath the surface. It accounts for both interest and any mandatory service fees.
Imagine a lender promises a 10% interest rate but adds a sneaky $500 fee to the contract. In reality, your APR will skyrocket far beyond that initial 10%. The math changes once those extra costs are baked into the total percentage.
When shopping around for the best terms, use the APR as your primary yardstick. Comparing different offers based on this number is the smartest way to ensure you aren’t getting the short end of the stick.
Steps to Ready Your Loan Request
If an urgent need for cash is looming on the horizon, taking proactive measures today can significantly boost your success rate. Think of this preparation as a roadmap through a financial storm. By getting your ducks in a row now, you prevent future headaches and pave a smoother path toward your fiscal goals.
Start by organizing your essential documentation. Most creditors in the Grand Canyon State will require specific evidence to verify your background. You should gather your paperwork well in advance to avoid any sudden delays during the approval process.
Typically, you will need to present several key items to prove who you are and what you earn:
- A current Arizona driver’s license or a state-issued ID to prove your identity.
- Evidence of your earnings, such as your two most recent W-2 forms, pay stubs, or bank records.
- A recent bill for water or electricity to verify where you currently live.
- Records of any existing liabilities if you intend to consolidate those specific debts.
Next, pull your own credit profile to see what the banks see. You can secure a no-cost report from the primary bureaus to review your standing. If any inaccuracies pop up—such as a collection that doesn’t belong to you—get those errors fixed right away.
Even a single tiny blunder can slash your score by as many as 50 points. This sudden dip could be the difference between getting a great deal at Arizona Zip Loan and facing rejection or higher costs from Sun West. Stay vigilant about your data.
Lastly, pin down the exact amount of funding you truly require. It is incredibly tempting to pad the request with extra cash “just in case,” but this choice only serves to drive up your total interest payments. Don’t let a small loan turn into a massive burden.
Suppose your car needs a new transmission that will run you $1,200. In that scenario, you shouldn’t request $2,000 from a lender. Asking for more than the actual cost is like jumping into a whirlpool; it creates a cycle of debt that is notoriously difficult to escape.
Charting Your Course Through Lending Choices
Do not let the sudden sight of a massive windfall blind you to the fine print. It is incredibly easy to get swept up in the excitement of a quick cash injection, but the true narrative lies in what that capital actually costs you in the long run. Before you put pen to paper, scrutinize every detail carefully.
You should actively inquire about the cumulative expense of the debt and any sneaky charges lurking in the shadows. Specifically, keep a sharp eye out for “prepayment penalties.” Some creditors will actually slap a fee on your head if you attempt to settle the balance ahead of schedule, effectively penalizing your financial discipline.
It sounds like a bitter pill to swallow, but being a diligent borrower shouldn’t come with a surcharge. You want a lender that cheers your progress rather than one that profits when you try to get out of debt faster. Always demand transparency regarding the total amount you will have paid by the time the final installment is made.
Avoid the trap of juggling several different lines of credit simultaneously. This habit often triggers a “debt spiral” that can feel like an inescapable whirlpool. If you find yourself grabbing a title loan to wipe out a credit card, only to take a personal loan to cover that title loan, you are merely spinning your wheels.
In that scenario, you are essentially paying interest on top of interest, which is a recipe for disaster. Instead, aim for a singular, streamlined solution that aligns with your monthly cash flow. A predictable, manageable payment schedule is the cornerstone of maintaining your sanity and your bank account balance.
If you look ahead and can’t visualize yourself meeting the monthly obligations for a full twelve months without sweating, the loan is likely too heavy. Don’t take on more than your shoulders can bear. It is better to seek a smaller amount now than to drown in a sea of mounting interest payments later.

Recent Comments