Notice: Function _load_textdomain_just_in_time was called incorrectly. Translation loading for the wpforms-lite domain was triggered too early. This is usually an indicator for some code in the plugin or theme running too early. Translations should be loaded at the init action or later. Please see Debugging in WordPress for more information. (This message was added in version 6.7.0.) in /home/howhumansthink/public_html/wp-includes/functions.php on line 6131

Notice: Function _load_textdomain_just_in_time was called incorrectly. Translation loading for the salient domain was triggered too early. This is usually an indicator for some code in the plugin or theme running too early. Translations should be loaded at the init action or later. Please see Debugging in WordPress for more information. (This message was added in version 6.7.0.) in /home/howhumansthink/public_html/wp-includes/functions.php on line 6131

Notice: Function _load_textdomain_just_in_time was called incorrectly. Translation loading for the salient domain was triggered too early. This is usually an indicator for some code in the plugin or theme running too early. Translations should be loaded at the init action or later. Please see Debugging in WordPress for more information. (This message was added in version 6.7.0.) in /home/howhumansthink/public_html/wp-includes/functions.php on line 6131

Notice: Function _load_textdomain_just_in_time was called incorrectly. Translation loading for the salient domain was triggered too early. This is usually an indicator for some code in the plugin or theme running too early. Translations should be loaded at the init action or later. Please see Debugging in WordPress for more information. (This message was added in version 6.7.0.) in /home/howhumansthink/public_html/wp-includes/functions.php on line 6131
admin-pro – Page 4184 – Will Steinberg, MD MSPH Skip to main content
All Posts By

admin-pro

Quickly Secure Bad Credit Loans California: Best Fast Approval Lenders

By Uncategorized
Bad credit loans california

Quickly Secure Bad Credit Loans California: Best Fast Approval Lenders

Last updated: 2026-10-16

Navigating your finances in California can often feel like trying to steer through a heavy mist, especially if your credit score isn’t quite where it needs to be. It is a common struggle for many residents who find themselves scrambling to pay for unexpected vehicle maintenance, doctor’s bills, or other pressing living expenses. Too often, traditional big-name banks offer an immediate “no” when you are most vulnerable. This leaves many people searching for alternative paths to bridge the gap between their current income and sudden, mounting costs. Whether it is a sudden transmission failure while driving through Los Angeles or an unexpected medical deductible in San Diego, financial emergencies rarely wait for a convenient time. They strike like lightning, leaving you grasping for immediate liquidity to keep your life moving forward. Finding a suitable lender requires more than just glancing at shiny advertisements. You must dive deep into the fine print, scrutinizing interest rates and the actual speed of fund disbursement to ensure you aren’t being misled by flashy promises. It is incredibly easy to fall for a “low monthly payment” sales pitch that sounds like a lifeline. However, your true total cost of borrowing is dictated by the length of your term and the Annual Percentage Rate (APR). Don’t let the marketing jargon cloud your judgment. Understanding how these factors interact is the only way to avoid a mountain of debt that feels impossible to climb later on. This selection outlines the premier choices for Californians seeking flexibility. These lenders offer a realistic possibility of approval, even for those navigating a rather bumpy financial journey.

  1. OneMain Financial
  2. Avant
  3. FastLoans CA
  4. Upgrade
  5. VivaLoan
  6. GreendayOnline
  7. United Finance

Scrutinizing California Lending Options for Low Credit Scores

Finding a trustworthy lender is like searching for a needle in a haystack when your credit history is less than stellar. We decided to weigh several critical metrics to see who actually stands up to scrutiny. Our investigation prioritized how accessible these services are for those with suboptimal ratings. We also looked at how quickly cash lands in your pocket.

Transparency is the name of the game when you are navigating financial waters. You should never be left in the dark regarding whether a company will perform a hard credit pull during your initial inquiry. Knowing this detail upfront can be the difference between a smooth experience and a sudden shock to your financial standing.

A soft pull is your best friend because it allows you to gauge your potential rates and eligibility without any penalty to your score. It’s a harmless glance at your data. Conversely, a hard pull occurs when an institution conducts an intensive investigation of your credit profile for a formal loan request. This specific action can lead to a momentary drop in your numerical rating.

Understanding this nuance is vital to protect your credit score from needless erosion. We also dug deep into the math behind the money. A massive loan limit sounds enticing, but it can be a wolf in sheep’s clothing if the interest rates are predatory. It can turn a simple loan into a mountain of debt that is impossible to climb.

Consider how the numbers play out over time. For example, a $5,000 loan carrying a 36% APR over a 36-month span will cost you significantly more in interest than a $5,000 loan with a 15% APR over that same duration. We have ranked these providers based on their commitment to fair structures and straightforward, honest processes.

Financial Institution Borrowing Limits Speed of Funding Credit Standards Primary Advantage
OneMain Financial $1,500 – $30,000 Within 1 hour Refer to website Local branch access
Avant Refer to website Refer to website Refer to website Versatile options
FastLoans CA $1,000 – $35,000 Within 24 hours No hard credit pull California authorized
Upgrade Up to $50,000 Refer to website Refer to website Debit card cash back
VivaLoan $100 – $15,000 By the next day All credit types welcome Small minimums
GreendayOnline $100 – $5,000 Within the same day No credit check Rapid emergency funds
United Finance Up to $20,000 Refer to website Refer to website Operational since 1922

Distinguishing Between Collateralized and Non-Collateralized Borrowing

Navigating the lending landscape in California often feels like walking a tightrope. You will inevitably encounter two primary categories of debt: secured and unsecured options. Grasping the nuances between these two paths is essential for your lasting fiscal stability and how you handle potential pitfalls.

Think of it as choosing between a minor inconvenience and a total catastrophe. One path leaves your belongings safe, while the other puts them on the line. Understanding this distinction is the first step toward making a smart move with your money.

When you opt for an unsecured loan, such as the personal loans offered by Upgrade or Avant, you aren’t required to provide collateral. You won’t find yourself handing over your home deed or your car’s title just to secure the funds. It is a straightforward transaction without the heavy baggage of physical assets.

However, there is no such thing as a free lunch in the banking world. Since these lenders face a higher risk of non-payment without an asset to grab, they typically charge steeper interest rates. For many residents across the Golden State, the ability to protect their property makes these higher costs worth the peace of mind.

On the other hand, a secured loan demands that you pledge something valuable, such as a savings account or a vehicle, as security. This asset acts as a safety net for the lender. If you find yourself unable to meet your monthly obligations, the creditor possesses the legal authority to take that property to recover their funds.

It is a classic trade-off of risk versus reward. While these types of loans frequently boast more favorable interest rates, losing your primary mode of transportation could derail your entire life. Before signing any paperwork, carefully balance the benefit of a lower rate against the terrifying possibility of losing your hard-earned possessions.

Leading Lending Options for California Residents

1. OneMain Financial
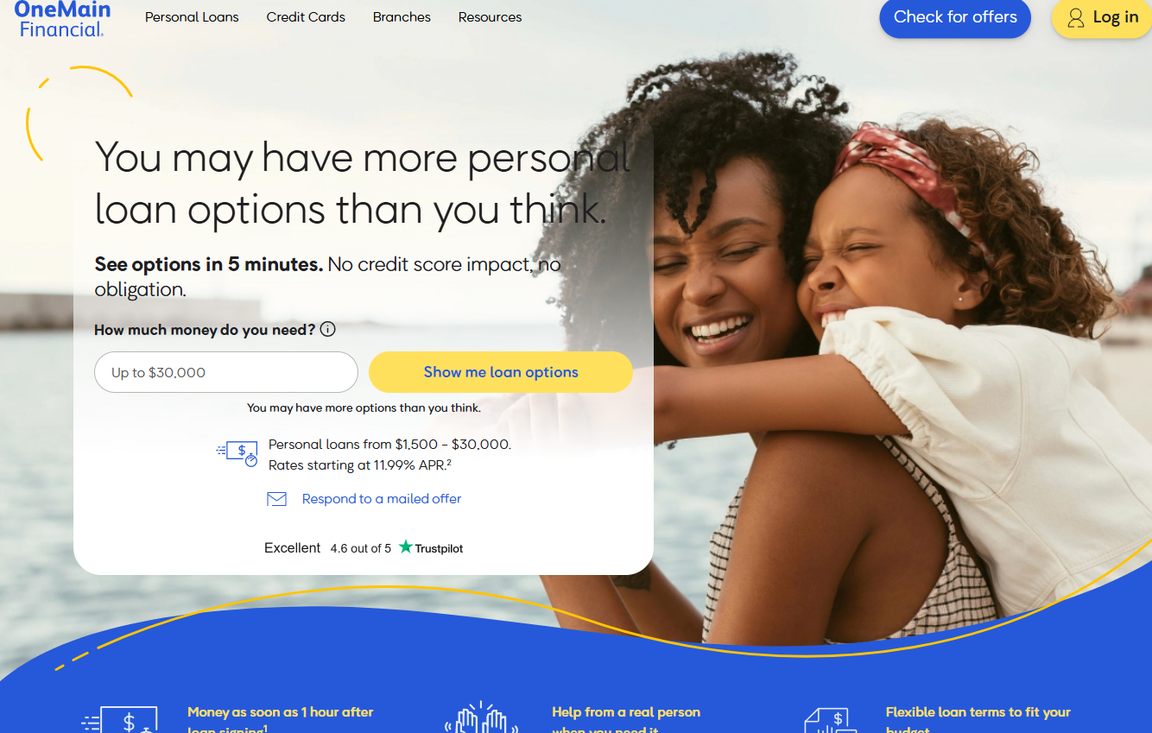
OneMain Financial – onemainfinancial.com

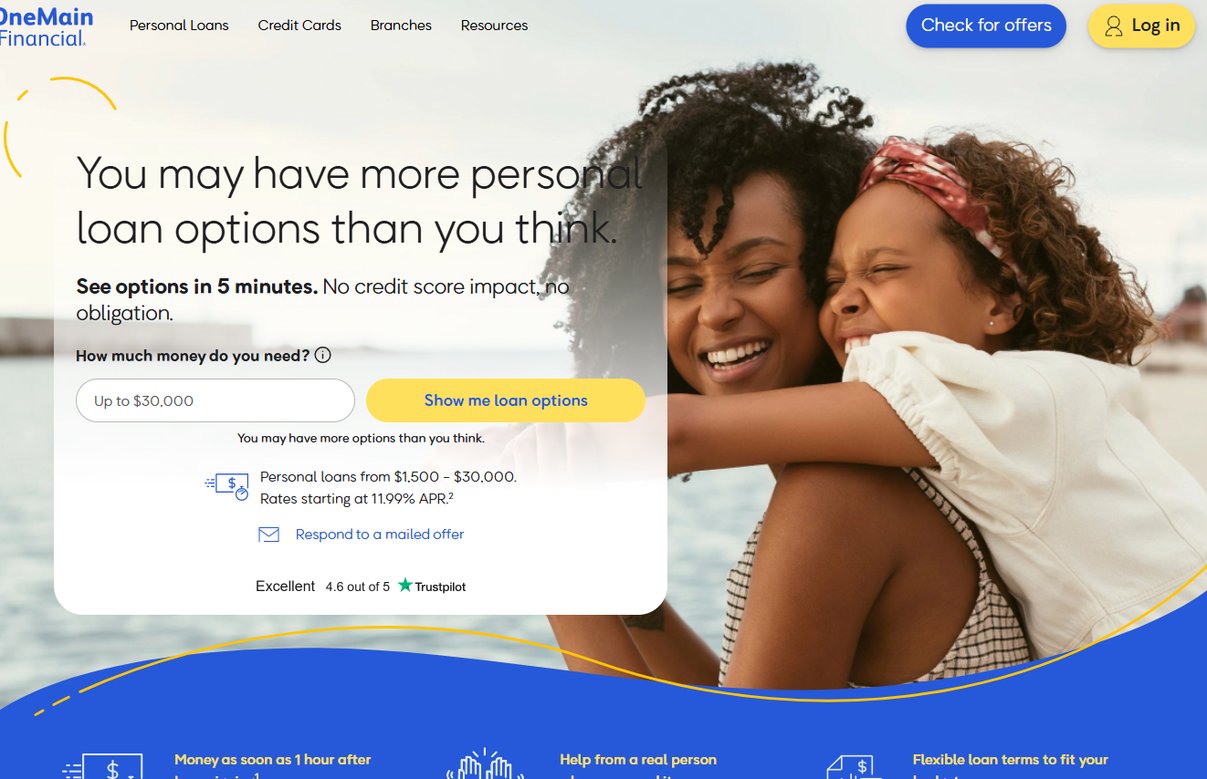
If you’re the type of person who prefers a handshake over a digital signature, OneMain Financial might be your best bet. They bridge the gap between modern technology and old-fashioned service through a massive network of over 1,300 local branches. It’s a comforting feeling to walk into an office rather than clicking through a screen when your finances are on the line.

For residents in Fresno or Sacramento, having a physical location nearby can make all the difference in the world. Sitting down with a professional helps clear up the fine print and builds a foundation of trust that many purely online companies just can’t match. You can secure personal loans ranging from $1,500 all the way up to $30,000 to tackle those heavy financial burdens.

Budgeting becomes much less of a headache with their fixed monthly installments. With terms that stretch from 24 to 60 months, your costs won’t fluctuate even if the economy throws a curveball. Starting at 11.99% APR, these loans offer a structured path to getting your finances back on track without any nasty surprises later on.

Pros:

  • Wide-reaching physical network for face-to-face assistance.
  • Rapid disbursement, potentially within an hour of signing.
  • Predictable monthly payments for easier financial planning.

Cons:

  • Involves more hands-on interaction than most digital-only lenders.

2. Avant
Avant – avant.com

Think of Avant less as a lender and more as a financial companion. Rather than just handing over cash, they provide a toolkit designed to help you make progress. Whether you need a fresh credit card or a loan to consolidate what you already owe, they focus on your long-term trajectory.

This makes them a stellar choice if you’re tired of chasing multiple high-interest monthly payments. They realize that life isn’t one-size-fits-all, so they offer a variety of paths, from tackling debt to funding home improvements or handling sudden emergencies.

Their digital-first platform is a dream for the busy person on the move. You can manage your entire financial life while grabbing a coffee or riding the train. It’s a seamless way to find the specific tools you need to steady your ship and move forward.

Pros:

  • Prioritizes your ongoing financial growth.
  • Provides a diverse range of products like loans and credit cards.
  • Boasts a very intuitive digital experience.

Cons:

  • Upfront details on specific rates and terms can be a bit elusive.

3. FastLoans CA
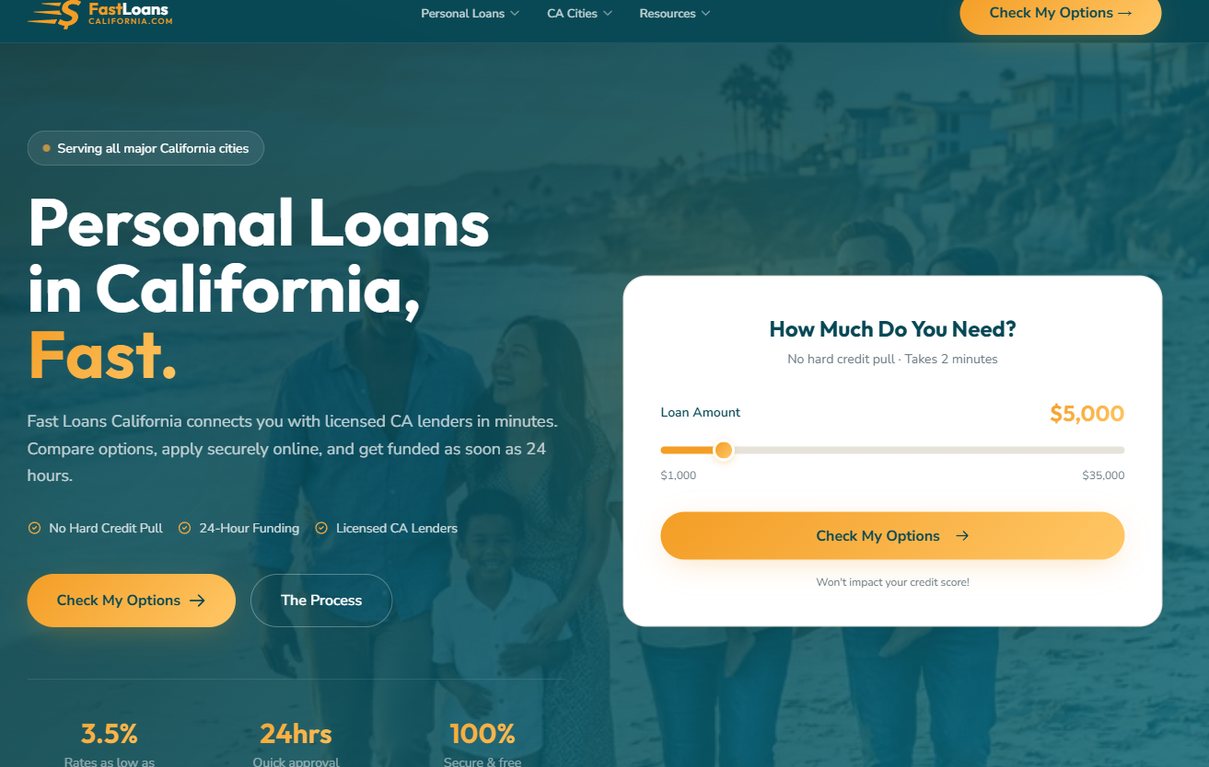
FastLoans CA – fastloanscalifornia.com

When you’re facing a sudden crisis, FastLoans CA acts as a bridge to licensed lenders throughout the Golden State. They understand that time is of the essence, often aiming to get funds into your hands within 24 hours. You can check your eligibility in just a few minutes.

Imagine your pipes burst or a medical bill arrives out of nowhere; that’s where this speed becomes a lifesaver. Best of all, checking your options won’t ding your credit score because they don’t use hard credit pulls for the initial inquiry. You can shop around with peace of mind.

With loan caps reaching $35,000, they cover everything from a quick fix to a major household overhaul. Because they focus specifically on California, they are well-acquainted with local laws, offering an extra layer of security for the people they serve.

Pros:

  • Inquiry process does not impact your credit score.
  • Extremely quick approval and funding turnaround.
  • Dedicated service for a huge number of California families.

Cons:

  • Interest rates may be notably higher than standard bank loans.

4. Upgrade
Upgrade – upgrade.com

A powerhouse in the lending world, Upgrade has helped over 8 million people navigate their finances. With loan amounts hitting up to $50,000, they are a heavy hitter for those tackling major life transitions or massive debt consolidation projects. If you’re looking to roll several high-interest cards into one, their high limits are a massive plus.

They do more than just lend money; they offer a complete ecosystem, including checking accounts that can pay you back with 2% cash on your purchases. This creates a unique opportunity to blend your borrowing needs with your everyday banking habits seamlessly.

By keeping your banking and your loan under one roof, you can see your whole financial picture in a single dashboard. This is a huge time-saver for anyone who finds managing five different apps to be a total headache.

Pros:

  • Substantial loan limits reaching $50,000.
  • Offers rewarding checking accounts alongside loans.
  • Allows for quick rate checks without affecting your credit.

Cons:

  • The most competitive rates are usually reserved for those with better credit.

5. VivaLoan
VivaLoan – vivaloan.com

Sometimes, you don’t need a mountain of cash; you just need a small helping hand. VivaLoan excels at providing smaller, bite-sized loans starting at just $100. It’s the perfect solution for a quick fix, like replacing a blown tire, without the weight of a massive debt hanging over you.

Speed is their middle name. The application process takes roughly five minutes, and if you’re approved, the money is usually in your account by the next business day. It’s a reliable lifeline for when you need cash almost instantly.

The beauty of their system lies in its simplicity. By cutting through the red tape that usually defines traditional banks, they make it incredibly easy for people to solve a sudden problem and move on with their lives.

Pros:

  • Very accessible minimums starting at only $100.
  • Funds are often delivered by the very next business day.
  • The application is incredibly straightforward and fast.

Cons:

  • Loan ceilings are somewhat limited at $15,000.

6. GreendayOnline
GreendayOnline – greendayonline.com

When a financial emergency is staring you in the face, GreendayOnline provides specialized installment loans designed for urgent situations. They specifically cater to those with less-than-perfect credit by skipping the hard credit checks. For many, this is a vital lifeline when traditional banks have closed their doors.

This is often the final option for those dealing with significant credit damage or active bankruptcy. With amounts from $100 to $5,000, they provide the quick liquidity needed for immediate crises. Their web form is streamlined to ensure you get a decision quickly.

While these are high-speed options, they function as installment loans. This means instead of a single massive payment, you can spread the repayment out over time, which is much more manageable than a typical payday loan structure.

Pros:

  • Approvals don’t require hard credit checks.
  • Potential for same-day cash when you need it most.
  • Simple and incredibly easy-to-use online platform.

Cons:

  • Interest rates on these installment loans can be quite steep.

7. United Finance
United Finance – unitedfinance.com

United Finance offers a sense of enduring stability, having been around since 1922. In an era of fly-by-night digital lenders, their century of experience offers a comforting sense of permanence. There is a unique peace of mind that comes with knowing a company has weathered every economic storm for decades.

They provide a range of products, including personal loans up to $20,000 and various auto loan options. Their philosophy is built on simplicity and accessibility, making them a great choice for anyone seeking a traditional, reliable lending experience.

Having survived everything from the Great Depression to the digital revolution, their longevity speaks volumes. This history can be incredibly reassuring for cautious borrowers who are wary of unproven online startups that might vanish overnight.

Pros:

  • A long, established history in the finance industry.
  • Offers both auto and personal loan varieties.
  • Provides a personal touch in their lending approach.

Cons:

  • Lacks some of the high-tech, instant-only digital features.

How to Boost Your Approval Odds

Even when your credit score isn’t exactly shining, you can still tilt the scales in your favor. It is a common misconception that a low FICO score is a total dead end. Most lenders actually peek at your capacity to settle your debts rather than just looking at a single number.

Walking into an application unprepared is like sailing into a storm without a compass. By doing your homework beforehand, you can avoid a trail of rejected requests. Every time a lender pulls your report, it leaves a tiny mark on your record, so being selective is key.

Before you even sit down to click “submit,” make sure you have your paperwork organized in a neat pile. You will generally need to provide:

  • A legitimate ID issued by the government, such as a passport or driver’s license.
  • Evidence that you live in California, like a lease or a recent utility statement.
  • Documentation of your earnings, which might include bank statements or your two most recent pay stubs.
  • Your Social Security number to confirm you are who you say you are.

Making sure your paychecks are easy to track is vital. For those navigating the gig economy or freelance life, the path can be a bit rockier. If you can show a steady stream of deposits or neatly filed tax documents, you might just turn a “no” into a “yes.”

Another crucial step involves checking your debt-to-income ratio (DTI). Think of this as a measure of how much of your paycheck is already spoken for by other lenders. If your monthly obligations eat up too much of your gross income, it’s a red flag for most banks.

It might be worth it to clear a small balance on a credit card before you start this process. Reducing that debt slightly can polish your financial profile. A better DTI makes you look much more stable when the lender begins their investigation into your finances.

Dodging Financial Traps

Before you ink your signature on any legal documents, you must grasp the full price tag of your debt. It is easy to get blinded by a small monthly installment that seems to fit your budget perfectly. However, a stretched-out repayment timeline can be a wolf in sheep’s clothing for your wallet.

Consider a scenario where you borrow $5,000. A $200 monthly bill feels like a breeze, but if that agreement spans 36 months, your total output hits $7,200. That extra $2,200 is the actual toll you pay for that credit. Never let a low monthly figure distract you from the bottom line.

Always demand the lender clarify the total repayment amount in a flat dollar figure rather than just the monthly chunk. If you only look at the monthly payment, you are essentially flying blind. It is like looking at the tip of an iceberg while ignoring the massive mass beneath the surface.

Don’t rush headlong into a deal without scrutinizing the fine print. Some companies bury administrative charges or hidden levies within the text. These sneaky costs can balloon your debt before you even have a chance to settle the balance.

Keep a sharp eye out for “prepayment penalties.” These are essentially fines that companies slap on you if you attempt to settle your debt ahead of schedule. It feels like being penalized for being financially responsible, which is a bitter pill to swallow.

You deserve the liberty to crush your debt early and bypass heavy interest charges without being slapped with extra fees. Take a moment to pause and weigh different APRs against one another. Make sure the debt’s architecture aligns with your real-world earnings and lifestyle.

Being diligent during the application phase acts as a shield for your future self. Taking an extra hour to read now prevents a massive headache from blooming down the road. It is better to be cautious than to find yourself trapped in a cycle of endless interest.
Get Fast Cash with Bad Credit Loans New York Residents Can Access Today

By Uncategorized
Bad credit loans new york

Get Fast Cash with Bad Credit Loans New York Residents Can Access Today

Last updated: 2026-10-17

Navigating your finances within the five boroughs can feel like dodging taxis in a sudden downpour. When your credit score isn’t exactly stellar, locating a lender that won’t immediately slam the door can seem like an impossible feat. Between the relentless price of living in the city and those sudden, stomach-churning medical costs, cash is often needed yesterday.

This resource is crafted specifically for residents dealing with unforeseen costs who require dependable solutions. You shouldn’t find yourself trapped between a rock and a hard place by choosing between rent and predatory street-corner lenders. Balancing quick access to funds with reasonable rates is the ultimate way to keep your head above water in this frantic urban jungle.

Choosing your lender involves much more than a quick glance at the interest percentage. You must carefully weigh the velocity of the deposit against how much that debt will ultimately cost you. A cheap rate means nothing if the bank takes a fortnight to transfer funds while your landlord is knocking at the door.

On the flip side, a loan that arrives in a heartbeat might carry massive APRs that leave you drowning in repayments. We examine how these companies approach credit inquiries, their speed of fund distribution, and whether their contracts are crystal clear or riddled with fine-print surprises. We judge them based on how they function for real people in the city.

Our aim is to pierce through the flashy advertising to identify genuine financial tools. We focus on what actually works when life throws you a curveball. Use these insights to navigate your way toward a smarter financial future without the typical headaches.

  1. SkyOne
  2. United Finance
  3. JetzLoan
  4. Experian
  5. GreendayOnline

How These New York Loan Options Were Evaluated

The evaluation process focused on accessibility for individuals with less-than-perfect credit scores. We looked at whether a lender performs a hard credit pull during the initial inquiry phase. This matters because a hard pull can impact your score before you even know if you are approved. In a competitive market like New York, where credit utilization and score fluctuations are closely watched, a “soft pull” for quotes is a vital safeguard.

Speed of funding is also a massive factor for those in urgent situations. Whether it is a car repair needed to get to work or a sudden utility shut-off notice, time is of the essence. We prioritized lenders that move quickly without sacrificing the transparency of their terms. We wanted to see who actually gets money into your account when you need it most.

We also scrutinized the range of loan amounts available to ensure a variety of needs are met. A $500 loan might fix a broken appliance, but a $25,000 loan might be necessary to consolidate high-interest credit card debt that is stifling your monthly cash flow. We prioritized clarity regarding repayment terms to ensure the lenders listed provide a genuine service rather than a debt trap.

We specifically looked for indicators of “predatory lending,” such as excessive origination fees that are tacked onto the principal. We also checked for a lack of clarity regarding the total cost of credit over the life of the loan. If a lender hides the real cost behind fine print, they didn’t make our list.

Lender Name Loan Amounts Funding Speed Credit Requirement
SkyOne $500 – $50,000 see site Personal Loans available
United Finance see site see site Installment loans available
JetzLoan $500 – $35,000 As little as 24 hours No hard credit pull
Experian $2,000 – $50,000 Same-day funding available see site
GreendayOnline $100 – $5,000 As soon as the same day Bad credit welcome

Top-Rated Lending Providers for Your Needs

1. SkyOne

SkyOne – skyone.org

Operating as a federal credit union, SkyOne brings a more human touch to the world of personal finance. Instead of relying solely on cold, automated rejection algorithms common in big banks, they treat members with a holistic perspective. This community-centric approach often opens doors that traditional commercial lenders might slam shut.

Whether you need a personal loan or a flexible line of credit, their products act as a vital lifeline. Many clients use these funds to steady their shaky financial footing. If you are staring down a massive debt pile or planning a major home renovation, their limits reach as high as $50,000.

The interest rates are quite refreshing, starting as low as 13.99% APR. When you compare that to the predatory rates on high-interest credit cards, it feels like a breath of fresh air. This makes them an excellent choice for funding significant life milestones, such as a new vehicle down payment.

Choosing this institution means opting for a collaborative partnership rather than an impersonal transaction. They are a rock for those chasing long-term stability. If you want a lender that feels like a neighbor rather than a giant corporation, this is your best bet.

Pros:

  • Personal loan APRs begin at a competitive 13.99%.
  • Borrow up to a maximum of $50,000.
  • Provides flexibility through both loans and lines of credit.

Cons:

  • You may need to meet specific credit union membership criteria.

2. United Finance

United Finance – unitedfinance.com

Since 1922, United Finance has been a cornerstone of the lending industry, bringing a century of wisdom to every application. They focus heavily on installment loans, which offer a predictable rhythm for your repayments. Unlike the chaotic cycle of payday loans, these fixed payments of principal and interest make budgeting a breeze.

This structure is a total departure from revolving debt. With payday loans, interest can snowball so fast that you feel like you are running on a treadmill that never stops. United Finance emphasizes ethical practices, frequently warning consumers about scammers attempting to steal their identity by mimicking their brand.

This commitment to security is a godsend for New Yorkers who are constantly dodging predatory phishing texts or emails. Their long history means they have survived countless economic storms. That institutional stability is something many newer fintech startups simply cannot claim to offer.

If you want a traditional, dependable lending experience, they are a very solid choice. You get the peace of mind that comes with knowing exactly what your monthly obligation will be. It is a steady hand in an unpredictable financial world.

Pros:

  • Boasts a massive reputation built since 1922.
  • Prioritizes installment loans over high-risk payday options.
  • Maintains a fierce stance on fraud prevention and consumer security.

Cons:

  • Availability is restricted to certain states, including Nevada and Oregon.

3. JetzLoan

JetzLoan – jetzloan.com

When you are in a tight spot and need cash yesterday, JetzLoan is the fast lane. They specialize in bridging the gap between you and top-tier lenders in mere minutes. The real magic here is their ability to let you check your rate without a hard credit pull.

This “pre-qualification” step is a total game-changer for your credit score. Most people walk on eggshells, fearing that every application will cause a nasty dip in their rating. With JetzLoan, you can window-shop for the best terms while keeping your credit report perfectly intact.

Forget about the mountain of paperwork found at a dusty brick-and-mortar bank. Their digital setup is built for the modern, frantic lifestyle. You can whip through the two-minute application while riding the subway or waiting for coffee. It is streamlined for ultimate efficiency.

If you are in a rush, this is your go-to solution. Funds can land in your bank account in as little as 24 hours. For those who simply cannot afford to wait for the slow-moving gears of traditional banking, this speed is a lifesaver.

Pros:

  • Initial rate checks do not require a hard credit pull.
  • Rapid funding, with many seeing cash in 24 hours.
  • A lightning-fast, two-minute application process.

Cons:

  • Total borrowing is capped at $35,000.

4. Experian

Experian – experian.com

Experian is a household name when it comes to the science of credit, and their loan offerings reflect that deep-seated expertise. They understand the complex math behind your score better than just about anyone. They provide personal loans from $2,000 all the way up to $50,000.

Flexibility is their middle name, with repayment windows ranging from 24 to 72 months. This is a massive advantage if you are trying to balance a tight monthly budget. While a longer term lowers your monthly payment, remember it does mean you pay more in total interest over time.

They are a powerhouse for anyone looking to rehabilitate their financial standing. By utilizing their specialized credit-boosting tools—which can report on rent or utility payments—you can actively work on your score. It is about working smarter, not harder, to improve your credit profile.

Think of it as a virtuous cycle for your wallet. You use a loan to clear a hurdle, then use Experian’s ecosystem to climb even higher. It is a way to take a temporary financial stumble and transform it into a long-term leap forward.

Pros:

  • Certain loan types qualify for same-day funding.
  • Repayment windows are flexible, lasting up to 72 months.
  • Includes built-in tools designed to boost credit scores.

Cons:

  • An increase in your score or loan approval is never a certainty.

5. GreendayOnline

GreendayOnline – greendayonline.com

GreendayOnline is built for those needing a quick, small injection of cash to cover a sudden gap. They provide installment loans between $100 and $5,000. This is a niche service tailored for those “oh no” moments where speed and ease are the only things that matter.

While this won’t help you tackle a massive mountain of debt, it is perfect for bridging the gap between paychecks. The entire journey happens online, which is incredibly convenient for a busy New Yorker on the move. They don’t shy away from applicants with bad credit.

Instead of a grueling, traditional application, they provide a straightforward path to quick cash. It is an essential fallback for anyone who has been stung by credit setbacks in the past. If you just need a little extra help to make it to next month, they are ready.

Pros:

  • Very low entry point, with loans starting at just $100.
  • Quick approvals and same-day cash availability.
  • Specifically tailored to help those with bad credit.

Cons:

  • The maximum loan amounts are quite small compared to other lenders.

Navigating Your Loan Choices: A Tactical Roadmap

Staring at a pile of different loan documents can feel like trying to solve a puzzle in the dark. Between the shifting numbers and varying deadlines, it is easy to get lost in the weeds. You need a clear strategy to separate the golden opportunities from the traps.

Instead of letting the data wash over you, try to slow down and dissect each offer piece by piece. Taking a methodical approach ensures you don’t sign away your financial peace of mind just to get a quick fix. Here is how to stay ahead of the game.

Think of it as a checklist for your wallet. By looking at the fine print through a different lens, you can find the terms that actually suit your life. Don’t just take the first handshake you’re offered; make sure the math actually adds up in your favor.

  • Prioritize the APR Over Interest Rates: It is a common trap to only watch the interest rate, but that only tells half the story. While that number represents the cost of the principal, the Annual Percentage Rate (APR) is the real truth because it incorporates extra costs like processing or origination fees. Always use the APR to weigh one deal against another.
  • Identify Your Hard Budget Ceiling: Before you dive into a contract, take a hard look at your monthly cash flow. If your budget only has room for a $150 increase each month, steer clear of a deal requiring a $200 installment, even if the interest looks tiny. Don’t let a “good” rate push you into a deficit.
  • Scan for Early Repayment Fees: Some companies will punish you for being responsible by charging prepayment penalties if you settle your debt early. If you are anticipating a windfall like a tax return or a work bonus, ensure your chosen loan allows you to clear the balance ahead of schedule without any extra costs.
  • Confirm the Exact Payout Schedule: In a crisis, timing is everything, so don’t settle for vague promises. Ask the lender, “When exactly will the cash be sitting in my bank account and ready for use?” Remember that being officially “approved” is quite a different beast than having the actual funds cleared and ready.

Navigating the Hidden Traps of the New York Credit Landscape

Trying to find a loan in the concrete jungle can feel like walking through a minefield of fine print. Many lenders in the city use high-pressure psychological plays to force a quick signature. They might bombard your phone with incessant calls or use scare tactics, claiming you will miss out on funds if you do not act instantly.

A legitimate company won’t try to corner you like a street hustler. Instead, they maintain a professional demeanor and grant you the space to review every clause. If someone is shouting about your “final opportunity” to secure cash, take a step back. It is often a red flag rather than a genuine offer.

One dangerous habit that many New Yorkers fall into is the cycle of “loan stacking.” This is essentially playing a high-stakes game of musical chairs with your debt. You take a new, expensive loan to settle an old one, thinking you have found a way out of the woods.

In reality, you are merely shifting the weight of your debt around while the interest rates continue to snowball. It feels like a temporary fix, but it is actually a recipe for a financial disaster. If your strategy involves borrowing more to pay off what you already owe, stop immediately and reach out to a debt counselor.

Finally, do not let a slick website fool you into thinking an online lender is trustworthy. A beautiful, modern interface is nothing more than digital window dressing. It is the bare minimum requirement for any business operating in the modern age.

You must dig a little deeper to ensure they are actually registered to work within New York state regulations. Check for a verifiable physical office and hunt for authentic feedback from past customers. True stability is found in a long-standing reputation and absolute transparency, not just a pretty web design.

Making Smarter Choices with Your Credit

Before you ink your signature on any contract, try to slow down and catch your breath. The rush of getting a fast “yes” can feel like a shot of adrenaline, but you need to keep a cool head. It is vital to scrutinize the true price of every cent you borrow.

Don’t let the shiny numbers on the advertisement fool you. You should always demand clarity regarding any hidden costs, such as prepayment penalties or origination fees. These sneaky additions can make a loan much pricier than it initially appeared to be.

For instance, imagine you secure a $1,000 loan, but the lender demands $100 in upfront fees just to hand over the cash. In reality, that money is far more expensive than the interest rate suggests on paper. Always look past the surface level to see the real financial impact.

Resist the urge to grab several tiny loans from various lenders just to settle one massive debt. This approach is a slippery slope that often leads to a financial tailspin from which it is incredibly hard to climb out. It’s like trying to put out a fire by throwing more gasoline on it.

Whenever you can, aim to bundle your various debts into a single, consistent monthly installment. This strategy keeps your household budget predictable and prevents your stress from skyrocketing. It is much better to handle one clear obligation than to juggle a messy pile of different due dates and fluctuating rates.

Get Quick Loans for the Unemployed with Bad Credit Today

By Uncategorized
Loans for the unemployed with bad credit

Get Quick Loans for the Unemployed with Bad Credit Today

Last updated: 2026-10-16

Getting laid off hits like a ton of bricks. One day you are thriving, and the next, you are staring at a growing pile of invoices that simply do not care that your income has evaporated. It is a gut-wrenching experience that leaves many feeling like they are drowning in a sea of mounting debt.

The fear isn’t just about trimming your luxuries; it is about the fundamental need for shelter and warmth. When that regular direct deposit stops arriving, the pressure to settle rent or electricity costs can become truly overwhelming. It feels like trying to walk a tightrope during a thunderstorm.

You are essentially performing a frantic balancing act. You must find a way to settle your immediate debts while desperately trying to preserve some shred of long-term solvency. It is a high-stakes game where the rules seem rigged against those facing sudden hardship.

Adding a bruised credit score to this mix is like pouring gasoline on a fire. Standard banking institutions tend to slam the door shut the second they notice a lapse in your employment or a dip in your rating. To them, a lack of a steady job is just a red flag for potential non-payment.

Most large-scale lenders use rigid algorithms that trigger instant denials for anyone without a traditional paycheck. They view unemployment as a high-risk gamble they aren’t interested in taking. This leaves many people feeling completely abandoned by the traditional financial system.

We have put together this review to highlight which providers actually offer a lifeline for those navigating these murky financial waters in 2026. The following companies might provide the breathing room you need right now.

  1. Avant
  2. Upgrade
  3. FastLendGo
  4. Wells Fargo
  5. NetCredit
  6. OneMain Financial

Our Selection Methodology

Finding the right lender requires digging beneath the surface of flashy marketing campaigns. We prioritized speed of disbursement and how accommodating the signup process truly is. For anyone currently between roles, the ability to present bank statements instead of standard pay stubs is a game-changer.

Being able to prove your financial reliability without a traditional boss can be the difference between a successful application and an immediate decline. We looked closely at how lenders validate income via third-party data aggregators. This technology serves as a vital safety net for freelancers or anyone with a fluctuating paycheck.

Instead of asking “does this person have a job?”, these lenders ask “can this person manage their debt?” This fundamental shift in perspective is crucial for those without a conventional salary. It turns a potential roadblock into a navigable pathway.

Honesty is paramount in this industry. A company might promise instant cash, but if the interest is predatory, you’re just digging a deeper hole. We avoided lenders that hide the true cost of borrowing behind long-term extensions.

For example, a low monthly bill might look enticing, but a 72-month term can cause you to pay back double the original principal. Our goal was to find a sweet spot between credit accessibility and sustainable, fair repayment terms.

Provider Credit Limit Terms & Interest Disbursement Time Credit Criteria
Avant See site See site See site Bad Credit Options
Upgrade Up to $50,000 See site Fast funding See site
FastLendGo $500 – $5,000+ See site Quick access Bad/Fair/Good
Wells Fargo See site See site See site Traditional Requirements
NetCredit Up to $10,000 See site Same-day available Advanced Algorithms
OneMain Financial $1,500 – $30,000 From 11.99% APR As soon as 1 hour See site

1. Avant

Avant – avant.com

Avant attempts to provide a stepping stone for people navigating life’s unexpected turbulence. Their product suite includes various installment loans and credit cards designed for those seeking a financial reset. Unlike the rigid structures of massive banks, they utilize a unique proprietary model.

Rather than focusing exclusively on a static FICO number, they scan a broader spectrum of financial health indicators. This nuanced view makes them an excellent tool for consolidating debt or building an emergency cushion. If a sudden car repair threatens your ability to attend job interviews, they provide a way out.

They also cater well to those managing inconsistent income streams or transitioning between employment. It is a pragmatic solution for anyone looking to tidy up several high-interest obligations into one manageable monthly bill.

Pros:

  • Diverse loan products tailored to various needs
  • Complementary credit card availability
  • Designed to facilitate financial progress
Cons:
  • Standard rates aren’t always transparently listed online

2. Upgrade

Upgrade – upgrade.com

A heavy hitter in the personal lending space, Upgrade provides significant capital, reaching up to $50,000. Their funds can cover anything from major home renovations to one-off large expenses. Their entire digital infrastructure is built around rapid delivery to the borrower.

One standout feature is their ability to offer rate checks in mere minutes without any damage to your score. They achieve this through a “soft pull” mechanism for the initial evaluation. This is a massive advantage when you are comparing different offers to find the best deal.

Shopping for terms becomes a stress-free endeavor because you aren’t accumulating a mountain of “hard inquiries” that could tank your rating. They also feature a checking account that rewards you with cash back on debit spending, acting as a comprehensive financial ecosystem.

For those needing substantial funds to wipe out existing debt or jumpstart a project, the process is incredibly slick. Since the application is optimized for mobile devices, it is perfect for people who rely on smartphones rather than traditional desktop computers.

Pros:

  • Large borrowing capacity up to $50,000
  • Check rates quickly without hurting your credit
  • Added value through checking account rewards
Cons:
  • Top-tier interest rates may require higher credit

3. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo is a reliable partner for those facing urgent, smaller financial hurdles. Their specialty lies in modest personal loans, with entry points starting at just $500. This makes them an ideal choice for immediate needs like dental work, auto repairs, or utility deposits.

Because these loans aren’t massive, the barrier to entry is often much lower than at a giant commercial bank. They have streamlined their online interface so you can weigh your options in a snap. (fastlendgo.com)

Whether your credit profile is considered good, fair, or poor, there is likely a product tier meant for you. For example, if you maintain a “fair” score but have a history of consistent income, you might secure better terms here than elsewhere.

They offer a rapid infusion of cash for people in a pinch, helping to prevent a small problem from spiraling into a catastrophe. It is about providing immediate relief for pressing, real-world issues.

Pros:

  • Low starting point for small-scale needs
  • Tailored for specific emergencies like auto or dental
  • Easy comparison of localized lending options
Cons:
  • Small loan limits may not cover heavy debt

4. Wells Fargo

Wells Fargo – wellsfargo.com

Wells Fargo stands as a titan in the financial world. As a cornerstone of American banking, they provide an array of services ranging from basic checking to specialized auto and home financing. They offer a level of physical stability and institutional presence that many newer apps cannot replicate.

However, for those currently without a job, securing a loan here can feel like climbing a mountain without gear. Traditional banks usually demand two years of continuous, documented work history and a specific debt-to-income balance. They are generally risk-averse when it comes to unverified income.

That said, once you have secured a new position, they become an excellent partner for rebuilding your credit. If you are already a customer, it is often worth talking to a live representative about potential hardship programs or assistance.

A real-world conversation with a bank employee can sometimes bypass the rigid “no” of an automated algorithm. It is a place for long-term financial stability rather than quick, emergency fixes.

Pros:

  • Massive variety of banking products
  • Extremely well-established and trusted name
  • Wide array of wealth management services
Cons:
  • Rigid requirements for standard lending

5. NetCredit

NetCredit – netcredit.com

NetCredit operates under the philosophy that your identity is more than just a single number on a screen. They utilize sophisticated algorithms to look beyond a standard FICO score. This makes them a lifeline for those with less-than-perfect credit who still need meaningful funding.

By analyzing how you manage day-to-day expenses like rent or utilities, they can detect a level of reliability that traditional reports often overlook. This holistic view helps them offer loans up to $10,000 with incredibly fast turnaround times.

Their application is designed to be simple and efficient, which is perfect for managing urgent costs or rolling multiple high-interest debts into a single, more affordable monthly payment. It’s a strategic way to regain control of your finances.

Pros:

  • Underwriting through sophisticated algorithms
  • Possibility of same-day funding
  • Borrowing amounts up to $10,000
Cons:
  • Governed by specific partner bank regulations

6. OneMain Financial

OneMain Financial – onemainfinancial.com

If you find comfort in face-to-face interaction, OneMain Financial is an ideal choice. With a massive footprint of 1,300 branches, they offer a personal touch that digital-only lenders lack. They provide loans between $1,500 and $30,000, with rates starting at 11.99% APR.

One of their most impressive features is the speed of their disbursement. In some cases, you can see the funds in your account just an hour after the paperwork is finished. This is life-saving when you’re facing an emergency, such as a broken heating system.

The ability to sit down with a professional and explain your unique situation provides a level of psychological relief that a web form simply cannot provide. It is a human-centric approach to personal finance.

Pros:

  • Rapid funding, potentially within the hour
  • Large network of physical branch locations
  • Fixed, predictable monthly repayment amounts
Cons:
  • Requires an in-person or manual signing process

Decoding the Actual Expense of Your Loan

Before putting pen to paper, you really need to grasp how the Annual Percentage Rate (APR) differs from your scheduled monthly installment. While many eyes fixate solely on what leaves your bank account each month, the APR provides the full picture by incorporating both interest and compulsory service charges. It is the gold standard for evaluating a loan’s actual weight on your wallet.

In the middle of a financial storm, it is easy to let a small monthly bill blindside you. However, a low installment amount can act as a siren song if the repayment period stretches out indefinitely. You might think you are getting a break, but a long term can actually deepen your hole.

Imagine a scenario where you are paying $500 every month. On the surface, that seems like a walk in the park. Yet, if that commitment spans five years, you will end up returning a mountain of cash far exceeding the initial sum you received. It is a clever mirage of affordability that often pulls people into a cycle of endless debt.

As you weigh your various options, keep these three critical indicators at the forefront of your mind:

  • The Complete Loan Price: To find the true cost, take your monthly amount, multiply it by the total duration of the term, and then add any initial processing charges. This number tells you exactly what that borrowed capital costs you in the long run.
  • Early Repayment Charges: Should you land a new position and want to wipe out your debt early to dodge more interest, verify if the lender charges a penalty. Always hunt for a “no prepayment penalty” clause to keep your flexibility.
  • Processing or Origination Costs: Certain companies deduct fees from your capital before the funds ever hit your account. If you request $1,000 but only receive $950 in your hand, your effective interest rate is actually much steeper than the figure they initially advertised.

A Roadmap for Navigating Financial Hardship

Think of a temporary loan as a life jacket rather than a luxury cruise. While you’re between roles, this capital should only serve as a bridge to cover the bare necessities like groceries, your rent, electricity, and transit costs. It is vital not to spend this cash attempting to maintain a social facade or a standard of living your current situation simply cannot sustain.

The primary objective is to secure enough breathing room to hunt for your next career move without sinking into a whirlpool of predatory interest. If you treat this money as a permanent fix rather than a temporary patch, you might find yourself in a hole that is incredibly difficult to climb out of later.
During this transitional phase, you need a tactical approach to shield both your mental peace and your credit score. Staying proactive can prevent a temporary setback from turning into a permanent catastrophe. Consider these vital maneuvers to keep your head above water:

  1. Reach Out to Lenders Early: If a car payment or mortgage bill seems out of reach, don’t wait for a missed deadline to act. Call your bank immediately. Most institutions have specific programs for financial hardship or forbearance designed to help people in exactly your position.
  2. Rank Your Needs: When the wallet is light, prioritize survival. Your roof, your food, and your utility bills must come before the credit card companies. Keeping your basic needs met is far more urgent than maintaining a perfect credit score.
  3. Slash Unnecessary Costs: It might seem trivial, but pruning your digital life pays off. Cutting a gym membership or a streaming service might save $50 or $100 every month. When you are living on a skeleton budget, those small wins accumulate quickly.
  4. Maintain Detailed Records: Treat every loan application, email from a creditor, and specific term like a legal document. Store them in a dedicated folder. If a conflict arises down the road, having a complete paper trail will be your strongest ally.

Every single cent carries significant weight when you don’t have a steady paycheck. A single oversight can lead to an expensive mess. Before signing anything, look past the monthly installment amount and scrutinize the total cost of borrowing in the fine print. You must avoid being ensnared by skyrocketing interest rates while you are already struggling.

It is tempting to grab multiple small loans from various lenders to patch different holes, but this is a dangerous game. Such behavior often sparks a debt cycle that feels impossible to break. Instead, seek a single, cohesive solution that tackles your most pressing crisis with a repayment plan that aligns with your actual income.

If the walls feel like they are closing in, remember that high-interest debt isn’t your only option. Negotiating with your current creditors or seeking out local community assistance might offer more relief than a new loan ever could. Always balance the immediate relief of a loan against the long-term consequences for your future self.

Best Personal Loans for High Income Individuals: Compare Top Rates Today

By Uncategorized
Personal loans for high income individuals

Best Personal Loans for High Income Individuals: Compare Top Rates Today

Last updated: 2026-10-16

Securing immediate liquidity can feel like a uphill battle for those at the top of the food chain. Even with a towering income on your tax documents, many lenders struggle to wrap their heads around intricate cash flows or unique tax arrangements. It is a real headache.

It is not merely a quest for capital. Instead, you are searching for a collaborator who acknowledges your financial intelligence and values your precious time. You deserve a lender that treats your complex portfolio with the respect it warrants.

For elite professionals like specialized engineers, corporate leaders, or surgeons, rigid automated credit algorithms frequently miss the forest for the trees. These computer-driven models often overlook the true depth of your wealth. They are far too blunt an instrument for your situation.

Your actual net worth might be hidden within seasonal bonuses, stock options, or deferred compensation packages. These elements rarely translate well on a standard paycheck for a basic credit model. Consequently, you might face rejected applications or poor rates despite having substantial assets.

When selecting a provider, staring solely at the interest rate is a rookie mistake. You must weigh how fast the funds arrive against the fluidity of your repayment schedule. A clunky digital interface can also turn a smooth transaction into a nightmare.

If you are jumping on a private equity play or a real estate opportunity, you cannot afford to waste days uploading documents to a dinosaur bank. For high-asset individuals, excessive administrative friction is a total dealbreaker. Efficiency is your most valuable currency.

Our selection focuses on lenders that marry rapid capital deployment with an understanding of high-net-worth requirements. We have leaned heavily toward digital-first providers that won’t drag their feet. You need momentum, not a mountain of tedious paperwork.

We have curated a list of institutions that keep pace with your lifestyle. These are the companies designed to move as fast as you do.

  1. Discover
  2. Avant
  3. JetzLoan
  4. OneMain Financial
  5. LendingPoint
  6. Upgrade

Our Methodology for Rating Lenders

We tailored our assessment to meet the unique demands of individuals with substantial earnings. The primary goal was to find institutions capable of issuing substantial sums of money without demanding physical assets as security. Many executives prefer leveraging their projected income or existing wealth rather than tying up collateral.

Because of this, we hunted for companies that employ “soft pulls” during the preliminary screening phase. This specific feature is a breath of fresh air for anyone worried about their credit standing. It permits a quick glance at potential terms without causing any damage to your financial history.

Testing the speed at which money actually hits your bank account was also vital. In the high-stakes world of investing, timing is everything. A missed window on a real estate deal can be a costly mistake for even the most seasoned professional.

Consequently, we gave top marks to firms that provide lightning-fast capital deployment. We prioritized those offering funds within twenty-four hours, and even those that could deliver in just one hour. Speed is often the deciding factor when a sudden opportunity knocks on your door.

We also peeked under the hood of their digital application platforms to check for transparency. A lender that buries “origination fees” in the fine print of a massive document is a major red flag. People with busy schedules need clarity, not a scavenger hunt for hidden costs.

Finally, the sheer scalability of each loan product was a deciding factor in our review. Offering a measly $5,000 might help with a small fix, but it does nothing for someone aiming to consolidate major debt or fund a massive lifestyle change.

We steered clear of small-scale lenders in favor of those with significant ceilings. We looked for providers that routinely offer $30,000 or much more. Such high limits ensure the liquidity actually serves a purpose in complex, high-net-worth strategic financial planning.

Comparing Leading Borrowing Options

Selecting the right lender often feels like navigating a maze without a compass. You might find yourself weighing various pros and cons while trying to secure the best possible terms for your financial goals. It is not just about the money; it is about the speed and the fine print that governs your debt.

Some companies promise to deliver funds before the sun sets on your application, while others require a bit more patience. High earners typically prioritize efficiency, wanting to see that capital hit their accounts without any unnecessary delays or bureaucratic red tape getting in the way.

Before you sign any contracts, it is vital to look at how these institutions handle your credit history. A soft inquiry is a breeze, but a hard inquiry can feel like a punch to the gut if you are not prepared. Knowing which companies offer a “no impact” pre-qualification is a real game-changer.

Financial Institution Maximum Borrowing Limit Time to Receive Funds APR and Interest Details Credit Score Effect
Discover $40,000 By the following business day 6.99% – 24.99% Pre-approval does not affect score
Avant Consult website Consult website Consult website Consult website
JetzLoan $50,000 A minimum of 24 hours Consult website No hard credit pull
OneMain Financial $30,000 Within a single hour From 11.99% APR Checking results in no impact
LendingPoint $36,500 Consult website Consult website Checking results in no impact
Upgrade $50,000 Rapid disbursement Consult website Checking results in no impact

Top-Tier Lending Options for High-Income Earners

1. Discover

Discover – discover.com

For those who find comfort in institutional giants, Discover is a rock-solid contender. Their personal loans offer a range of $2,500 to $40,000, providing a dependable bridge for your financial needs. There is a certain peace of mind that comes with knowing a massive, established entity is managing your debt.

If you are weary of trendy fintech startups that might vanish overnight, this brand offers the permanence of a legacy institution. It’s like having an old, reliable lighthouse in a sea of unpredictable digital players. Their structure provides a sense of security that many modern apps simply cannot replicate.

The digital experience is remarkably smooth, designed specifically for the person whose time is worth more than gold. You can perform a soft check for pre-approval to see your potential terms without bruising your credit score. It’s a low-stakes way to scout your options without any heavy lifting.

The interface is stripped of all the clutter, ensuring you don’t get lost in a maze of sub-menus. For a busy executive, this streamlined workflow is a luxury in itself. It gets the job done quickly so you can get back to your high-level priorities.

Pros:

  • You could have your funds as early as the very next business day.
  • They offer flexible timeframes and a zero-fee structure.
  • Checking your pre-approval status leaves your credit score untouched.

Cons:

  • Your borrowing limit is capped at a maximum of $40,000.

2. Avant

Avant – avant.com

Avant caters to individuals who are constantly in motion, moving their finances toward new horizons. They provide a versatile toolkit of products, from specialized credit cards to loans intended for home upgrades or debt consolidation. This makes them a great fit for those whose financial profile is ever-evolving.

Consider a professional climbing the corporate ladder; your debt-to-income ratio might shift as you move from an associate to a partner. Avant understands these transitions. They offer a menu of solutions rather than a rigid, “one-size-fits-all” template that might leave you feeling boxed in.

The company prioritizes a user-centric approach, pairing digital ease with helpful support. Whether you need a quick fix for a sudden expense or a long-term plan to reorganize your liabilities, their tools help simplify the path. It’s about finding the right gear for your specific financial velocity.

Pros:

  • Customizable loan options designed for various life situations.
  • Digital tools that make financial oversight a breeze.
  • Offers diverse strategies for managing existing debt.

Cons:

  • Details regarding specific limits and terms are not always transparent.

3. JetzLoan

JetzLoan – jetzloan.com

When time is the most expensive commodity, JetzLoan enters the ring as a high-speed contender. They act as a conduit, connecting you with premier lenders in mere minutes. You could potentially see funds land in your account in as little as twenty-four hours.

Traditional banking can often feel like wading through molasses when you are in a hurry. If a time-sensitive investment presents itself—like a high-stakes real estate auction—the velocity provided here becomes a massive competitive advantage. It’s built for the professional who needs capital yesterday.

Completing the initial application takes less than a two-minute sprint through a simple form. With a ceiling of $50,000, they handle significant needs without requiring a hard credit pull just to see your rates. It’s a clever way to survey the landscape without the usual administrative headache.

By utilizing this marketplace model, you can view a wide array of opportunities in one sitting. This saves you from the tedious chore of applying to multiple banks one by one. It’s a massive time-saver for the high-earning professional.

Pros:

  • Lightning-fast funding, potentially arriving within a single day.
  • Initial rate comparisons won’t harm your credit score.
  • A substantial maximum borrowing limit of $50,000.

Cons:

  • The service functions as a bridge to lenders rather than being the lender itself.

4. OneMain Financial

OneMain Financial – onemainfinancial.com

OneMain Financial serves those who want the best of both worlds: digital speed and human connection. Their personal loans range from $1,500 up to $30,000, with APRs starting at 11.99%. For urgent liquidity, the ability to receive money just one hour after signing is a game-changer.

In a market where unsecured loans are often slow, this level of urgency is a rarity. It makes them a premier choice for those facing unexpected emergencies. You get the efficiency of a modern app without losing the safety net of a physical presence.

With 1,300 branches available, you can always sit down with a real person if you prefer. This hybrid approach is perfect for high earners who want the convenience of a phone but the security of a face-to-face meeting. Sometimes, you just want to look someone in the eye when discussing complex money matters.

Having a physical office to visit can provide immense peace of mind. It is especially helpful if you need to iron out complicated repayment structures. A digital-only lender might reject a nuance that a human expert can navigate easily.

Pros:

  • Rapid disbursement, sometimes in just sixty minutes.
  • A massive network of branches for in-person assistance.
  • Repayment windows ranging from 24 to 60 months.

Cons:

  • Unsecured loan rates may exceed those of secured lending products.

5. LendingPoint

LendingPoint – lendingpoint.com

LendingPoint positions itself as a versatile tool for life’s various milestones, whether that is a wedding or medical bills. Their loan amounts fall between $1,000 and $36,500, hitting a sweet spot for those who need more than a tiny micro-loan. They provide a robust middle ground for significant expenses.

Their underwriting logic is built to be more sophisticated than your standard consumer lender. Instead of just glancing at a single number, they tend to view your broader financial health. It’s a more holistic way of looking at a professional’s creditworthiness.

The platform makes the “shopping around” process painless. You can check your specific rates without any impact on your credit score, which is a vital feature. This allows you to compare various offers with total freedom, ensuring you don’t pay more than necessary for your debt.

For high-earners managing multiple lines of credit, this “window shopping” capability is essential. You need to be surgical about which debt you take on and exactly what the cost will be. Precision in these matters can save a fortune over time.

Pros:

  • Supports a diverse array of loan purposes.
  • Rate checking is available without credit score penalties.
  • Offers significant loan amounts up to $36,500.

Cons:

  • The borrowing ceiling is lower than some specialized lenders.

6. Upgrade

Upgrade – upgrade.com

Upgrade acts as a comprehensive digital toolkit for the modern, high-earning consumer. They offer personal loans that reach up to $50,000, prioritizing speed and high-tech integration. You can often see your potential rates in just a few minutes.

It is a fantastic option for those who desire to manage their loans, checking, and savings in one unified ecosystem. Their approach focuses on reducing the “friction of friction,” effectively cutting out the unnecessary steps between your application and the actual disbursement of cash.

Their ecosystem is impressively robust, featuring cash back on various transactions and high APY on savings accounts. It is a “one-stop-shop” designed to appeal to those who crave efficiency. By centralizing your finances, you gain a clearer, real-time view of your total liquidity.

This bird’s-eye view of your cash flow is a vital component of sophisticated financial management. Instead of juggling five different apps, you have everything in one place. It turns a chaotic financial life into a streamlined, digital machine.

Pros:

  • High borrowing limit of up to $50,000.
  • A seamless ecosystem linking savings and checking.
  • Quick rate checks that won’t touch your credit score.

Cons:

  • The breadth of the ecosystem might feel complex to some users.

Leveraging Credit as a Wealth Management Catalyst

For individuals sitting in the upper echelons of earnings, a personal loan shouldn’t simply be categorized as a burden of debt. Instead, think of it as a sophisticated lever for moving capital around your portfolio. When you use these funds with precision, they act as a bridge toward lucrative ventures that might otherwise pass you by.

It is all about timing and the art of deployment. Rather than waiting for liquid cash to become available, a well-timed loan allows you to strike when the iron is hot. Consider these specific ways to put that capital to work effectively:

  • Capturing Arbitrage Spreads: Imagine a distressed real estate deal or a private equity play lands on your desk overnight. You might not want to wait for a bonus or a property sale to finalize. A loan provides the instant liquidity needed to lock in that deal, ensuring the potential profit far outweighs the interest cost.

  • Refining Cash Flow and Tax Timing: While you won’t get the same tax breaks on personal loan interest as you would with a mortgage, they remain powerful tools for managing liquidity. You might choose to finance a large purchase now to keep your own cash tucked away in high-yield vehicles, effectively deferring the use of your own capital.

  • Streamlining Existing Liabilities: Many high-net-worth individuals find themselves juggling several lines of credit and premium credit cards. By rolling these various debts into one low-interest personal loan, you simplify your monthly obligations. This consolidation reduces the sheer amount of interest bleeding out of your accounts over the long haul.

Steering Clear of Common Lending Traps

Even if you are pulling in a massive salary, it is remarkably easy to slip up and watch your net worth slowly bleed away. One frequent blunder involves obsessing over a small monthly bill while ignoring the actual price tag of the debt. When you are securing a $50,000 loan, a mere 2% discrepancy in interest can swallow thousands of dollars that should have stayed in your portfolio.

You must always scrutinize the APR instead of just looking at the monthly installment to grasp the real weight of your debt. This number is the ultimate truth-teller because it merges the interest rate with any compulsory fees. It paints the most honest portrait of what your borrowing will actually cost you in the long run.

Another blunder involves ignoring how fast the cash hits your account versus how much you actually need it right away. If a golden opportunity lands on your desk, a slightly higher interest rate might be a small price to pay for instant liquidity. Sometimes, speed is the secret sauce that turns a good deal into a great one.

Consider a scenario where a business venture demands a 24-hour turnaround to succeed. In that moment, a 12% loan that arrives in an hour is infinitely more precious than a 7% loan that sits in processing for ten days. On the other hand, if your goal is long-term debt consolidation, you should hunt down the lowest APR possible regardless of the wait.

Finally, you must read the fine print regarding prepayment penalties with a hawk’s eye. High earners often find themselves sitting on extra cash and may want to kill off a loan early to stop interest from accruing. If your lender hits you with a fee for early repayment, that “bargain” loan might end up being a total money pit.

Before you put pen to paper, don’t be afraid to ask the hard questions. Specifically, ask: “Is there a penalty for paying this loan off in full within the first twelve months?” For someone with fluctuating cash inflows, having that kind of freedom is a non-negotiable requirement for any smart lending partner.

Get Best Rates on Personal Loans for Credit Score Under 600 Now

By Uncategorized
Personal loans for credit score under 600

Get Best Rates on Personal Loans for Credit Score Under 600 Now

Last updated: 2026-10-16

Navigating your finances when your FICO score slips under the 600 mark can feel like wandering through a dense, blinding mist. Most conventional banking institutions typically bolt their doors against you. This leaves anyone hunting for immediate liquidity desperately searching for a lifeline.

Life has a way of throwing curveballs when you least expect them. An abrupt mechanical failure in your vehicle, a surprising hospital invoice, or a sudden period of unemployment can trigger a financial storm. It is an incredibly high-pressure situation for anyone to endure.

In these tight spots, the standard financing packages from giants like Wells Fargo or Chase often seem like a distant dream. Their algorithmic decision-makers are designed to chase elite credit ratings and long-term histories. They often fail to see the human being behind the data point.

Selecting the ideal provider involves a much deeper dive than merely scanning interest percentages. You need to balance the velocity of funding, total amounts, and how a company values your recent paychecks over historical slip-ups. For example, a firm might ignore a past bankruptcy if your current job provides steady, provable wages.

Our current list identifies the most practical pathways for individuals attempting to mend their financial standing. We have scrutinized various companies to determine who actually steps up during a crisis. These are the leading options for 2026.

  1. FastLendGo
  2. Avant
  3. Prosper
  4. Max Cash
  5. Upgrade
  6. LendingPoint

Evaluating Lenders for Credit Scores Under 600

When searching for lenders in this bracket, the primary focus shifts toward accessibility for those with less-than-perfect credit histories. We analyzed the speed at which funds arrive and the minimum amounts available for borrowing. For many, the clock is the biggest enemy during a financial crisis. If a utility company threatens to cut off your power, waiting a week or more for a bank’s decision is simply not an option.

You generally want a company that utilizes rapid, digital-first underwriting to get you answers fast. During our research, we looked closely at the specific niches these providers fill. Some businesses are built for small, urgent cash injections, whereas others are geared toward larger projects like debt consolidation. Knowing if a company values a high salary or just a consistent work history can change your entire strategy.

Consider how different requirements can impact your chances of success. One lender might demand that you earn at least $2,500 every month to qualify. On the other hand, another provider might be perfectly happy with any steady income, provided you can prove it through bank statements instead of traditional paychecks. This small detail is a lifeline when you are racing against a looming deadline.

Company Borrowing Limits Credit Standards Speed of Funds
FastLendGo $500 – $5,000+ Fair/Bad Credit Quick Access
Avant Check website Near 580 Check website
Prosper $2,000 – $50,000 Check website Check website
Max Cash $250 – $10,000+ Bad Credit Within Minutes
Upgrade Up to $50,000 Check website Check website
LendingPoint $1,000 – $36,500 Check website Check website

1. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo acts as a versatile safety net for people navigating life’s sudden financial potholes. Their offerings span from modest $500 loans to larger amounts exceeding $5,000. This variety is a total lifesaver if you are stuck with an unexpected dental bill or a sudden car repair. Their process is built for speed, focusing on why you need the money rather than digging through years of credit data. (fastlendgo.com)

This is a great landing spot for those with fair or bad credit who feel ignored by the big banks. They even branch out into specific areas like roof financing or motorcycle loans. If you are tired of scrolling through endless search results, this platform helps streamline the hunt. They often provide specialized products, such as using your property as collateral, which standard lenders usually won’t even consider.

Pros:

  • A diverse range of uses, from car fixes to emergencies.
  • Small-scale borrowing starts at just $500.
  • Tailored specifically for those with poor or fair credit.

Cons:

  • Detailed information on specific interest rates is hard to find.

2. Avant

Avant – avant.com

Avant approaches lending with a goal of helping people move past financial setbacks. They offer a mix of personal loans and credit cards intended for managing debt or handling surprises. Their digital system is designed to make things easy, allowing you to handle all the paperwork from your phone without ever stepping into a branch.

If your score is hovering near 580, this could be a meaningful option. Rather than being a slave to a single number, they look at the bigger picture. Their installment loans are designed to fit into your existing monthly budget. They aim to see the “whole person,” which means they might weigh your current income against your debt more heavily than a single mistake from years ago.

Pros:

  • Provides both credit cards and loan options.
  • Excellent for consolidating debt or home projects.
  • Very intuitive digital tools for managing money.

Cons:

  • Applicants with extremely low scores may still face denials.

3. Prosper

Prosper – prosper.com

Prosper is a major player in the peer-to-peer (P2P) market, offering a unique twist on traditional borrowing. You aren’t actually borrowing from a bank here; you are connecting with individuals looking to earn interest on their savings. This can lead to more flexibility for people with non-traditional financial backgrounds, as individual investors are often willing to accept higher risks for better returns.

The loan amounts available are substantial, ranging from $2,000 to as high as $50,000. This makes them a powerhouse for massive life events, such as weddings or major debt restructuring. Because the capital comes from various private investors, the approval process can feel a bit different than a bank. Their reputation remains strong due to high user ratings and a transparent marketplace model.

Pros:

  • Massive borrowing capacity of up to $50,000.
  • A peer-to-peer structure that offers diverse opportunities.
  • High user satisfaction according to third-party reviews.

Cons:

  • The P2P nature means approval times can vary.

4. Max Cash

Max Cash – maxcash.com

When you are staring down a ticking clock and an unpaid bill, Max Cash is ready to step up. They focus heavily on speed, providing title loans and installment loans in mere minutes. This is perfect for those true emergencies, like a sudden transmission failure that threatens your ability to get to your job or an urgent medical deposit.

Their loan amounts are segmented very finely, starting as low as $250. This is ideal for those who want to avoid over-borrowing. If you only need $300 for a quick bill, you shouldn’t have to take on $5,000 in debt. Max Cash offers precision borrowing, acting as a relief valve for people who need immediate liquidity without the mountain of paperwork found at big banks.

Pros:

  • Lightning-fast processing for urgent situations.
  • Very accessible entry point with $250 loans.
  • Offers varied products, including title loans.

Cons:

  • Rapid, small-dollar loans often come with very high interest.
5. Upgrade

Upgrade – upgrade.com

Upgrade functions as much more than a simple lender; they are an expansive financial services hub. Their catalog includes personal loans, credit cards, and even checking accounts. This makes them a convenient “all-in-one” destination for anyone wanting to consolidate their various financial life into one easy-to-manage ecosystem.

With limits reaching up to $50,000, they are well-suited for significant milestones like starting a business. Their business model focuses on helping users earn rewards and manage cash flow more effectively. They typically use a mix of income verification and credit scores to decide eligibility, which can be a massive win for high earners with lower credit scores.

Pros:

  • A full suite of tools, including checking accounts.
  • High borrowing ceilings up to $50,000.
  • Potential for cash back through specific products.

Cons:

  • May require a more stable income than specialized lenders.

6. LendingPoint

LendingPoint – lendingpoint.com

LendingPoint aims to help users open new doors through customized personal loans. Their amounts, from $1,000 to $36,500, place them right in that sweet spot between tiny cash advances and massive bank loans. They are looking for people who are trying to bridge the gap between being considered “unbankable” and reaching prime credit status.

The application is built for efficiency, allowing you to check your rates without hurting your credit score. For someone with a score under 600, every single point matters. This “soft pull” feature is a game-changer, letting you shop for the best terms with zero risk of a hard inquiry damaging your score further.

Pros:

  • Check your rates without any credit score impact.
  • Substantial loan limits up to $36,500.
  • Clear options for travel or medical expenses.

Cons:

  • They do not explicitly market themselves as “low credit” friendly.

The Real Price of Loans for Lower Credit Scores

Stepping into the world of lending with a score under 600 feels a bit like sailing into a storm without a compass. You aren’t merely paying back the principal sum you requested; you are essentially paying a premium for the gamble the bank is taking on your reliability. It’s vital to grasp what the Annual Percentage Rate (APR) actually signifies in your daily life.

Think of it this way. A traditional bank might hand you a loan with an APR between 8% and 12% without breaking a sweat. However, for those with sub-600 ratings, interest rates often skyrocket, frequently landing between 25% and 36%, or even higher for quick, short-term financing options. These steep jumps are the difference between a light, manageable monthly bill and a suffocating cycle of debt that feels impossible to outrun.

Let’s crunch some numbers to see how this plays out in the real world. Imagine you borrow $5,000 at a 10% interest rate over a 3-year term. Now, compare that to a $5,000 loan with a 30% interest rate over that same 3-year period. In that second, much more expensive scenario, you might find yourself shelling out nearly $8,000 just to satisfy the original $5,000 debt.

Before you ink your signature on any contract, demand a “Truth in Lending” disclosure. This isn’t just paperwork; it’s a legal requirement that forces lenders to reveal the total dollar amount of interest you will accumulate throughout the entire lifespan of the loan. If that final number makes your heart sink, it is much wiser to request a smaller loan amount or simply walk away and search for another lender.

How to Boost Your Likelihood of Getting Granted

Think of your credit score as your financial reputation, which doesn’t shift overnight. However, you can certainly polish how you appear to the banks. When your score sits around 550, banks aren’t just looking at that number; they are hunting for signs of a steady lifestyle.

If you can hand over pay stubs proving you’ve held the same job for half a year, you’re in a much better light. This evidence of steady work acts as a shield against the perception of risk. To a lender, a reliable income often outweighs a mediocre score.

They want to know you won’t vanish when the bill comes due. Demonstrating consistent earnings provides the reassurance they crave. It is the secret sauce to turning a “maybe” into a “yes” when your numbers aren’t perfect.

Treat your search like a reconnaissance mission by utilizing pre-qualification tools. I have seen people make the massive mistake of jumping straight into a formal application without testing the waters first. That’s a recipe for a bruised score.

Once you officially hit “submit” on a real application, a hard inquiry hits your report. This can shave points off your score instantly. Instead, you want to hunt for “soft inquiries.” These are the low-stakes checks that let you shop around without any penalty.

Use these soft checks to compare different options and rates. It’s like window shopping for the best deals. Only commit to a formal request once you have found a lender that truly fits your specific budget and financial goals.

Don’t get blinded by shiny advertisements for tiny monthly payments. Always dig into the fine print before signing anything. A low monthly bill often hides a trap: a massive term that stretches the debt for years.

If the repayment period is too long, you might end up paying back twice or even triple your original loan amount. It is a heavy price for a small monthly comfort. Always aim for the quickest timeline your budget allows to keep interest costs low.

If you have a little extra cash, throw an extra $50 toward your principal every month. It might seem like a drop in the bucket, but it works like magic. This simple habit slashes your total interest and helps you escape the debt cycle much faster.

Top Rated 620 Credit Score Personal Loan Options for Immediate Cash

By Uncategorized
620 credit score personal loan

Top Rated 620 Credit Score Personal Loan Options for Immediate Cash

Last updated: 2026-10-16

Navigating your finances with a 620 credit score can feel like walking a tightrope in a windstorm. Even if you are diligent with your monthly payments, major financial institutions often turn up their noses at a “fair” rating. It is a taxing situation that leaves many people feeling completely sidelined by the traditional banking system.

You frequently find yourself stuck in a no-man’s land. On one side, you have predatory lenders looking to sink you with massive interest; on the other, rigid lenders demand perfection. This middle ground is a tricky place where many borrowers lose their footing before they even begin their journey.

When you are searching for a way out, don’t just grab the first hand that reaches out to you. It is vital to find a partner that provides a genuine path toward stability rather than a debt trap. You need clarity and speed, not hidden fees that pop up like weeds in a garden.

Our research into the 2026 market focuses on finding the most reliable options for those hovering around the 620 mark. We prioritized evaluating how quickly these companies process applications and how honest they are about their terms. We want to ensure you see the full picture before signing anything.

  1. JetzLoan
  2. Max Cash
  3. Avant
  4. Upgrade
  5. LendingPoint
  6. United Finance
  7. Prosper

Scouting the Best Lending Choices for Fair Credit

Finding the right money partner when your credit is hovering in the “fair” zone requires a keen eye. We dissected several key metrics to determine which companies truly serve this specific demographic. Our main focus was the turnaround time from the first click to the moment funds hit your bank account.

When a car breaks down or a medical bill arrives, you need cash yesterday. Waiting through a week of tedious paperwork is simply not an option for most people facing real-world crises. Consequently, we weighed the velocity of the funding process quite heavily.

Protecting your reputation with credit bureaus is just as vital as getting the cash. A 620 score is like walking a tightrope; one wrong move and you could slip into a lower tier. We hunted for lenders that utilize “soft” inquiries during the shopping phase.

This approach allows you to browse various offers without the fear of a sudden dip in your rating. Every hard inquiry counts, and when you are on the fence, every single point matters. You need the freedom to compare without being penalized for being cautious.

The logic behind our selection process is straightforward. If a provider forces a hard inquiry before giving you a price, they aren’t a friend to the cautious borrower. You deserve a window to view costs without any immediate damage to your financial standing.

Financial Provider Borrowing Limits Payout Timeline Score Sensitivity
JetzLoan $500 – $35,000 24-hour minimum Soft pull only
Max Cash $250 – $10,000+ Immediate No charge to check
Avant Check website Check website Check website
Upgrade Max $50,000 Rapid transfer No rating change
LendingPoint $1,000 – $36,500 Check website Zero credit damage
United Finance Max $20,000 Fast decision Check website
Prosper $2,000 – $50,000 Check website Does not affect score

Leading Loan Providers Compared

1. JetzLoan

JetzLoan – jetzloan.com

Life doesn’t wait, and neither should you. When you are facing an immediate financial crunch, JetzLoan acts as a digital bridge between you and various premier lenders. Instead of spending your afternoon hunting through dozens of websites, they do the heavy lifting for you.

This platform is tailor-made for the modern, fast-moving lifestyle. Whether you are staring down a sudden car repair or trying to tidy up your debt through consolidation, speed is their specialty. You could see the funds in your bank account in a mere 24-hour window.

Getting started is a breeze; the application takes roughly two minutes to complete. Just remember that JetzLoan doesn’t lend its own money. They serve as a helpful intermediary to find the most suitable match from their extensive partner network.

Pros:
  • Get your funds in as little as 24 hours.
  • Check your rates without a hard credit inquiry.
  • Access high borrowing limits up to $35,000.
Cons:
  • Functions as a middleman rather than a direct source.

2. Max Cash

Max Cash – maxcash.com

Max Cash is like a Swiss Army knife for your finances. Their lineup of products is incredibly diverse, catering to almost any situation. You might need a tiny cash advance to bridge a gap or a much larger installment loan to handle a major expense.

The flexibility here is quite remarkable. They accommodate everything from small $250 micro-loans to much larger sums exceeding $10,000. Because they offer zero-obligation inquiries, you can shop around for the best deal without seeing a dip in your credit score.

It is an excellent safety net when you find yourself in a tight spot. However, with so many different avenues to explore, the sheer variety can occasionally feel a bit dizzying for a first-time visitor.

Pros:
  • Very accessible with starting amounts of $250.
  • Rapid processing, frequently finishing in just minutes.
  • Huge variety, including title loans and cash advances.
Cons:
  • The wide array of products can feel complicated.

3. Avant

Avant – avant.com

Avant is all about helping you take the next step toward financial stability. They specialize in structured installment loans, specifically designed for those who might find traditional bank requirements a bit too rigid. Their focus is on helping you reach life’s milestones.

If your credit score sits between 580 and 700, you might find Avant to be a perfect fit. Rather than just providing a quick cash injection, they aim to offer a sense of long-term direction for your money. It is a holistic approach to borrowing.

Don’t expect the same “anything goes” atmosphere you might find with some niche lenders. They have specific standards to maintain, so their requirements might feel slightly more stringent than those of high-risk specialists.

Pros:
  • Targeted loans for home improvement and debt consolidation.
  • Ideal for borrowers with scores between 580 and 700.
  • Designed to foster long-term financial growth.
Cons:
  • Criteria may be more rigorous than some niche lenders.

4. Upgrade

Upgrade – upgrade.com

Upgrade is a heavyweight in the digital finance arena. They provide a comprehensive ecosystem that includes everything from standard personal loans and credit cards to dedicated savings accounts. They are famous for their speed and their ability to offer fixed rates.

For those looking to borrow a substantial amount, they provide a direct route to funds up to $50,000. You can see your personalized rate in just a few minutes without any impact on your credit score. They even reward checking customers with cash back on certain debit transactions.

With so many moving parts in their system, it is easy to get lost in the weeds. You might need to slow down and carefully evaluate which specific product aligns best with your current financial goals.

Pros:
  • Borrowing ceilings reach up to $50,000.
  • Predictable monthly payments with fixed interest rates.
  • Lightning-fast rate checks and fund transfers.
Cons:
  • The abundance of options can lead to confusion.

5. LendingPoint

LendingPoint – lendingpoint.com

LendingPoint aims to strip away the complexity of the borrowing process. Their application is designed to be straightforward, making it easy to tackle urgent costs like medical emergencies, weddings, or much-needed travel. Their loan amounts range from $1,000 all the way up to $36,500.

Transparency is a cornerstone of their business model. You can shop for the best rates without any fear of hurting your credit, which is vital for someone with a 620 score. It removes a significant layer of stress from the process.

Be prepared to dive into the details, though. Unlike some of the “quick and dirty” lenders, you may need to provide more extensive documentation to complete your application successfully.

Pros:
  • Funding amounts are ideal for major life events.
  • Safe rate comparisons via soft credit checks.
  • Clear categorization for various borrowing needs.
Cons:
  • Documentation requirements can be quite thorough.

6. United Finance

United Finance – unitedfinance.com

United Finance brings a wealth of history to the table, having been active since 1922. This longevity offers a sense of rock-solid stability that many modern fintech startups simply cannot replicate. They provide a more classic, personalized touch to lending.

They focus on providing auto and personal loans that align with your specific budget. For those working to repair their credit, their installment loans offer a strategic way to manage and rebuild debt. It is a very human way to bank.

You won’t find the dizzying, instant speed of a brand-new app here. Instead, you get a trade-off: a slightly slower process in exchange for the peace of mind that comes from decades of industry experience.

Pros:
  • Backed by decades of market experience.
  • Provides both personal and automotive loan options.
  • Focuses on creating a sustainable household budget.
Cons:
  • Lacks the instant speed of newer tech-driven apps.

7. Prosper

Prosper – prosper.com

Prosper is a major player in the peer-to-peer lending landscape. They have built a massive reputation for offering competitive interest rates and a strong presence in the market. Their loans range from $2,000 to $50,000, usually featuring flexible terms.

If you want to see your potential rates instantly and without a credit hit, this is a strong contender. Their tech-forward platform is built for maximum efficiency, helping you find money exactly when you need it most.

Because this is a peer-to-peer system, the way they evaluate your application might feel a bit different than a traditional bank. There are unique nuances to their approval process that you should keep in mind.

Pros:
  • High loan caps of up to $50,000.
  • Flexible repayment options, including 6-year terms.
  • A smooth and modern digital interface.
Cons:
  • The P2P model involves unique approval variables.

Hunting for the Ideal Credit Match

Selecting a provider is a delicate tightrope walk. You are essentially juggling your urgent cash requirements against your future fiscal stability. If a sudden crisis strikes, you might prioritize lightning-fast approvals above all else.

However, if your goal is merging various debts, you must scrutinize the overall expense. Digging into the APR is vital. You cannot afford to ignore the fine print when trying to simplify your finances.

Many borrowers stumble by focusing solely on what they owe each month. It is a deceptive carrot on a stick. A small monthly installment often hides a much longer repayment period lurking beneath the surface.

This extended timeline can drain your wallet, forcing you to pay a premium in interest. Before you put pen to paper, demand the total sum you will eventually repay. Knowledge is your best defense against hidden costs.
Another common pitfall involves peppering various lenders with full applications. This is a recipe for disaster for your score. While browsing rates is harmless, a formal application initiates a “hard” inquiry on your report.

Think of it like shopping for a car. You wouldn’t walk onto a lot and sign a contract immediately. Instead, use “soft pull” tools to compare deals first. Only commit once the stars align and the math makes sense.

Get a 500 Credit Score Personal Loan From These Fast Online Lenders

By Uncategorized
500 credit score personal loan

Get a 500 Credit Score Personal Loan From These Fast Online Lenders

Last updated: 2026-10-16

Navigating a financial drought with a 500 credit score can feel like wandering through a dense mist without a map. You might feel like the walls are closing in. Many folks mistakenly believe a low rating acts as a permanent barrier to entry.

In reality, it is often just a temporary roadblock on your journey. The real secret to finding breathing room lies in locating a lender that sees the human behind the digits. They need to look beyond that solitary, underwhelming number.

Generally, a score around 500 lands you in the “very poor” bracket. If you approach big banks or premium credit card companies, expect a quick “no.” They aren’t built for these types of risks. It’s a tough pill to swallow.

However, the credit landscape isn’t entirely closed to you. You just need to pivot your approach. Instead of knocking on the doors of mainstream institutions, start scouting for specialty lenders who specialize in these unique situations.

When you hunt for a loan, remember that getting the money is only half the battle. You have to ensure the terms don’t become a millstone around your neck. A bad deal can quickly turn a minor setback into a catastrophe.

Consider the math: a $5,000 loan at 36% APR is a much heavier burden than one at 25% APR over 36 months. That extra interest adds up fast. You could end up throwing thousands of dollars down the drain instead of building savings.

We have curated this list to highlight lenders that value speed and accessibility. These are the companies helping people patch up their finances. They focus on those who are actively trying to mend their credit standing.

  1. Avant
  2. OneMain Financial
  3. FastLendGo
  4. Reprise
  5. United Finance
  6. OppLoans

Our Method for Ranking Providers

When we set out to find the best options for those with a 500 credit score, our primary compass was accessibility. Traditional banks often slam the door on anyone in the “poor” credit bracket. Consequently, we spent our time hunting for lenders that specialize in helping people with less-than-ideal credit histories.

We placed a huge premium on companies that don’t treat your FICO score like a fragile glass vase. Specifically, we looked for lenders that permit you to start the application process without an immediate penalty to your credit standing. It is all about keeping your options open without causing extra damage.

A “soft pull” is a lifesaver in these scenarios because it lets you peek at interest rates and loan terms without a “hard pull” scarring your report. When your financial health is already on shaky ground, you need to scout the field carefully. This allows you to shop around without making your situation even more precarious.

Speed and honesty were the other two pillars holding up our selection process. Life doesn’t wait for a perfect credit score to throw a curveball. Whether it is a sudden trip to the mechanic, a surprising medical invoice, or a looming utility bill, people often need cash in a heartbeat.

Because of this, we gave the spotlight to lenders capable of making lightning-fast decisions or offering same-day transfers. However, we didn’t just reward speed; we also ensured their repayment structures remained fair and manageable. We weren’t interested in predatory traps that offer quick cash but demand a mountain of interest in return.

We relied heavily on the “time-to-cash” metric to separate the wheat from the chaff. This specific measurement tracks the clock from the second you click “submit” on your digital application until the actual dollars land in your personal checking account. If they were too slow, they didn’t make our cut.

The Reality of Borrowing with Limited Credit

Before you sign on the dotted line with anyone on this list, you must face the cold, hard math of high-interest debt. When your score hovers around 500, you are essentially a gamble in the eyes of a bank. They see a high-risk profile, so they demand a higher premium to cover their potential losses.

This premium manifests as a higher Annual Percentage Rate, or APR. It is a common mistake to look only at the interest rate and think you have the full story. In reality, the APR is the true north for your finances because it bundles the base rate with those pesky origination fees and lender costs.

Think of the APR as the “all-in” price of your debt. If you only focus on the interest rate, you might find yourself blindsided by extra charges when the final bill arrives. Being savvy means looking at the total cost of borrowing before you commit your hard-earned cash to a new loan.

Take a look at how these different borrowing scenarios play out for someone sitting at a 500 credit score:

Principal Borrowed APR (Annual Rate) Repayment Period Monthly Installment Cumulative Interest
– $3,000 15% (Good Credit) 24 Months $145.46 $491.04
– $3,000 30% (Fair Credit) 24 Months $171.18 $1,108.32
– $3,000 45% (Poor Credit) 24 Months $199.63 $1,791.12

The numbers tell a staggering story. When the interest rate simply doubles, the total amount you pay in interest can end up more than tripling the original cost. It is a steep mountain to climb, and the weight of that interest can feel like an anchor around your ankles if you aren’t careful.

This is why your choice of lender matters more than almost anything else. You shouldn’t just be looking for someone to hand you cash; you need a partner. Look for a lender that offers a path to repairing your credit score rather than one that just treats you like a walking ATM.

Ultimately, your goal should be long-term stability, not just immediate relief. Choosing a lender that prioritizes your financial health over predatory interest rates is the single most vital decision you will make during this journey.

Top Borrowing Alternatives Evaluated

Navigating the sea of lending options can feel like trying to find a needle in a haystack when your score is hovering around the 500 mark. It is easy to feel overwhelmed by the sheer volume of companies promising quick cash under the table. However, not every lender is cut from the same cloth when it comes to risk tolerance.

I remember a friend of mine who was stuck in a financial pinch, staring at a daunting pile of bills. He thought his credit history had essentially closed all the doors in his face. It turns out, some providers actually specialize in helping people in his exact predicament. You just have to know where to look.

Finding the right fit is about more than just looking at the interest rate. You have to weigh how fast they can get money into your pocket and what they demand from your credit report. Some companies are lightning-fast, while others take a bit more time to process your application and verify your details.

Before you sign any paperwork, take a moment to look at the landscape. This quick breakdown compares how several major players stack up against one another. It should give you a bird’s-eye view of what to expect regarding amounts, timeframes, and their specific attitudes toward your credit profile.

Company Available Funds Repayment Period Processing Time Qualification Criteria
Avant Consult website Consult website Consult website Suited for low credit scores
OneMain Financial $1,500 – $30,000 24 – 60 months Within 1 hour Consult website
FastLendGo Consult website Consult website Consult website Poor or no credit history
Reprise Consult website Consult website Consult website Consult website
United Finance Max $20,000 Consult website Consult website Consult website
OppLoans Consult website Consult website Funds arrive same-day No impact on FICO score

Leading Lending Options Evaluated

1. Avant

Avant – avant.com

Avant acts like a financial co-pilot, helping people steer toward better economic health. They provide a tailored suite of options, ranging from credit cards to installment loans, that adapt to where you are in life. Their mission focuses on handing you the right implements to tackle debt or survive an unexpected rainy day.

You won’t find a predatory “payday” trap here; instead, Avant wants to walk beside you for the long haul. They are a fantastic pick if your needs go beyond a simple cash injection. Because they offer tools for debt consolidation, they function as a versatile ally for anyone looking to tidy up their messy financial life.

If your high-interest credit card bills are starting to feel like a heavy weight, an installment loan from Avant might be the life raft you need. By merging those various payments into one single, manageable monthly installment, you could find some breathing room, provided the interest rate works in your favor.

Pros:
  • Provides various financial instruments like debt consolidation and credit cards.
  • Focused on helping clients reach their long-term financial milestones.
  • Offers flexible solutions suited for different stages of life.
Cons:
  • Exact terms and interest rates aren’t clearly stated for every credit bracket.

2. OneMain Financial

OneMain Financial – onemainfinancial.com

Sometimes, you just need to look a human being in the eye. OneMain Financial fills that void with a massive network of over 1,300 physical branches. This face-to-face access is a goldmine for borrowers with non-standard income, like freelancers or the self-employed, whose stories might get lost in a cold computer algorithm.

Walking into a branch allows you to sit down with a professional and lay out your unique circumstances. This personal connection can often unlock better loan terms than a purely digital application. They offer a wide range of personal loans, from $1,500 all the way up to $30,000, making them a sturdy choice for big projects like fixing a roof or consolidating debt.

If you are in a time crunch, you won’t be left hanging for long. Once the paperwork is signed and verification is complete in person, you could potentially see your funds within a single hour.

Pros:
  • Extensive network of physical locations for face-to-face assistance.
  • Rapid fund disbursement, potentially just one hour after signing.
  • Substantial loan limits reaching up to $30,000.
Cons:
  • Some loan options require a branch visit or a response to a mailed offer.

3. FastLendGo

FastLendGo – fastlendgo.com

Think of FastLendGo as a high-speed digital bridge connecting you to local lending opportunities. Rather than wasting your afternoon playing phone tag with various banks, FastLendGo pulls multiple offers into one clean, efficient dashboard. Whether you need a tiny $500 cushion for a sudden repair or a larger sum for a new roof or car, they have you covered.

The platform is built for the modern, fast-paced lifestyle, working beautifully on a smartphone for those on the move. They specifically target people facing financial hurdles, providing options for those with no credit history or even bad credit. It is the perfect “near me” solution for anyone wanting to bypass the long lines of a traditional bank.

By putting all the cards on the table through a comparison model, you take back control. You get to see exactly which lender is offering the most competitive rate for your specific credit profile, giving you the full picture at a single glance.

Pros:
  • Supports many loan uses, including dental and automotive needs.
  • Accommodates various credit levels, including those with no credit history.
  • Provides an efficient way to compare local lenders.
Cons:
  • Works as a comparison engine, so actual terms depend on the matched lender.

4. Reprise

Reprise – reprise.com

Reprise plays in a different league by utilizing cutting-edge AI to handle data and demonstrations. While they primarily exist to provide a platform for enterprise-level demos, they represent the fascinating point where high-tech data meets professional services. In a world where everything is being automated, they showcase how deep data management has evolved.

For professionals who live and breathe technology, they offer sophisticated features like full clones and data injection. They aren’t really a traditional lender for your personal debt; instead, they are a specialized tool for managing business presentations at a high level. They serve as a unique reminder of the diverse tech landscape currently shaping the fintech world.

Pros:
  • Utilizes advanced AI technology for creating demos.
  • Offers high-level capabilities for injecting data.
  • Provides an efficient way to manage professional presentations.
Cons:
  • Not a standard personal loan provider for consumer debt.

5. United Finance

United Finance – unitedfinance.com

United Finance is a true veteran of the industry, having kept its doors open since 1922. They specialize in making personal and auto loans straightforward and easy to understand. Their long history is a testament to the stability they provide to their clients—a refreshing change of pace compared to the “flashy” fintech startups that often vanish overnight.

This decades-long track record suggests they truly understand how to manage risk and navigate the lending cycle. They offer personal loans that can go up to $20,000. Additionally, Oregon residents can take advantage of their high-yield certificates. This mix of lending and investment products makes them a very reliable choice for those seeking a traditional institution.

Pros:
  • Boasts an incredibly long history of stability.
  • Provides both auto and personal loan options.
  • Features investment products like high-yield certificates.
Cons:
  • Certain products, like investment certificates, may have geographic restrictions.

6. OppLoans

OppLoans – opploans.com

If speed is your main priority, OppLoans is built for the moment. Perhaps their greatest advantage is that applying won’t touch your FICO score. This is a massive win for anyone trying to nurse a 500 credit score back to health, because when you are rebuilding, every single point is precious.

Since a “hard inquiry” can act like a weight on your score, being able to check your eligibility without penalty is a game-changer. They partner with banks to deliver rapid decisions, often within just a few minutes. If you are facing a crisis, they can even offer same-day funding to get you through the storm.

This is the ideal choice for urgent emergencies where waiting even one day might mean a late fee or a utility shut-off. It is a tool designed for when you need a solution right this second.

Pros:
  • Checking eligibility does not impact your FICO score.
  • Same-day funding is available for those who are approved.
  • Features a very rapid decision-making process.
Cons:
  • Best suited for urgent, short-term needs rather than long-term wealth building.

Hunting for the Right Financing

If you find yourself staring down a 500 credit score, you might feel like you’re running a race with weights tied to your ankles. The urge to jump at the very first hand extended to you is incredibly strong. Yet, the path of least resistance rarely leads to the most favorable destination for your wallet.

You must dive deep into the murky details regarding how much this capital actually costs you. A quick loan might seem like a lifesaver in a pinch, but it can quickly turn into a millstone around your neck if the interest rates are predatory. Don’t let a momentary solution create a long-term financial headache.

Watch out for those sneaky “origination fees” that lenders often hide in the shadows. These are essentially upfront charges sliced directly from your borrowed funds. Imagine you secure a $1,000 loan, but the lender deducts a $100 fee immediately. You walk away with just $900 in hand, yet your debt remains $1,000. It is a bitter pill to swallow.

Many borrowers stumble by failing to distinguish between a soft inquiry and a hard credit pull. I always suggest hunting for lenders that permit you to verify your eligibility through a soft pull first. This method lets you window-shop for better rates without bruising your credit score further. It is a smart way to play the field.

Treat this comparison phase as a tactical mission to gather diverse quotes. By weighing various APRs against one another, you ensure you aren’t paying a premium just for the luxury of having cash today. It is better to spend a little time now than to lose hundreds later to high interest.
Another trap involves getting caught up in a long repayment timeline. While a 60-month term might make your monthly bills look manageable, the math tells a different story. You could end up paying back almost twice what you initially took out because of the extended interest accumulation. It is a costly way to live.

Try to find a sweet spot where the monthly installment fits your budget without suffocating your lifestyle. You want to leave some breathing room in your bank account so you can build an emergency fund. This extra cushion helps you climb out of a low score rather than staying stuck in a debt cycle.

Ultimately, look at this loan as a temporary bridge to get you from point A to point B. It should be a tool for progress, not a permanent anchor that keeps you tethered to your past financial mistakes.

Best Places to Secure a 520 Credit Score Personal Loan Right Now

By Uncategorized
520 credit score personal loan

Best Places to Secure a 520 Credit Score Personal Loan Right Now

Last updated: 2026-10-16

Trying to navigate your finances with a 520 credit score is akin to trekking uphill through a swamp. When your rating slides into the 500s, traditional banks tend to pull up the drawbridge. It becomes a relentless loop of seeking assistance, only to collect a mountain of rejection notices.

This specific rating often stems from a cocktail of heavy credit usage, late payments, or perhaps a recent bankruptcy. Dealing with collections can also drag your standing down. Beyond the math, the mental fatigue of constant denial is a heavy weight to carry.

We have curated this list to highlight lenders that peek past that one difficult digit. If your score is low, you require transparency and rapid response times. You cannot afford to wait weeks for a manual review when an urgent medical debt or a broken furnace demands immediate payment.

Our team cut through the clutter to find genuine options for people facing immediate hardship. We specifically sought out firms that weigh alternative metrics. By looking at your bank activity or steady income, they build a more complete picture of your ability to repay.

  1. Max Cash
  2. Avant
  3. JetzLoan
  4. Acorn Finance
  5. NetCredit
  6. Upgrade

Our Methodology for Rating Lenders

Finding a way out of a financial hole when your credit rating sits at 520 is like walking a tightrope in a storm. It is incredibly difficult. Because of this, our team placed a premium on finding lenders who actually welcome people facing major credit hurdles.

We didn’t care about perfection; we cared about possibility. Our main goal was to pinpoint companies that grant approvals even when a flawless payment history is out of reach. Speed was another deal-breaker for us. We sought out streamlined, user-friendly digital portals.

Specifically, we hunted for web-based services capable of finishing your paperwork in less than ten minutes. It wasn’t just about the raw numbers, though. We examined the breadth of their inventory to ensure they had something for everyone.

Whether you are hunting for a small lifeline to pay a sudden electric bill or a substantial pile of cash for renovations, diversity matters. We wanted to ensure these providers didn’t just offer one size fits all solutions.

We also took a hard look at “soft pull” options. You should never have to risk your fragile score by “shotgunning” applications across the internet. That frantic habit of blasting out dozens of requests can bury a consumer in even more damage.

Transparency is the name of the game when things get dicey. For those navigating a 520 score, hidden costs or penalties for paying early can feel like a trap. We prioritized lenders who lay their APRs bare before you ever sign on the dotted line.

Provider Funding Range Processing Time Score Impact for Quotes
Max Cash $250 – $10,000+ Minutes No Obligation
Avant See site See site See site
JetzLoan $500 – $35,000 As little as 24 hours No impact
Acorn Finance See site See site No impact
NetCredit Up to $10,000 Same-day available No impact
Upgrade Up to $50,000 Fast funding Won’t impact score

Top-Tier Lending Options for Subprime Borrowers

1. Max Cash

Max Cash – maxcash.com

When mainstream banks shut their doors, Max Cash serves as a vital lifeline. Their product catalog is quite diverse, spanning from tiny micro-loans to much larger installment-based financing. They understand that time is of the essence when you are facing a sudden cash crunch.

This makes them a perfect fit for those navigating “bridge financing” scenarios. If you are simply waiting for a paycheck or a tax refund to hit your account, they can bridge that gap. It is a reliable lifeline for anyone needing quick liquidity to tackle an emergency.

The flexibility here is impressive, with borrowing limits starting at a modest $250 and scaling up past the $10,000 mark. Because they cater to various scales of necessity, they are a versatile ally. Small loans are particularly handy for minor expenses that don’t require a long-term debt commitment.

Advantages:

  • Flexible amounts ranging from $250 to over $10,000.
  • Lightning-fast processing that takes only minutes.
  • Initial quotes are provided without any obligation.

Disadvantages:

  • The emphasis on extreme speed may result in higher interest rates.

2. Avant

Avant – avant.com

Avant operates on the belief that a person is much more than a solitary digits on a report. Their mission is to facilitate upward financial mobility through various tools designed to manage debt or cover unexpected household costs. They offer a structured path for those seeking stability.

They don’t just obsess over FICO numbers; instead, their underwriting process might weigh your employment history or your banking relationships. Whether your goal is a new credit card or funding a home renovation, they provide tailored options for your life.

If you are slowly climbing out of the credit basement, Avant is a fantastic companion. As your score inches from 520 toward the 600 mark, they act as a long-term partner in your progress rather than a mere temporary band-aid for your problems.

Advantages:

  • Wide variety of options, from credit cards to debt consolidation.
  • Built specifically to help users progress financially.
  • Versatile solutions that adapt to different life stages.

Disadvantages:

  • Minimum credit thresholds might disqualify those with the lowest scores.

3. JetzLoan

JetzLoan – jetzloan.com

If the slow pace of traditional banking drives you crazy, JetzLoan is a breath of fresh air. They act as a high-speed connector, linking you to premium lenders in just a few minutes. It is an incredibly efficient way for modern, busy individuals to shop around.

You won’t have to spend your afternoon filling out a mountain of different applications. Their marketplace model handles the heavy lifting for you. With a reputation for high customer satisfaction and over 500,000 loans funded, they are built for high-speed results.

The ability to hunt for rates without a hard credit inquiry is a massive safety net. When your score is sitting at 520, a single unnecessary inquiry could drag you into the 400s. JetzLoan protects your credit health while you search.

Advantages:

  • Potential to receive your funds in as little as 24 hours.
  • Rate comparisons that don’t require a hard credit pull.
  • Consistently high ratings from satisfied customers.

Disadvantages:

  • How quickly you get paid depends on the specific lender you find.

4. Acorn Finance

Acorn Finance – acornfinance.com

Acorn Finance is a niche powerhouse, specifically engineered for those tackling home improvement projects. They operate as a marketplace that matches you with various lenders. This is a godsend if you are trying to upgrade your kitchen or fix up a backyard deck.

Many homeowners view their property as their primary wealth builder. Using a loan to increase home value is a smart way to build equity even when your credit is currently in the red. They even allow contractors to offer financing without charging any dealer fees.

This makes them a standout for large-scale, project-specific funding. You can shop around for personalized rates without touching your credit score. For example, if a new roof is required, you can compare different specialists through Acorn to find the best APR for your profile.

Advantages:

  • Focused expertise in financing for home improvement contractors.
  • Checking rates will not impact your credit score.
  • Certain contractor options feature zero dealer fees.

Disadvantages:

  • The narrow focus means they might not fit general cash needs.

5. NetCredit

NetCredit – netcredit.com

With the slogan “Credit to the People,” NetCredit operates under the philosophy that you are more than a data point. This mindset leads them to use sophisticated algorithms that look at your holistic financial health rather than just a single FICO number.

By analyzing your banking patterns, they can assess your ability to repay, which is a total game-changer for people with thin credit histories. They offer everything from personal loans to lines of credit, with the possibility of seeing funds the same day you apply.

This is perfect for emergencies, like a sudden car breakdown that threatens your ability to get to work. They strive to be a transparent, empathetic alternative to the big banks, providing a reliable experience for those who are often overlooked.

Advantages:

  • The option to receive funding on the same day.
  • Advanced technology looks beyond just your credit score.
  • Checking your eligibility is completely free and won’t hurt your FICO.

Disadvantages:

  • Total loan amounts are limited to a maximum of $10,000.

6. Upgrade

Upgrade – upgrade.com

Upgrade is a major player in the personal loan industry, serving a massive variety of borrowers. They provide substantial funding, reaching up to $50,000, which is ideal for life-altering events or consolidating expensive debt. If high-interest credit cards are sinking your score, this is your exit ramp.

Consolidating those various high-interest balances into one single, lower-interest installment loan can act as a catalyst for credit recovery. Their digital platform is built for the modern age, allowing you to see your potential rates in mere minutes.

They also include extra perks, such as cash back on select purchases, helping you rebuild your financial footing while you manage your money. By providing both a loan and cash-flow tools, they act as a holistic financial partner for your journey.

Advantages:

  • Generous loan limits that go up to $50,000.
  • Rapid rate checks and quick funding cycles.
  • Bonus features like cash-back on specific checking accounts.

Disadvantages:

  • The variety of products might be too much for someone seeking only a basic loan.

Financial Implications of Subprime Loans

If your credit profile sits around 520, you need to brace yourself for a bit of a sting. Borrowing money isn’t a walk in the park when your score is low; it’s going to cost significantly more than it would for a person boasting a 750 rating. Lenders view your score through a lens of uncertainty, attaching higher interest rates as a safety net to cover potential defaults.

Think of these extra percentages as a “risk premium” that banks demand to offset the gamble they are taking on you. Before signing any paperwork, you must grasp the fundamental distinction between how interest is tallied. Understanding the mechanics of your debt is the only way to avoid being blindsided by rising balances later on.

Simple interest is quite straightforward, as it only applies to the original sum you borrowed. On the flip side, compound interest is a different beast entirely. It calculates charges based on your principal plus any unpaid interest, which can cause your debt to snowball out of control if you stick only to minimum monthly payments.

You should always hunt down the “Total Cost of Loan” metric during your search. A salesperson might tempt you with a $150 monthly installment, which feels like a breeze for your budget. However, if that term stretches out to 60 months, that $5,000 loan could ultimately cost you $9,000 in total repayments.

That gap represents a $4,000 fee just for the access to capital. It is worth asking yourself: “How much total interest will I pay over the life of this loan?” Taking the time to ask this one specific question can save you thousands of dollars and stop years of grueling financial struggle before they even begin.

Pathways to Credit Improvement Post-Loan

View obtaining a loan with a 520 score as a strategic stepping stone rather than a mere quick fix for immediate expenses. Think of it as a reset button for your financial health. If you utilize this capital to combine various debts, use that newfound space to clear those old balances entirely.

The real danger lies in the temptation to keep spending. If you wipe out a credit card using your loan but then quickly max out that card again, you’ve effectively doubled your liabilities. This mistake is a recipe for disaster that could cause your score to plummet even further than it is now.

To squeeze every bit of value out of your loan and watch those numbers climb, stick to these essential habits:

  • Set and forget your payments: A single slip-up on a deadline can slash your score by 50-100 points. To prevent this, schedule autopay for at least the minimum monthly amount to keep your record spotless.
  • Watch your credit usage: If your loan was meant to settle card balances, ensure your card usage stays below the 30% threshold. Managing this ratio is often the fastest way to see a significant jump in your rating.
  • Hold off on new credit: Once things stabilize, resist the urge to shop for new credit lines for the next 6-12 months. Your score needs a window of time to recognize and reward your consistent repayment habits.

Mastering the Application Journey

Navigating the financial landscape with a 520 score is like walking a tightrope during a storm. Every single step requires precision and careful thought. A common blunder that many people make is firing off numerous applications simultaneously to different lenders.

Every time a lender performs a “hard pull” on your file, your credit rating takes a direct hit. This can make your already shaky foundation even more unstable. It is better to hunt for lenders that offer “soft pull” rate checks first.

Checking rates this way is like window shopping in a luxury mall. You can compare prices and terms without any cost to your reputation. This method lets you find the most favorable terms without the sting of multiple credit inquiries.

Don’t let the siren song of a quick cash injection lead you into a trap. While a fast loan might patch a hole in your finances today, the long-term consequences can be heavy. You must scrutinize the fine print of your agreement.

If the interest rates are sky-high, you might find yourself staring at a mountain of debt rather than a solution. It is a slippery slope that many borrowers fall down. Always calculate the total cost of borrowing over the full life of the loan.

Looking only at the monthly installment is like looking at the tip of an iceberg. It hides the massive debt lurking beneath the surface. Ensure your choice actually paves a path toward better credit rather than digging a deeper hole.

Keep a sharp eye out for clauses regarding “prepayment penalties” tucked away in the contract. Some companies will actually charge you a fee if you try to settle your debt ahead of schedule. It sounds counterintuitive, but it is a real trap.

If a sudden windfall allows you to clear your balance early, you want to celebrate that victory. You shouldn’t be punished for being fiscally responsible or efficient with your money. Seek out lenders that cheer on your progress instead of taxing it.

Get a 550 credit score personal loan: Top 5 lenders to apply for today

By Uncategorized
550 credit score personal loan

Get a 550 credit score personal loan: Top 5 lenders to apply for today

Last updated: 2026-10-16

Navigating your finances while stuck with a 550 credit score often feels like trekking through thick sludge. It is a heavy burden to carry, particularly when life tosses an unexpected wrench into your plans. An emergency trip to the mechanic or a sudden trip to the dentist can drain your savings in a heartbeat.

You might find that mainstream banks pull the ladder up behind them, viewing a 550 rating as a hard “no.” Yet, a few niche lenders remain ready to lend a hand. These outfits utilize alternative metrics that peer beyond your standard FICO digits. They evaluate your steady paycheck and history with your current bank to gauge your reliability.

Searching for a financial safety net involves looking at much more than just the APR. You must balance the speed of the funding against the ultimate price of the loan. A low interest rate is vital for those thinking long-term. Conversely, some folks just need funds hit their account by tomorrow to dodge a late fee or an eviction.

We have curated a selection of dependable lenders for those navigating the fair to poor credit spectrum. This resource aims to simplify the heavy lifting involved in making quick, high-stakes choices. We want to help you find the right path forward during a tight squeeze.

  1. LendingPoint
  2. FastLendGo
  3. Max Cash
  4. Avant
  5. Reprise

Our Selection Methodology

Scouring the market for lenders that accept lower credit scores requires looking past the shiny advertisements. It is not merely about finding a firm that gives a thumbs up. The real goal is locating a provider that offers a fair path toward financial assistance.

We prioritize accessibility above all else. Can you actually secure the capital when your credit history has hit some bumps in the road? Simply being able to get approved is only half the battle if the fine print is filled with traps.

A company might brag about massive approval rates, but they aren’t a real lifeline if they hide sneaky service charges or punish you for paying off the debt early. You have to know the exact cost of your commitment before you sign any paperwork.

Our team analyzed providers specifically targeting the 550 score bracket. We focused our scrutiny on three pillars: availability, speed, and transparency. We looked at how rapidly they transfer cash, how candid they are regarding loan totals, and the diversity of their available products.

Every single candidate was vetted to ensure they provide a genuine way out of a pinch. We also put their mobile technology to the test. If a crisis strikes, you need to navigate the entire application on a smartphone while running errands.

A clunky or frustrating digital interface can become a massive obstacle when every minute counts. Our goal was to ensure these tools actually help you in an emergency rather than adding to your stress.

Lender Funding Range Credit Minimums Speed of Funds
LendingPoint $1,000 – $36,500 Fair Credit Fast Funding
FastLendGo $500 – $5,000+ Bad/Fair Credit Quick Access
Max Cash $250 – $10,000+ Bad Credit In Minutes
Avant See site 550 and above Fast Funding
Reprise See site See site See site

1. LendingPoint

LendingPoint – lendingpoint.com

LendingPoint serves as a bridge for individuals trying to walk away from financial tension and toward a more stable footing. They provide a broad spectrum of borrowing options, which makes them a very adaptable choice for many different needs.

You might find yourself needing a small chunk of change to cover a sudden doctor’s visit. Conversely, you may require a much larger sum to wipe out various old debts entirely.

Picture yourself staring at $15,000 in credit card debt with interest rates that feel like they’re suffocating you. A single consolidation loan from LendingPoint can pull all those disparate obligations into one neat, predictable monthly bill. It is an excellent way to stop playing “catch up” with multiple different due dates every single month.

This provider is a strong match for those tackling specific milestones, such as upgrading your home or reorganizing debt. Their digital setup is built for speed to respect your hectic life. You can submit paperwork and receive a verdict in mere minutes, which is a lifesaver when your budget is stretched thin.

Pros:

  • Extensive maximum borrowing limit reaching $36,500.
  • Checking your rates won’t hurt your credit score.
  • Wide range of uses from travel to weddings.

Cons:

  • Their eligibility requirements might be tougher than niche bad credit firms.

2. FastLendGo

FastLendGo – fastlendgo.com

FastLendGo is tailor-made for the person who feels like they need cash by yesterday. Their main specialty is providing rapid access for urgent needs like fixing a car or paying for a dentist visit.

Imagine your car’s alternator dies on a Friday and you must have it fixed by Monday to stay employed. Their specialized loan products are crafted to address that exact nightmare.

They sit in that sweet spot between traditional bank loans and the high-cost world of payday lenders. This setup provides much more long-term stability than a quick cash advance, but they move much faster than a standard big-name bank.

Whether you are looking for a $500 boost or a $5,000 loan, their tiered structure accommodates you. This flexibility is a godsend when your score is stuck in the tricky 550 territory. Instead of being saddled with a massive debt you can’t manage, you can pick a smaller amount that matches your specific crisis.

Pros:

  • Offers loans for specific emergencies like motorcycle or roof repairs.
  • Provides tiny loan amounts for very immediate needs.
  • Features options for first-time borrowers and high earners.

Cons:

  • The sheer volume of product types might be confusing for some users.

3. Max Cash

Max Cash – maxcash.com

Max Cash functions like a digital matchmaker for financial relief. For those wrestling with a 550 score, they provide a streamlined way to encounter personalized lender matches tailored to you. Their technology links you with exactly what you require, saving you from the headache of browsing hundreds of different websites manually.

Rather than offering a generic, one-size-fits-all solution, they employ a smart algorithm to locate the lender most likely to say yes to your specific profile. It is a matter of efficiency rather than blindly casting a wide net and hoping for the best.

They excel at providing highly accessible amounts, with entries as low as $250. This is ideal for those micro-emergencies where a large loan would simply be overkill. If you have a $300 utility bill, taking out a $3,000 loan would be a massive mistake. Max Cash lets you fix the small leaks without the heavy weight of excessive interest.
Pros:

  • Incredibly low starting points for loan amounts.
  • Rapid inquiry process that carries no obligation.
  • Manages a huge variety of different credit backgrounds.

Cons:

  • Their focus on small amounts might not work for major debt restructuring.

4. Avant

Avant – avant.com

Avant is a significant contender for anyone looking to make forward progress in their financial journey. They have built a reputation for considering applicants whose scores sit around 550. This makes them a crucial option if you have been repeatedly turned away by traditional banking institutions.

While some lenders only fixate on your FICO score, Avant takes a much broader look at your overall financial health. This can be a total game-changer for people who have faced recent financial setbacks but still maintain a regular, steady income.

This lender focuses on providing long-term solutions, such as debt consolidation or funding home improvements. If you manage to get your application in before their afternoon cutoff, you might see the funds arrive in your account remarkably fast. Their platform is built for the modern user who wants to run their finances entirely through a mobile app.

Pros:

  • Specifically targets the 550 credit score demographic.
  • Capable of very fast funding for those who are approved.
  • Provides a mix of loans and credit cards for various needs.

Cons:

  • Approval is highly contingent on specific timing and your unique criteria.

5. Reprise

Reprise – reprise.com

Reprise functions in a totally different arena, concentrating on high-tech tools and AI-driven solutions. It is not a standard consumer personal loan lender like the other companies on this list. Instead, it represents the cutting edge of data management and financial technology.

They are much better suited for businesses or tech-savvy entities looking for advanced data injection and demo creation. It is a specialized toolkit for people who need to present complex datasets in an interactive format, rather than a regular consumer looking for a quick loan.

If a fintech startup needs to show potential investors exactly how a loan application workflow functions, Reprise provides the tools to build that immersive experience. It is about the sophisticated technology operating behind the curtain rather than a customer standing at a teller window.

Pros:

  • Very advanced AI toolkit used for creating demos.
  • Streamlined capabilities for data injection and presentation.
  • Makes sharing product tours incredibly easy.

Cons:

  • This is not a traditional provider of personal loans for individuals.

The Real Price of Credit: Measuring APR Against Monthly Obligations

When your finances are in a tight spot, it is incredibly tempting to chase the smallest possible monthly bill. You might find yourself comparing two different loan proposals side by side. Imagine one asks for $50 every month, while the other requires $75 to keep the account current.

At first glance, the $50 choice feels like a lifesaver because it keeps more cash in your wallet right now. It feels like a breath of fresh air during a storm. However, relying on this single metric is like navigating a ship without a compass; it is a recipe for disaster.

The actual expense of your debt is hidden within the Annual Percentage Rate, or APR. A bank could lower your immediate monthly burden by simply stretching your repayment period out to seven years. This might make the monthly sting feel much less intense on a day-to-day basis.

The catch is that interest accumulates like snow in a drift during a blizzard. While your monthly obligation stays low, the interest can balloon significantly. You might find yourself returning much more than you originally borrowed, potentially paying back double or even triple the initial amount.

You need to look at the big picture rather than just the immediate snapshot. Before signing any paperwork, ask yourself a critical question: “How much cash will have left my bank account by the time this debt is fully settled?” This is the ultimate litmus test.

If that final sum is vastly larger than the principal amount you received, you are essentially buying time. You are paying a steep premium for the luxury of a smaller monthly installment. It is vital to weigh that convenience against the heavy weight of long-term interest costs.

Navigating the Differences Between Hard and Soft Credit Checks

If your credit score is hovering around 550, you need to grasp how your search for financing influences your standing. Not all credit checks are created equal in the eyes of the bureaus. You will encounter two distinct categories: soft inquiries and hard inquiries.

A soft pull happens when a company scans your history to see if you qualify for a deal. You see this most often when clicking buttons that say “check your rate” on various websites. It is like testing the waters before diving into a deep pool.

These specific checks are harmless to your financial health. They remain invisible to other banks when they review your profile. Because they do not impact your score, you can use them to window shop for better terms without any fear of a penalty.

On the other hand, a hard pull is triggered once you formally apply for a credit card or a personal loan. This tells the credit reporting agencies that you are hungry for new debt. To a lender, this sudden hunger can signal a potential risk to your stability.

Every time a hard inquiry lands on your report, your score might take a minor, fleeting hit. While these dips are usually small, they can add up if you are not careful. If your goal is to mend your credit, treat these pulls like precious resources that shouldn’t be wasted.

Selecting a financial partner is much like shopping for footwear. If the fit is off, the entire trek becomes a literal and figurative headache. You must scrutinize the complete cost of borrowing rather than just eyeing the monthly installment. A small monthly bill might simply be a mask for a predatory interest rate that slowly bleeds your bank account dry.

Always demand a formal truth-in-lending disclosure from your chosen provider. Since this is a mandatory legal document, it removes any ambiguity by detailing the full finance charge. Knowing exactly how much cash will leave your pocket by the end of the term provides much-needed clarity.

Avoid the “shotgun approach” of spamming applications across various banks at once. When you do this, a flurry of hard inquiries hits your credit profile simultaneously. This makes you appear financially distressed to potential creditors, which can cause your score to plummet even further. It is much better to target one or two specific lenders that actually align with your current goals.

Don’t ignore the tiny text hidden in the contract. It is vital to grasp the specific repayment schedule and look out for any prepayment penalties. Some companies will actually fine you for being responsible and trying to settle your debt ahead of schedule. You shouldn’t be penalized when you finally get your finances back on track. Treat these loans as a bridge to recovery, but walk across it carefully.

fastlendgo.com

Secure Your 100k Personal Loan with Fast Approval Online

By Uncategorized
100k personal loan

Secure Your 100k Personal Loan with Fast Approval Online

Analyzing the Financial Toll of a $100,000 Unsecured Loan

Requesting a $100,000 unsecured loan can feel like betting your life savings on a single hand of blackjack. You might strike gold, or the house might walk away with your shirt. Your credit history serves as the ultimate gatekeeper, determining whether you get a fair deal or get fleeced.

If your credit score is top-tier, you might snag APRs starting near 7%. That is the dream scenario for any borrower. However, if your credit profile is a bit shaky, those figures can skyrocket. It is quite common to see rates hit 36% when banks decide your risk is too high.

Think of your credit score as a barometer for your financial future. A high score brings clear skies and cheap money, while a low score signals a massive storm of interest charges. This gap can turn a simple monthly obligation into a crushing weight that haunts your sleep.

When you shop around, the landscape changes drastically. Traditional banks want to see a lifetime of stability, while online lenders often prioritize speed over low rates. Credit unions often provide a sweet spot, offering competitive terms that feel much more personalized and less like a robotic calculation.

Term Durations and Monthly Obligations

Time functions as a double-edged sword when you are managing a $100,000 principal. Stretching the loan over more years might make your monthly bill look much more palatable at first glance. However, that extra time allows interest to pile up, eroding your wealth like a slow, persistent tide.

The math tells a sobering story. Securing a 9.49% APR keeps your monthly out-of-pocket cost relatively steady. Conversely, if you end up with a 36% APR, the math becomes eye-watering. You must run these figures through a financial tool before signing any binding agreement.

Review this comparison for a $100,000 loan to see how drastically the numbers shift:

Projected APR Duration Monthly Outlay
9.49% 3 Years $3,215
9.49% 5 Years $2,100
18% 5 Years $2,566
36% 5 Years $3,450

As the data highlights, the gap between a 9.49% and a 36% rate over a five-year term is nearly $900 every month. That represents cash that could have built your retirement or a house fund. It is an incredibly high tax for taking on high-interest debt.

The True Cost of Borrowing

The headline number on a loan offer is rarely what you actually pay in total. You have to factor in hidden fees, like origination charges. These are often sliced off your $100,000 upfront, meaning your actual cash in hand will be less than the amount you borrowed.

If you want to hunt for better terms, consider using specialized platforms like https://fastlendgo.com to see how different setups affect your long-term wealth. Also, watch out for prepayment penalties. These sneaky clauses can make it expensive to pay your debt off ahead of schedule.

The total interest paid is the most vital number you will ever see. A $100,000 loan at 10% for five years might result in about $26,000 in total interest. If that rate climbs to 25%, you are suddenly on the hook for an additional $40,000 in interest alone.
Always pose this question to your lender: “What is the full sum I will have paid once this is done?” It is a simple query that provides a much-needed reality check. Never let a low monthly payment be the only metric that drives your choice.

Evaluating Top-Tier Lenders and Maximum Borrowing Limits

Hunting for a six-figure payout is a whole different ballgame compared to seeking a quick fix for minor expenses. Once you step into the $100,000 realm, you are no longer just a face in the crowd. To the lender, you represent a major financial entity that requires intense scrutiny.

Banks will put your entire history under a microscope to determine if lending to you is a smart move. They aren’t just checking boxes; they are weighing every single detail of your fiscal past. It is a high-stakes game of risk assessment from the very first application.

SoFi has carved out a significant niche in this particular marketplace. They are widely recognized for providing unsecured personal loans that can climb as high as $100,000. For many, this is the golden ticket to erasing massive mountains of debt or funding a major life pivot without risking their home.

Axos Bank represents a different, perhaps more accessible, tier of lending. This institution usually focuses on individuals needing between $7,000 and $50,000. While you likely won’t walk away with a $100,000 check from them, their processes are famously straightforward and easy to navigate for the average person.

Many other lenders occupy the middle ground, serving as the reliable workhorses of the industry. They don’t offer massive windfalls, but they provide the necessary fuel for those who need substantial sums without needing to go into the highest brackets.

The Tug-of-War Between Risk and Collateral

Choosing between a secured or unsecured loan is one of the most pivotal decisions you will make. Think of an unsecured loan as a handshake agreement built on your personal reputation. You won’t have to pledge your car or your house as a guarantee, keeping your property safe if things go south.

Of course, this type of trust comes with a price tag, often manifesting as higher interest rates. It is essentially a way to borrow money based on the strength of your word and your creditworthiness alone, rather than any physical asset.

Secured loans operate on a completely different philosophy. Here, you must put skin in the game by offering an asset, such as a savings account or a vehicle, as collateral. If you hit a rough patch and miss payments, the bank has the right to seize that asset.

This safety net for the lender is a win for your wallet in another way. Because the bank’s risk is lower, they often reward you with much more favorable interest rates. It is a classic trade-off: providing security to gain better pricing.

If you are in a rush, the digital age has provided some incredible shortcuts. Modern lenders frequently allow for lightning-fast online prequalifications using a “soft credit pull.” It is like window shopping for expensive electronics without actually hitting the “buy” button.

This method allows you to scout for the best deals without causing a dent in your credit score. It is a total game-changer for anyone wanting to shop around. You can weigh various offers side-by-side before ever committing to a hard inquiry that might impact your standing.

The following table illustrates how different loan structures and amounts can impact your borrowing experience:

Category Ceiling Amount Typical Duration
High-Limit Unsecured $100,000 Up to 7 Years
Mid-Range Personal $50,000 3 to 6 Years
Small Personal Loan $7,000 2 to 5 Years
Secured Loan Variable Variable

Navigating Repayment Cycles and Timing

The moment you sign your name, the clock starts its relentless march forward. Most lenders give you a menu of repayment options, usually spanning from 3 to 6 years. Opting for a shorter duration is akin to a high-speed sprint; you’ll burn through the debt faster and pay less interest, but your monthly obligation will be much heavier.

Conversely, taking the long route is more like a steady marathon. This approach keeps your monthly cash flow flexible, leaving you more wiggle room for daily living costs. However, you have to keep your eyes peeled, because stretching out that debt can cause interest to snowball, potentially costing you thousands extra.

The goal is to hit that “sweet spot” where the monthly bill doesn’t crush your budget, yet the total interest doesn’t bleed your savings dry. Don’t be a pushover and just accept the first offer that hits your inbox. Do the math carefully and ensure the terms truly align with your long-term life goals.

How to Effectively Deploy Significant Personal Loans

Streamlining Your Debt Obligations

Picture yourself staring down a mountain of high-interest credit card statements every single month. It can feel like you are desperately trying to tread water against a relentless tide of compounding interest. A $100,000 loan can act as a sturdy life raft, helping you gather those expensive, scattered balances into one single, manageable monthly payment.
This strategic shift can provide a massive boost to your monthly cash flow. By migrating high-interest debt into an unsecured loan with a lower rate, you are essentially stopping the financial bleeding. Instead of fighting a dozen different battles with varying due dates, you focus your energy on just one.

Many borrowers discover that securing rates as low as 9.49% APR makes a world of difference compared to the 20% or 30% interest rates typically found on revolving credit cards. This isn’t just about making life easier; it’s a calculated maneuver to preserve your hard-earned cash.

When you consolidate, you are essentially trading “expensive” debt for much “cheaper” debt. This can slash the total amount you pay over the life of the loan, provided you don’t fall into the trap of running up those credit card balances once they are cleared. Success requires ironclad discipline to ensure you don’t treat a clean slate as a license to overspend.

Navigating Major Life Changes

Life often throws unexpected curveballs that demand immediate, heavy-duty capital. A sudden medical emergency can feel like a devastating financial gut punch, potentially draining your entire savings in a heartbeat. In these high-stakes moments, a large personal loan provides the necessary liquidity to cover costs without risking your home or long-term security.

Home renovations represent another classic reason to seek out a substantial sum. Perhaps you are dreaming of a kitchen remodel or adding a second story to boost your property’s market value. Utilizing $100,000 for these upgrades can be a brilliant investment, as the equity gained often outweighs the cost of the financing itself.

Some individuals utilize this capital to bridge the gap during a sudden career transition or to fund significant life events like a wedding or a relocation. It acts as a way to smooth out the jagged edges of life’s most expensive moments. It provides a sense of stability when everything else feels like it is in flux.

When you use a lump sum for these purposes, you are essentially pre-funding your future needs. Instead of paying small, annoying amounts as they arise, you have the firepower to tackle an entire project or bill at once. This often grants you better pricing from contractors or more significant negotiating power with service providers.

Strategic Capital and the Power of Fixed Rates

For the entrepreneurial spirit, a $100,000 windfall can serve as vital seed money for a side business or a major capital investment. Whether you are buying new equipment, upgrading your tech, or investing in a small franchise, having a large lump sum allows you to strike while the iron is hot. It turns a “maybe” into a “now.”

One of the most powerful features of these large loans is the ability to lock in a fixed rate. This provides immense peace of mind. Unlike variable rates that can swing wildly, a fixed rate ensures your monthly payment stays exactly the same from the very first month to the very last.
This predictability is the cornerstone of a healthy, sustainable budget. You won’t wake up one morning to find your interest rate has spiked, suddenly eating into your grocery money. It allows you to plan your life with confidence, knowing exactly what your financial obligations will be for the next several years.
When you manage a large sum through a fixed-rate structure, you are effectively buying certainty. In an unpredictable economy, that certainty is worth its weight in gold. It transforms a potentially volatile financial situation into a predictable, scheduled part of your monthly household management.

The Mathematics of Financial Efficiency

Is it better to take one giant loan or several smaller ones? Many people assume that breaking things up is easier, but the math often tells a different story. Multiple loans mean multiple origination fees, multiple interest rates, and a cluttered dashboard of due dates that can easily lead to accidental late fees.

Taking one large $100,000 loan can be far more cost-effective than taking five separate $20,000 loans. By consolidating your needs into a single request, you often secure a better overall interest rate and significantly reduce the administrative headache. It is about streamlining your financial life to maximize every single dollar you earn.

Consider the following comparison of how different borrowing structures might impact your total costs:

Approach Complexity Level Total Interest Risk Management Effort
Single $100,000 Loan Low Lower (due to lower APR) Minimal
Multiple $20,000 Loans High Higher (compounding effects) Significant
Small Revolving Credit Very High Extremely High Constant

Ultimately, the goal is to minimize the “leakage” of your wealth. Every dollar lost to extra interest or late fees is a dollar that isn’t working for you in a savings account or a retirement fund. Choosing the most efficient loan structure is a key step in building real, lasting wealth.

Navigating the Loan Lifecycle and Eligibility Criteria

From Initial Interest to Receiving Your Funds

Securing a $100,000 loan is less like a quick dash and more like a carefully paced marathon. Your first move should involve auditing your credit profile to see exactly where you stand. Taking this step prevents you from wandering blindly into negotiations, only to find that interest rates are much steeper than you anticipated.

Once your credit profile is clear, the real heavy lifting begins. Finding a financial institution that aligns with your unique profile is paramount. Once you officially apply, the bank will conduct a deep dive into your fiscal history. Depending on the specific lender, this scrutiny might last a few days or drag on for several weeks.

Once the underwriters grant you the green light, you will execute the final legal documents to cement your specific terms. The final stage is the transfer of capital directly into your personal bank account. While the sequence can feel quite hectic, sticking to the established order helps you avoid sudden financial stumbles.

To maintain clarity, view the progression through these core milestones:

  • Credit Assessment: Reviewing your current standing and numerical score.
  • Prequalification Stage: Obtaining a non-binding estimate of your potential terms.
  • Official Submission: Filing the formal request to secure $100,000.
  • Underwriting Process: The institution validates every piece of data you provided.
  • Authorization and Payout: Signing your contract and accessing the cash.

Calculating the Cost Before Committing

Before you press that “submit” button, you must run the numbers carefully. It is incredibly easy to get intoxicated by the idea of a $100,000 injection, but the recurring monthly reality can be quite a reality check. You must know your exact monthly obligation to ensure your current lifestyle can support the added weight.

Try using a digital calculator to model various financial scenarios. For instance, if you take out $100,000 at a 10% interest rate for a five-year term, that monthly bill will be substantial. If that figure feels uncomfortable, consider reducing the principal or stretching out the repayment window to find a more manageable equilibrium.

Ignoring these monthly outflows is akin to driving a long distance without watching your fuel gauge. You might feel quite confident while the tank is full, but realizing you cannot afford the next refill can leave you stranded. Always prioritize a payment schedule that integrates effortlessly into your existing budget.

Review these approximate monthly costs for a $100,000 debt:

Annual Percentage Rate (APR) Term Duration Projected Monthly Installment
7% 5 Years ~$1,980
12% 5 Years ~$2,224
18% 5 Years ~$2,566

Validating Your Economic Profile

Banks do not simply hand over massive piles of cash based on a simple promise. They require absolute certainty regarding your identity and your reported earnings. Consequently, you will need to assemble a significant dossier of paperwork to verify your employment and total income.

Standard requirements often include your most recent pay stubs, W-2 documents, or your latest tax filings. For those who are self-employed, the scrutiny intensifies significantly. You may be asked to produce several months of bank statements to demonstrate that your revenue streams are both consistent and predictable.

Do not overlook the essentials, such as your primary residence proof and a valid government ID. If your documentation is disorganized, the entire process could stall out entirely. Treat your financial paperwork like a high-stakes resume; it must be pristine, orderly, and ready for an immediate audit.

The Link Between Credit Scores and Rates

Think of your credit score as a high-tier VIP pass in the lending marketplace. This number essentially determines which group of interest rates you are eligible to access. While a top-tier score might unlock rates near 9.49% APR, a lower score could force you into much more expensive territory.

From a lender’s perspective, a credit score serves as a direct measurement of risk. Higher scores suggest lower risk, which empowers banks to offer you more favorable conditions. Conversely, if your rating is in the lower brackets, you might find that many lenders refuse to approve a loan as large as $100,000.

It is vital to remember that even a tiny fluctuation in your APR can lead to massive savings over the long haul. A difference of 2% might look like a mere trifle today, but that gap translates into a very expensive price tag over several years of interest.

Strategic Ways to Prequalify

The smartest way to shop for deals is by utilizing the prequalification mechanism. It is vital to understand that this is a “soft” inquiry. This specific type of check allows a lender to review your credit without impacting your score, which keeps your credit history pristine.

Use this period to cast a wide net across the market. Many digital lenders provide rapid, web-based prequalification that offers a sneak peek at your potential interest rates and loan limits. It is a low-risk way to weigh different options before you officially commit to an application.

Once you identify an offer that truly stands out, you can transition to the “hard” inquiry phase. This is the formal step that does affect your credit rating. By utilizing the prequalification route first, you ensure that you only trigger these impact-heavy inquiries when you are actually serious about a lender.

Crunching the Numbers: Expected Monthly Costs

Utilizing Loan Estimation Software

Before signing any binding paperwork, you really ought to sit down with a digital loan calculator. It serves as a vital tool to pull back the curtain on how high interest rates actually function. By playing around with various figures, you can visualize exactly how much of your monthly income will be swallowed by debt.

Think of this software as a financial crystal ball for your future spending. It offers a risk-free way to simulate different financial paths before they impact your real-world bank account. You can see how a $100,000 loan reacts under various interest scenarios, ranging from a modest 9.49% APR to much steeper, more costly tiers.

I have seen many borrowers realize the reality of their math is far different from their initial hopes. A debt that seems manageable on paper can quickly transform into a heavy anchor around your neck. Using these digital tools helps prevent that sudden “sticker shock” that often hits when that first massive bill arrives.

Comparing Different Debt Levels

The leap from a $30,000 balance to a $100,000 one isn’t just about adding extra zeros; it represents a fundamental shift in your economic reality. While a $30,000 loan might feel like a minor speed bump on your journey, a $100,000 loan is more akin to a grueling mountain climb.

When you take out $30,000, your monthly outlays stay relatively light and controlled. However, once you scale up to the $100,000 mark, interest starts compounding at a much more aggressive speed. You are essentially paying a premium for the luxury of holding a significantly larger pile of cash right now.

Take a look at this side-by-side comparison to grasp the immense difference in weight between these two principal amounts:

Comparison Case Total Principal Annual Interest Rate Predicted Monthly Installment
Minor Amount $30,000 10% ~$633
Major Amount $100,000 10% ~$2,124

Fixed vs. Variable Interest Rates

Deciding between a fixed-rate and a variable-rate structure is a lot like choosing between a steady stroll and a wild roller coaster ride. A fixed rate provides immense peace of mind because your monthly obligation remains identical throughout the entire term. It offers a predictable, stable path for your budget.

Conversely, variable rates can behave like a double-edged sword in your hands. They might appear more attractive initially due to a lower starting rate, which feels like a win for your wallet. However, if market rates climb, your monthly bill could skyrocket without any prior warning from the lender.

If you plan on carrying a $100,000 loan for a long duration, certainty is often worth paying a little more for. You certainly don’t want to wake up years from now to find your interest rate has jumped, turning your monthly budget into a chaotic mess of sudden expenses.

The Tug-of-War Between Duration and Cost

The length of your loan is a delicate balancing act that weighs your monthly cash flow against the total price of the debt. A longer term, such as six years, makes each individual payment much smaller and easier to stomach. This provides much-needed breathing room in your monthly finances.

However, there is always a hidden catch: time itself is quite expensive. The longer the period you have to pay back the money, the more total interest you will hand over. You might save $200 every month, but you could end up paying thousands of dollars extra to the bank in the long run.

It is absolutely vital to identify your personal “sweet spot” for repayment. You want a term long enough to keep your monthly payments comfortable, but short enough that you aren’t throwing a fortune away in interest. Finding this perfect equilibrium is the secret to maintaining long-term financial health.

The Impact of Early Repayment

Life is unpredictable, and sometimes you might find yourself with extra cash to throw at your mounting debt. This is where the concept of early repayment becomes your best friend. Paying down your principal more aggressively can save you a mountain of money in interest over time.

Before you start making extra payments, you must investigate any prepayment penalties. Some lenders include sneaky clauses that charge you a fee if you settle the loan too quickly. They essentially want to ensure they collect all the interest they originally projected from you.

Always scrutinize the fine print within your signed contract. If there are no such penalties, even a small extra $50 payment every month can shave many months off your total repayment schedule. It is a small sacrifice today that yields massive rewards for your future self.